4 mins min read • 18 November 2026


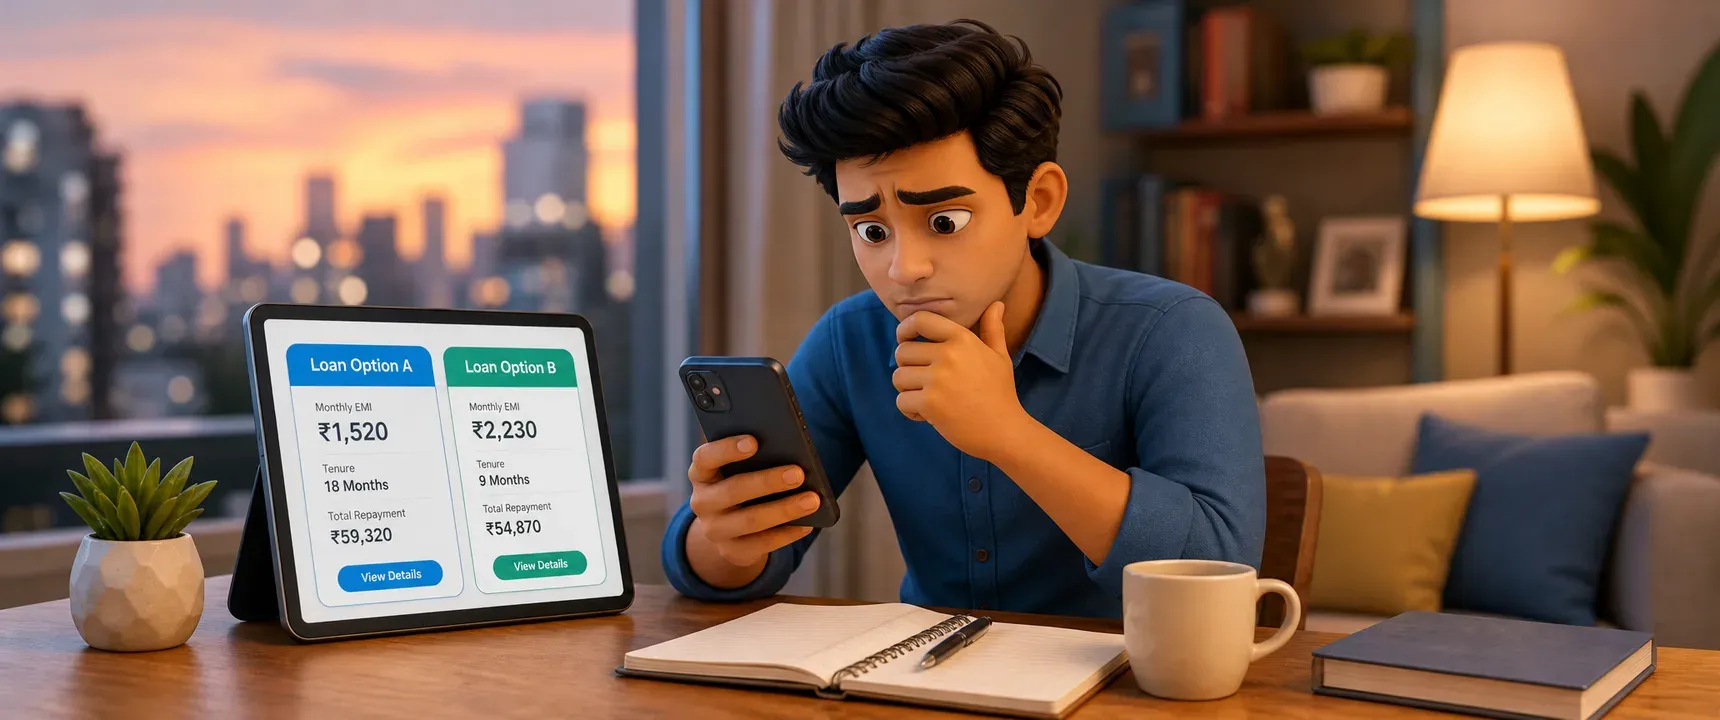
Table of content
Overview
Why small EMIs feel deceptive
5 mistakes to avoid
How to calculate EMI properly
Responsible borrowing matters
FAQs
A monthly EMI of Rs 1,500 feels painless. It barely dents your salary. So you sign the loan agreement without a second thought. Weeks later, you realize you committed to 24 months of payments, and the total amount you owe is far more than you expected. mPokket sees this pattern regularly among first time borrowers in India, and it is one of the most avoidable financial mistakes you can make.
Follow our Whatsapp Community for more offers and updates.
Join nowLenders often present the lowest possible EMI upfront. That number is calculated using the longest available tenure. A shorter tenure would mean a higher monthly payment, but far less total interest.
Borrowers anchor on the small number because it fits their monthly budget. They skip the step of multiplying that EMI by the number of months. When you do the math, the gap between principal borrowed and total repaid can be surprising.
This anchoring bias is not a sign of carelessness. It is a natural response to seeing a comfortable figure. The fix is simple: always ask for the total repayment amount before you agree.
The biggest error is never looking beyond the monthly number. If you borrow Rs 50,000 at a given interest rate, a 6 month tenure and an 18 month tenure produce very different totals. The longer option costs more in interest even though each instalment is smaller.
Fix: Before signing, multiply the EMI by the number of months. Compare that total against the principal. mPokket's personal loan EMI calculator can help you see both figures side by side.
Many borrowers pick the longest tenure because the app or lender suggests it. Longer tenure is not always better. It stretches your obligation and increases interest outflow.
Fix: Start with the shortest tenure you can afford. If the EMI strains your budget, increase tenure one step at a time. Stop at the point where the monthly payment is manageable without pushing total cost too high.
A personal loan EMI calculator shows you exactly how principal, interest, and tenure interact. Skipping this step means you are guessing. Guessing with borrowed money is risky.
Fix: Use an EMI calculator every time. mPokket offers this tool so borrowers can experiment with different amounts and tenures before applying. Plug in your loan amount, interest rate, and preferred tenure to see the monthly instalment and total repayment.
A Rs 2,000 EMI is easy to pay this month. But will it still be comfortable in month 10 or month 15? Borrowers rarely project their expenses forward. Unexpected costs like medical bills, home repairs, or festival spending can squeeze a budget that looked fine at the start.
Fix: Map your EMI against your monthly budget for the entire tenure. Account for irregular expenses. If the EMI leaves no room for emergencies, consider borrowing less or choosing a shorter tenure with a slightly higher payment.
When evaluating two loan offers, many borrowers pick the one with the lower EMI. That offer might have a longer tenure, a higher interest rate, or both. The "cheaper" monthly payment can end up being the more expensive loan overall.
Fix: Compare loans on three dimensions: interest rate, tenure, and total repayment. A transparent lender like mPokket shows all three clearly. If an offer only highlights the EMI, treat that as a reason to dig deeper, not a reason to sign.
A personal loan EMI calculator uses a standard formula. It takes the principal amount, the annual interest rate, and the tenure in months. The output is your fixed monthly instalment and the total interest payable.
Here is a practical approach. Enter your desired loan amount into the calculator. Try three different tenures: short, medium, and long. Note how the EMI changes and, more importantly, how the total repayment changes. The difference between the shortest and longest tenure is the real cost of choosing comfort over speed.
mPokket's EMI calculator is designed to make this comparison quick. Borrowers across segments, whether salaried employees, self employed professionals, or first time borrowers, can use it to make informed decisions before applying.
Choosing a loan based only on a small EMI is like buying a product based only on the instalment plan without checking the final price. The monthly number is just one piece of the picture. Total repayment, tenure length, and how the EMI fits your budget over time are equally important.
mPokket is designed to support transparent borrowing decisions. The platform provides EMI calculators, clear tenure options, and upfront cost breakdowns so borrowers can see the full picture. Whether you are a fresher managing your first salary, a housewife funding a home venture, or a salaried professional covering an emergency, the principle is the same: calculate before you commit.
Next time a low EMI catches your eye, pause. Open an EMI calculator. Compare tenures. Check the total. That five minute step can save you from months of regret.
Enter your loan amount, interest rate, and tenure into a personal loan EMI calculator. The tool computes your fixed monthly instalment and total interest payable. mPokket offers an EMI calculator that lets you compare different tenure options before applying.
A personal loan EMI calculator is an online tool that shows your monthly instalment based on principal, interest rate, and tenure. It also displays total repayment so you can assess the full cost of borrowing, not just the monthly figure.
No. A longer tenure lowers your monthly EMI but increases the total interest you pay. The overall cost of the loan rises because interest accrues over more months. Always compare total repayment across tenures before deciding.
A low EMI can mask a longer tenure or higher interest rate. Comparing loans only by monthly payment ignores total repayment cost. Check interest rate, tenure, and total amount payable to find the genuinely affordable option.
A responsible borrowing framework for instant personal loans in India
3 mins min read • 22 September 2026
Personal Loan Maximum Tenure: Is a Longer Repayment Period Right for You?
3 min read • 24 August 2026
How to Choose the Right Urgent Personal Loan During Financial Emergencies
4 min read • 10 August 2026
