Instant Unsecured Business Loan Without Collateral
Running a small business often means money needs to show up before the money coming in does. With mPokket’s instant unsecured business loan, you can apply for funding of up to ₹2 lakh without pledging your shop, machinery, stock or any other asset as security. It’s built for eligible small business owners, MSMEs and entrepreneurs who want a business loan without collateral and would rather not sit through branch visits and paperwork piles. Register on the app, complete your KYC, upload your business details and submit your request, all from your phone. Approval is eligibility-based, so the final offer depends on your business profile, income and repayment capacity. Check your eligibility today.
- Loans up to ₹2,00,000
- Digital KYC & Verification
- Minimal Documentation
- No Strict CIBIL Cutoof
 Loans up to ₹2,00,000
 Digital KYC & Verification
 Minimal Documentation
 No Strict CIBIL Cutoof
What Is an Unsecured Business Loan?
₹2L
Max Amount
100%
Digital
Fast
Approval
What Are the Benefits of an Unsecured Business Loan?
No need to pledge property or business assets
You don’t have to put your shop, land, machinery or stock on the line to apply. That makes an unsecured business loans for startup easier to consider if most of your capital is already tied up in the business.
Preserve ownership of business assets
Because nothing is pledged, you keep full ownership and control of your assets throughout the loan. Your equipment stays in your workshop and your shop stays yours, as long as you repay on time.
Secure funding for any business expenses
The money can be used for everyday business expenses, such as restocking, paying suppliers, rent or minor repairs. You decide where the money is needed most, within the eligible purposes allowed under the lending terms.

Quick Digital application
Everything happens in the app. You register, complete KYC, upload documents and submit your request without visiting a branch or standing in a queue. It saves time you’d rather spend running the business.

Repay through comfortable monthly instalments
Repayment is split into fixed monthly instalments, so you know what’s due each month and can plan your cash flow around it. Choose a tenure that suits your income cycle.
No Rigid CIBIL Cutoffs at mPokket
If the traditional lenders are rejecting your business loan requests due to lack of long credit history or high CIBIL score, mPokket is a good place to start. We only assess your income potential.
When Should a Business Consider an Unsecured Business Loan Without Collateral?
Not all businesses own property or heavy equipment to pledge and not all expenses can wait for the next sale. A loan without collateral can plug the holes. It is best suited for focused, short-term needs rather than large projects, with a funding of upto ₹2 lakh. Here are some situations where it can make sense.

Many home-based sellers, tailors and service providers rent their space and own little beyond tools. With nothing substantial to pledge, a collateral-free option like this can be a more realistic way to raise a modest amount.
A retailer running low before festival season could use ₹1–2 lakh to restock fast-moving items. Buying on time helps you avoid empty shelves and lost customers, and the monthly EMI can be planned against upcoming sales.
Suppliers often offer better terms for prompt payment, and some won’t ship until dues are cleared. A loan can help you settle an outstanding vendor bill so the relationship, and your supply line, stays intact.
Customers are sometimes slow to pay their bills, leaving you with a gap between bills due and cash available. A smaller top-up of up to Rs 2 lakh can fill that gap.
Replacing an old mixer, printer or billing machine can improve the speed and quality of work. An upgrade like this is good for a ₹2 lakh loan.
You can see annual license renewals, insurance premiums, or a seasonal marketing push coming. If your cash is committed elsewhere, a short-tenure loan can cover them, as long as repayments fit your monthly budget.
Who Can Apply for an Unsecured Business Loan?
If you run a registered enterprise or a small shop, mPokket’s unsecured business loan is tailored for operational businesses with a steady income. Here's how different types of borrowers can use it, if they qualify.
Unsecured Business Loans for Small Business Owners:
Retailers, shopkeepers, traders, service providers and other small operators can apply for a business loan without collateral if their business is active and they meet the eligibility criteria. Whether you run a kirana store, a salon or a trading counter, the application stays simple and mostly paperless.
Unsecured Business Loans for Startups
This option suits startups that are already up and running, with an established business history and income you can show. Pre-launch ideas or newly incorporated businesses with no trading record don’t automatically qualify. Lenders want proof that the business earns and can repay.
Unsecured Business Loan for MSME:
Micro, small and medium enterprises often need money for regular business requirements like buying raw material, paying wages or clearing vendor bills. MSME owners who are eligible and operational can avail of an unsecured business loan for MSME for their business needs.MSME applicants must have Udyam registration to apply for mPokket.
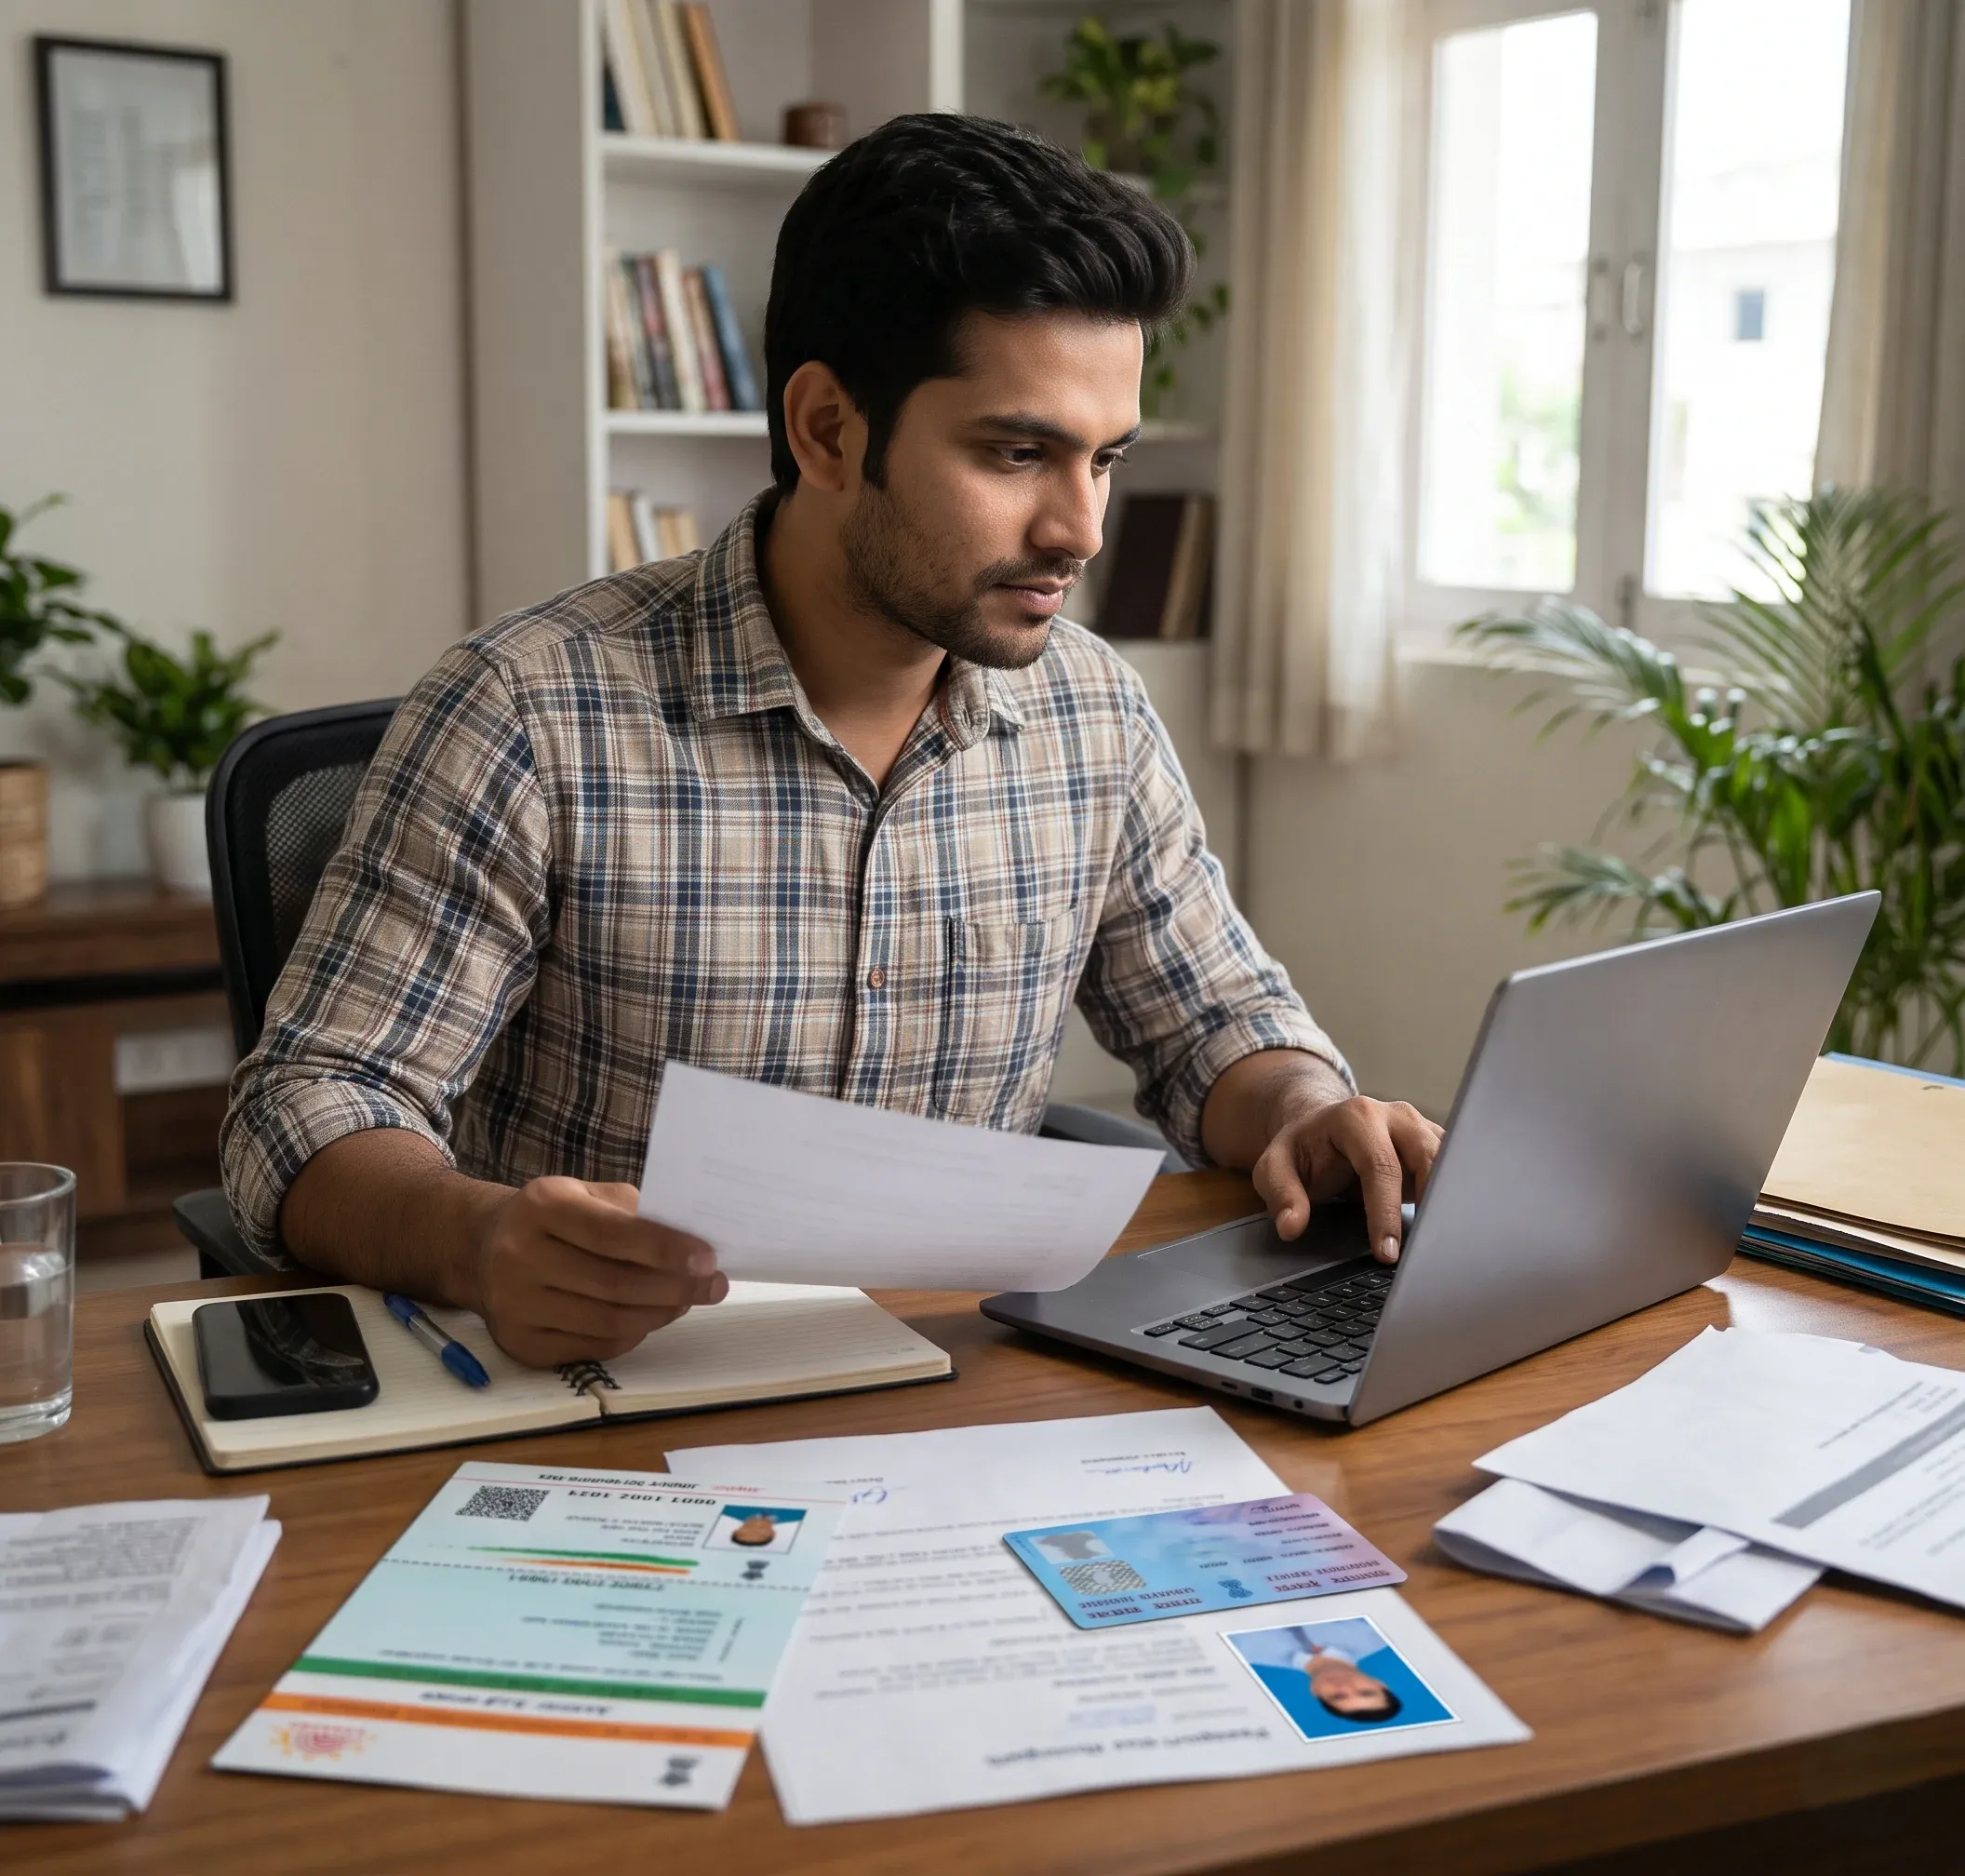
Eligibility is how a lender checks whether a loan fits your business and your budget. The points below are the common checks for an unsecured business loan for MSMEs or startups at mPokket.
Are You an Indian Citizen Aged 18 Years or Above?
You must be an Indian citizen and at least 18 years old to apply. Your identity and age are verified through your KYC documents during the application.
Existing and operational business
The business should already be running and earning. mPokket looks for an active setup, rather than an idea or a venture that hasn’t started trading.
Minimum business vintage
Your business needs to have been operating for a minimum period, as defined by mPokket’s lending policy. A longer track record strengthens the loan application.
Regular business income
The presence of a steady inflow of income in sales receipts, service payments, or daily collections helps you get approval for a higher loan amount.
Bank transaction
Your bank statements will show you the flow of money in and out of the business. Regular deposits or healthy balances increase approval chances.
Credit score and payment history
On-time payment and a clean financial record can help you unlock a lower interest rate. Missed payments can negatively impact your loan offer.
Monthly repayment capacity
After business and personal expenses, you should have enough left over to pay the EMI comfortably. The lender checks this to avoid putting you under financial strain with an instalment that’s too heavy.
Existing loan obligations
Running EMIs and credit card dues are taken into account. A high existing debt burden can lower the amount you’re offered, so it helps to clear smaller dues before you apply.
Business registration and verification
Your business details, address and registration are verified as part of the process. MSMEs must hold a valid Udyam registration, and the information you enter should match your submitted documents exactly.
What Is the Difference Between a Secured Business Loan and an Unsecured Business Loan?
Secured loans weigh the value and ownership of your asset alongside income. Unsecured loans depend more on credit history, business income, bank activity and ability to repay, so your financial record is more important.
Secured loans often cost less because the asset reduces the lender’s risk. Unsecured business loans interest rates can be higher, since pricing reflects borrower risk and lender policy. Final rates follow your offer.
Secured loans require proof of ownership and valuation reports of assets along with KYC documentation. Unsecured loans focus on KYC, business proof, income records and bank statements, which usually makes the paperwork lighter.
Secured loan amounts are usually tied to the value of the pledged asset. The unsecured amounts will depend on your eligibility and lender policy. At mPokket, you can apply for up to ₹2 lakh, subject to approval.
Secured loans have longer tenures for higher amount, unsecured loans usually have shorter tenure.Either way you pay back with monthly EMIs and are responsible for every installment.
How Do You Calculate Unsecured Business Loans Interest Rates, EMI, and Charges?
Your unsecured business loan interest rate depends on factors like credit profile, business income and repayment history. Together with the loan amount and tenure, it sets your EMI, which is the monthly installment calculated on the principal and interest. After that, processing fees and other charges will be added in the total interest payable and total repayment amount. Slide the loan amount bar to the amount you’re considering, then set the tenure in months and the interest rate. Thus, you can see an approximate monthly EMI, total interest and total repayment and compare plans before you apply.
Which Documents Are Required for an Unsecured Business Loan?
The exact documents depend on your borrower profile and lender requirements, so the app may ask for more or fewer. Keep these ready before you start.
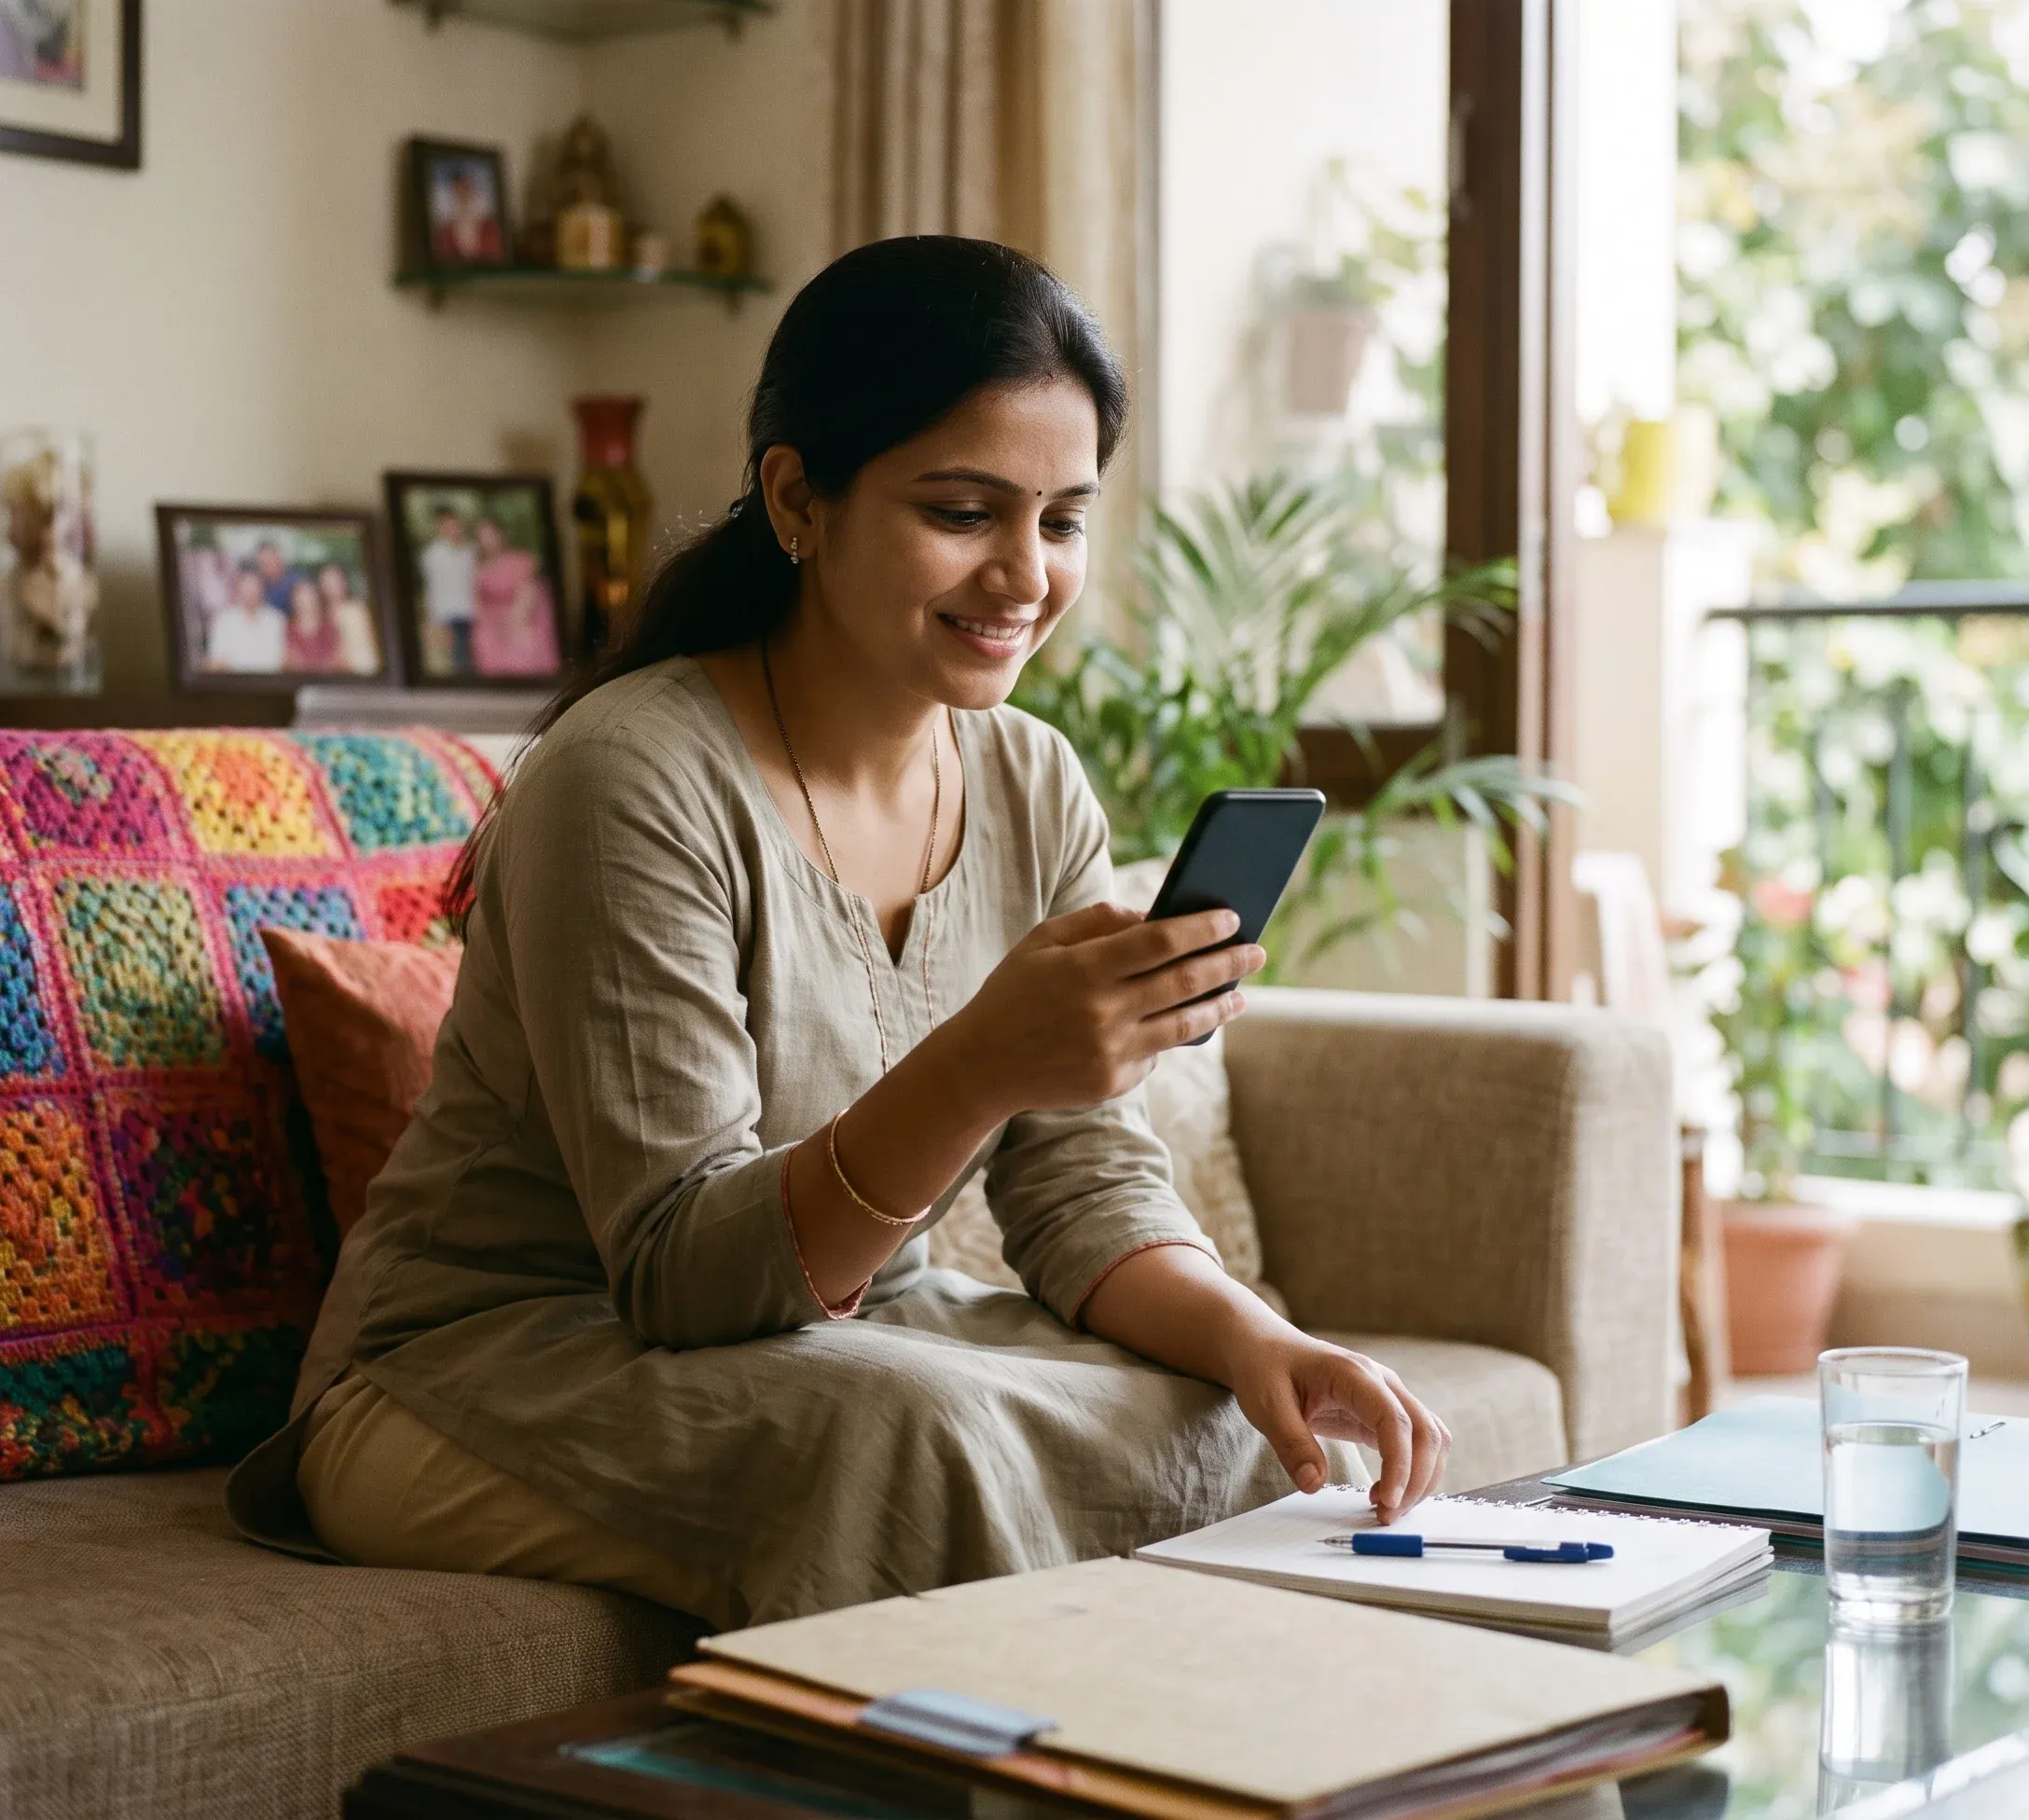
PAN and Aadhaar
These are required to verify your identity and complete KYC, and they let mPokket confirm that your details match official records.
Udyam registration (mandatory for MSMEs)
This registration officially confirms your enterprise’s existence and classification.
Business registration or establishment proof
You can submit any business-related documents, like trade licence or Udyam registration, that confirm your business exists and operates.
Bank statements
Bank statements are requested because they show your cash inflow, outflow and repayment habits.
Income or sales records
These records help the lender judge whether your earnings can support monthly EMIs.
GST registration or returns
It helps verify your turnover and confirm tax compliance.
Business address proof
You can submit a shop rental agreement, lease paper, property document, electricity bill or establishment certificate, whichever matches your premises.
Documents Ready? Start Application
Apply NowHow to Apply for an Unsecured Business Loan Online?
Applying for an unsecured business loan online shouldn’t eat up your afternoon. The mPokket app keeps the process simple and fully digital, from sign-up to disbursal. Follow the steps below, keep your documents handy, and you can submit your request with ease.
- 01
Register Yourself
Create your profile by entering your personal and business details.
- 02
Upload the Required Documents
Complete KYC with PAN, Aadhaar and a selfie. Add your income documents too.
- 03
Check Business Loan Eligibility
Complete verification and review the loan offer.
- 04
Submit Loan Application
Select your loan amount, tenure and EMI plan.
- 05
Accept the Applicable Terms
Accept the terms for approval and disbursal.
Frequently Asked Questions
Yes, if you’re eligible. mPokket doesn’t ask you to pledge property, stock or machinery. It reviews your business profile, income and credit record instead. Approval isn’t guaranteed, so the final decision rests on mPokket’s assessment.
The rate isn’t one fixed number. It varies with your credit profile, business income, loan amount and tenure. You’ll see the exact rate and charges in your applicable offer before you accept, so you can compare.
Yes, eligible micro, small and medium enterprises can apply. The business should be operational, and a valid Udyam registration is mandatory at mPokket. Other checks, such as income and repayment capacity, also apply.
Operational startups with an established business history and demonstrable income may qualify. Businesses that haven’t launched yet, or were only recently incorporated, don’t automatically qualify. Eligibility is reviewed case by case against mPokket’s lending policies.
Start with a simple formula: planned business expenses + outstanding business payments − available business funds = approximate financing requirement. For example, ₹1.5 lakh planned spend + ₹40,000 pending dues − ₹30,000 in hand ≈ ₹1.6 lakh. Before settling on a figure, check what EMI your monthly cash flow can comfortably handle. The final sanctioned amount may differ from your estimate.