Instant Business Loan for Women Entrepreneurs
Cash flow gaps can hold back even a good business. That’s where the instant business loan for women from mPokket comes in. It’s meant for eligible women entrepreneurs, small business owners and women-led MSMEs who need money for daily operations, stock, new equipment or growth. You can borrow up to ₹2 lakh, with no collateral to pledge. Everything happens on your phone, so there’s no branch queue to stand in.
- Loans up to ₹2,00,000
- Digital KYC & Verification
- Minimal Documentation
- No Collateral Required
 Loans up to ₹2,00,000
 Digital KYC & Verification
 Minimal Documentation
 No Collateral Required
What Is a Business Loan for Women Entrepreneurs?
₹2L
Max Amount
100%
Digital
Fast
Approval
What Are the Benefits of a Business Loan for Women?
Access funds for eligible business requirements
Stock, repairs, rent, supplier bills. Whatever the genuine business need is, the money is there when you need it. Small business loans for women let you move on an opportunity instead of waiting for customers to pay.
Avoid pledging business or personal assets as collateral
This is an unsecured business loan, so your shop, home, gold or any other asset stays with you. Nothing has to be pledged. You can focus on growing the business without putting property at risk.
Preserve available savings for operational expenses
Why drain household savings for business needs? Loan funds can cover those costs, while your own money stays available for rent, salaries, electricity bills and other regular running expenses.

Purchase inventory or essential business equipment
Restock products, buy raw materials or pick up a sewing machine, mixer or display unit. Buying on time means you can finish orders when they come in, and customers have a reason to return.

Manage short-term business cash flow requirements
Sales don’t always show up on schedule. A short-term business loan for women covers the gap between what you spend and what you’re yet to receive, so work carries on through slow weeks or late payments.
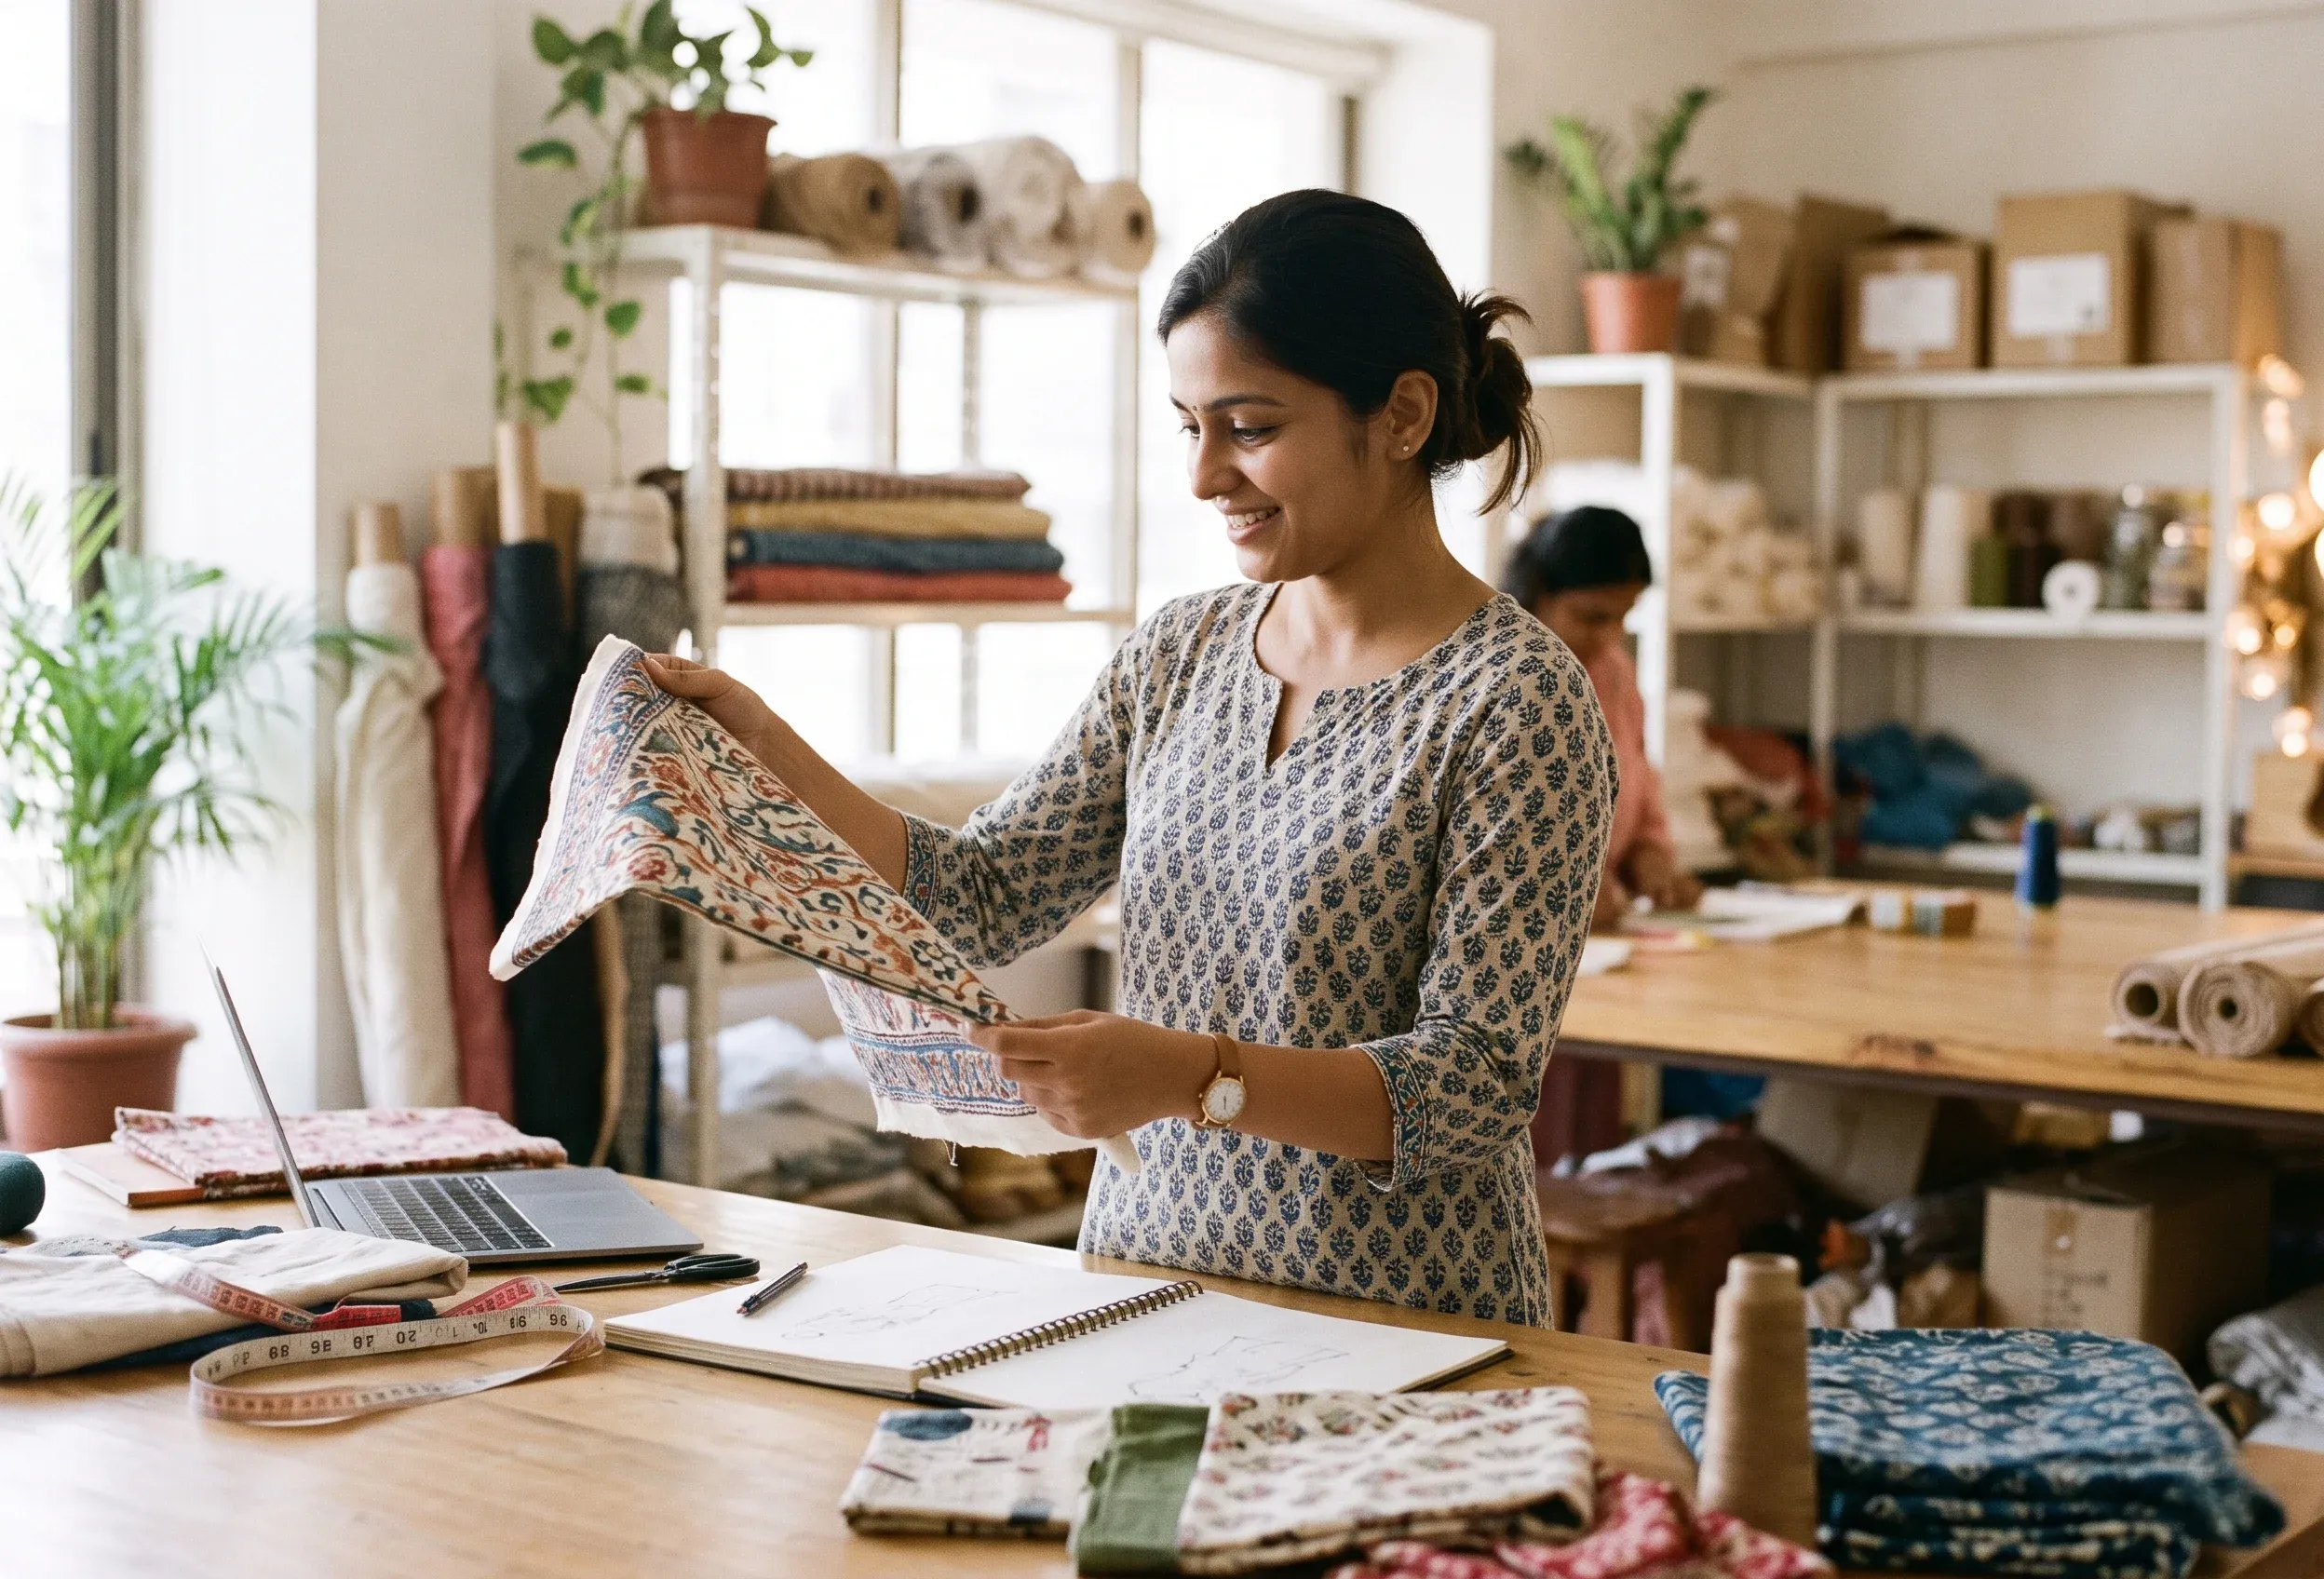
Apply through a digital process
Apply from your smartphone on the mPokket app. Set up your profile, finish KYC, upload documents and pick your loan details online. No branch trips, no stacks of paperwork to carry around.
Repay through structured monthly instalments
You repay in fixed monthly instalments (EMIs) based on the amount and tenure you choose. Since you know the EMI upfront, planning your monthly budget and business cash flow gets a lot easier.
When Should You Consider a Business Loan for Women?
A business loan for women works best when the money has a clear business purpose and the EMIs fit comfortably into your budget. These are some situations where women entrepreneurs often think about borrowing.

Shelves run low just before a busy week, and there’s no cash to refill them. A kirana store owner, for instance, can restock fast-moving items and avoid losing sales.
A festive season or one viral post can bring a flood of orders. With extra funds, you can buy more material, bring in short-term help and deliver on time rather than turning people away.
Worn-out tools slow down work and hurt quality. A salon owner might replace a damaged chair or hair dryer, and a tailor might finally swap an old sewing machine for a better one.
Suppliers want payment on fixed dates, but your customers may pay late. Clearing dues on time protects the relationship, and sometimes gets you better terms on future orders.
Home bakers, tiffin providers and craft sellers often outgrow their setup. Extra funds can cover packaging, a second oven, storage or delivery, so taking on more orders feels less risky.
Thinking of adding a product line, a new service or an online sales channel? A loan can pay for first stock, basic marketing and setup while you see what your customers respond to.
What Are the Different Types of Business Loan for Women?
Funding needs change with the kind of business you run and how far along it is. Someone with years of steady sales needs something different from a person who started recently. Here are the main types of business loan for women to consider.
MSME Loan for Women:
An MSME loan for women is for eligible women-owned micro, small and medium enterprises that need money for operating costs, inventory, equipment and growth. If your business has regular activity, this kind of financing can help with running costs and planned next steps. Udyam registration, where applicable, helps with verification.
Small Business Loans for Women:
Small business loans for women suit those running everyday businesses with modest funding needs. Retail and kirana stores, beauty parlours, boutiques and tailoring units, home-based food businesses, online stores: all of them can look at financing of up to ₹2 lakh.
Startup Loan for Women:
A startup loan for women can help owners of recently established businesses pay for equipment, inventory, marketing or operating costs. Whether you qualify depends on business vintage, current operations, proof of income and lender policy. It isn’t guaranteed funding for a business that hasn’t launched yet.
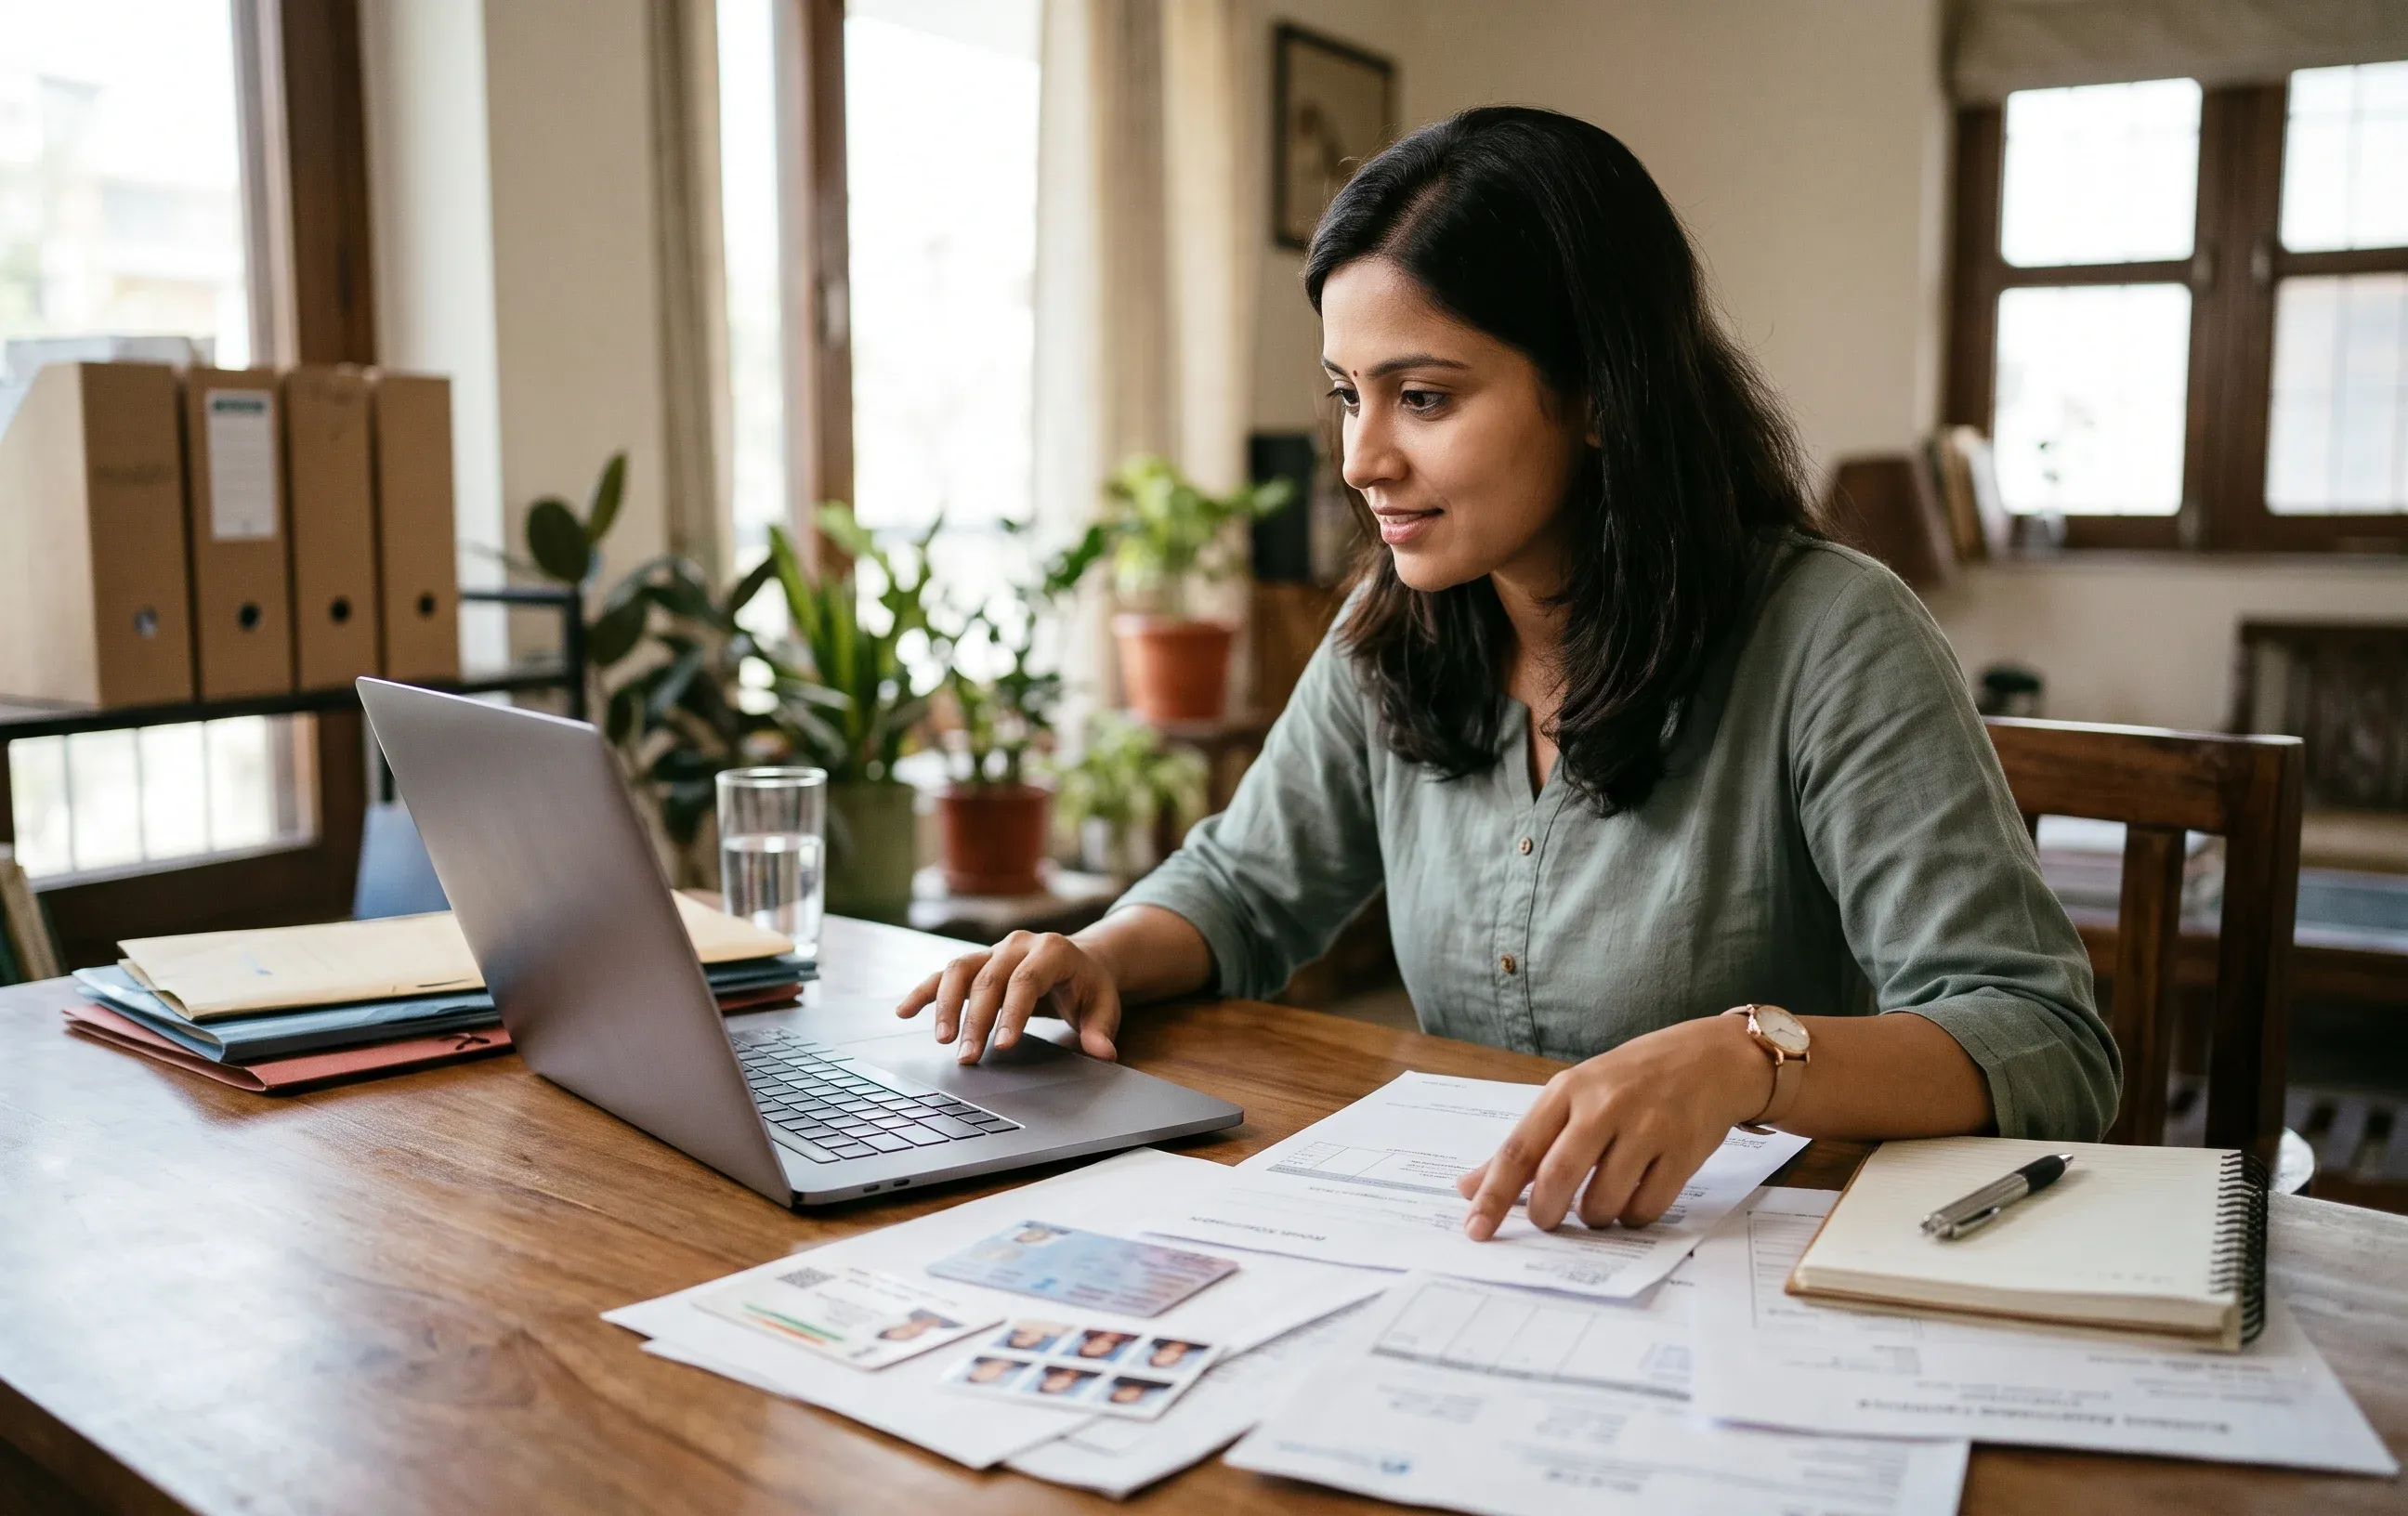
Eligibility for a women entrepreneurs loan comes down to your business and financial profile, not gender alone. Lenders want to know the business is active and that repayment won’t strain you. Here’s what they usually check.
Applicant age and nationality
You need to be an Indian citizen and fall within the age range the lender sets.
Active and operational business
The business must be running right now, not closed or dormant.
Business ownership or involvement
You should either own the business or be actively involved in running it.
Minimum business vintage
The business needs to have operated for at least the minimum period required.
Regular business income
Steady sales or earnings show you can handle repayments.
Bank transaction history
Account activity gives the lender a picture of your cash flow.
Credit profile and repayment history
A clean record of repaying earlier dues works in your favour.
Existing financial obligations
Existing EMIs and dues are looked at alongside the new loan.
Monthly repayment capacity
After your other expenses, your income should comfortably cover the new EMI.
What Is the Difference Between a Business Loan for Women and a Personal Loan for Women?
Business loans are for women who run a business. Personal loans are for women who need money for personal reasons, whether they’re salaried or self-employed.
For a business loan, lenders look at business activity, income and vintage. For a personal loan, the focus shifts to personal income, employment details and credit profile. Lender assessment applies to both.
Business loans usually ask for proof of the business, like registration, sales records or bank statements. Personal loans lean on personal income papers such as salary slips, plus identity proof.
Business loan money goes into inventory, operations and equipment. Personal loan money can cover eligible personal expenses, say a family event, a medical bill or a home repair.
Business loan repayment is planned around business income and cash flow, while personal loan repayment depends on personal income. In both, the EMI comes down to amount, tenure and applicable terms.
How Do You Calculate EMIs of the Business Loan for Women?
Before you apply for a business loan for women, check the applicable unsecured business loan interest rate. Credit profile, income and repayment history all affect it. Your EMI then depends on the loan amount, repayment tenure, and any processing fees and other charges. The calculator below shows your EMI, total interest payable and total repayment amount.
Which Documents Are Required for a Business Loan for Women?
Documents let the lender confirm who you are, that your business exists and what it earns. Requirements vary by business and assessment, so the app may ask for alternates. Keep these ready for your business loan for women application.
PAN and Aadhaar
These verify your identity and complete KYC, though other officially valid ID may be accepted under lender policy.
Business registration or establishment proof
This shows your business actually exists. If you don’t have formal registration, a shop licence or similar proof may do.
Bank account details and statements
If required, statements show your transaction history and cash flow, which helps the lender judge how comfortably you can repay.
Income or sales records
Sales registers or payment-app summaries prove regular earnings, and bank statements can fill in where formal records are missing.
GST registration or returns
If you’re GST-registered, returns confirm your turnover. Smaller businesses can use other income proof instead.
Udyam registration for eligible MSMEs
Udyam registration validates your business as an MSME and supports an MSME loan for women. If you don’t have it, other business proof may be accepted.
Business address proof
A rent agreement or utility bill confirms where you work, and home-based owners can share residence proof.
Business invoices or payment receipts
These show real transactions with customers or suppliers, and can stand in when formal records aren’t maintained.
Documents Ready? Start Application
Apply NowHow to Apply for a Business Loan for Women Online?
Applying for a business loan for women through the mPokket app is entirely online, so there’s no branch visit. Keep your phone and documents close, and go through the steps at your own pace. You’ll see your loan details before you accept anything.
- 01
Register Yourself
Download the app and set up your profile with your personal and business details.
- 02
Upload the Required Documents
Complete KYC using PAN, Aadhaar and a selfie, then add your income documents.
- 03
Check Business Loan Eligibility
Finish verification and go through the loan offer that appears for your profile.
- 04
Submit Loan Application
Pick your loan amount, tenure and EMI plan, then submit.
- 05
Accept the Terms
Accept the applicable terms to move ahead with approval and disbursal.
Frequently Asked Questions
Yes. mPokket’s unsecured business loans don’t need collateral. An MSME loan for women is approved on eligibility, business profile and repayment capacity, with amounts up to ₹2 lakh.
Yes. Women who run shops, salons, online stores or home-based services can apply for small business loans for women, provided they meet the criteria, including active operations and regular income.
A startup loan for women is for businesses that have already begun operating. Eligibility depends on business vintage, income evidence and lender policy, so funding for a business that hasn’t launched isn’t guaranteed.
Typically PAN, Aadhaar, a KYC selfie, business proof and income records. Depending on your business, bank statements, GST returns, Udyam registration and address proof may also be needed. Requirements for a women entrepreneurs loan vary by profile.
Try this: planned business expenses, plus upcoming operational payments, minus available business funds, gives your approximate loan requirement. Also weigh expected business income, recurring expenses, existing loan repayments and whether you can manage additional EMIs. The approved amount may differ based on eligibility and lender assessment.