4 mins min read • 17 November 2026


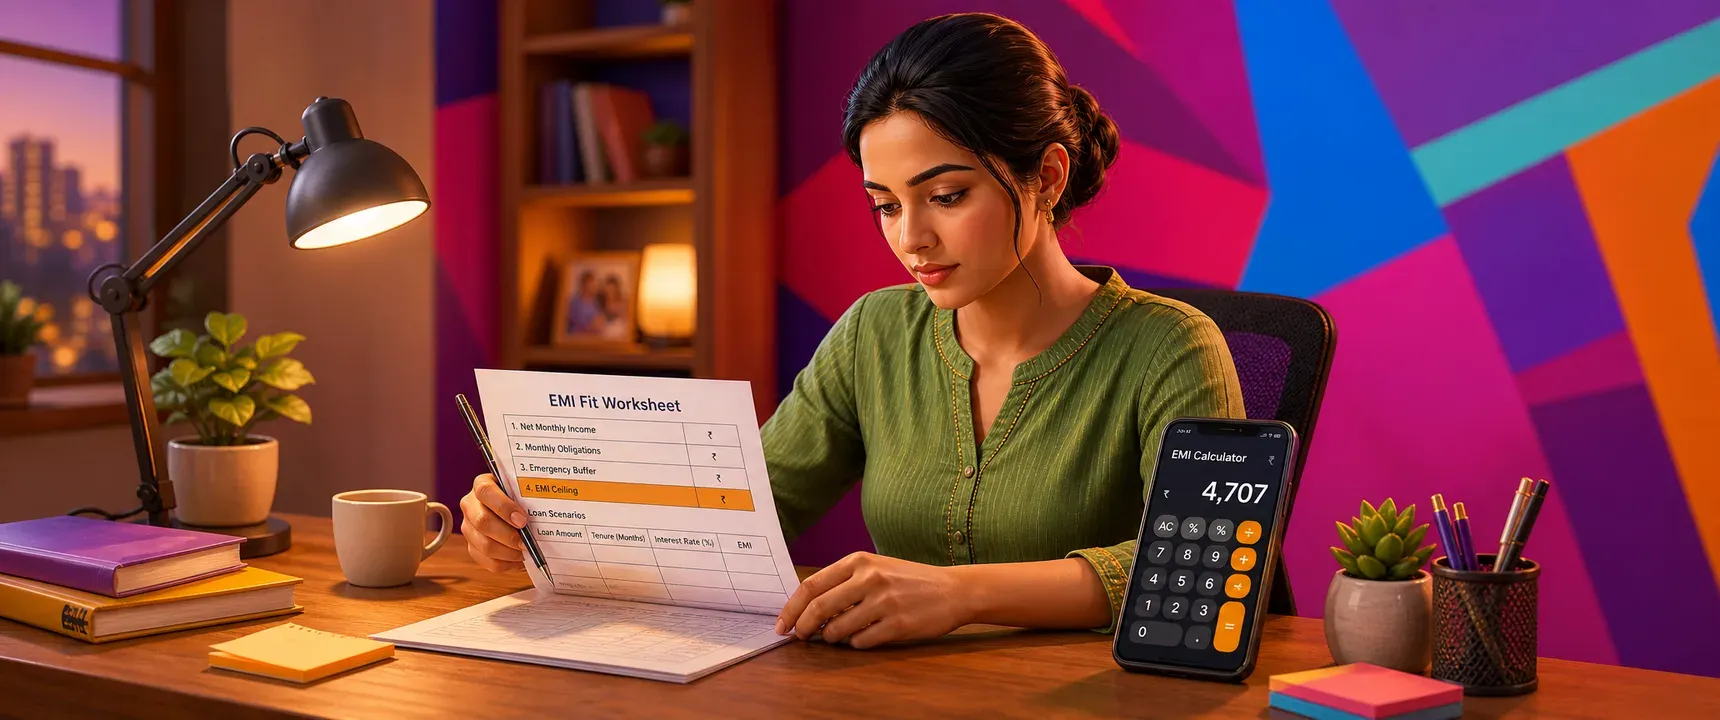
Table of content
EMI fit worksheet for Indian borrowers choosing loan amount and tenure
Summary
Why borrowers skip repayment planning
How a personal loan EMI calculator works
The mPokket EMI fit worksheet
Decision matrix: scoring your fit
How tenure and amount change your EMI
Common mistakes to avoid
Putting the worksheet into action
FAQs
Most Indian borrowers know how much money they need. Few know how much they can comfortably repay each month. That gap between wanting a loan and affording one is where costly mistakes happen. mPokket believes every borrower deserves a simple, structured way to test repayment comfort before submitting an application. This EMI fit worksheet turns that belief into a practical self assessment you can complete in minutes.
Follow our Whatsapp Community for more offers and updates.
Join nowWhat is an EMI fit worksheet? - It is a structured self assessment that helps you decide loan amount, tenure, and monthly EMI before you apply. Instead of guessing, you score your income, obligations, and emergency buffer against clear thresholds to find a repayment zone that fits your life.
How do you calculate personal loan EMI online? - Use a personal loan EMI calculator (like the one mPokket offers) by entering loan amount, interest rate, and tenure in months. The tool applies the standard reducing balance formula and shows your estimated monthly instalment instantly.
Why does repayment comfort matter? - A low EMI to income ratio (ideally under 40% of net monthly income across all obligations) protects you from missed payments, penalty charges, and credit score damage. Comfortable EMIs also leave room for emergencies and savings.
Who benefits most from this worksheet? - First time borrowers, salaried employees, freshers, self employed professionals, and anyone without prior credit experience. The worksheet is designed to replace guesswork with a repeatable decision framework aligned with mPokket's transparent lending approach.
Loan applications in India focus on eligibility. Lenders ask whether you qualify. Borrowers ask whether they will get approved. Neither side pauses long enough on a different question: can you repay this amount every month without stress?
Online EMI calculators solve part of the problem. They show you the monthly number. But a number without context is just arithmetic. Knowing your EMI is Rs 3,200 per month means nothing until you compare it against your rent, groceries, existing obligations, and the emergency buffer you need.
mPokket's EMI fit worksheet bridges that gap. It connects calculator output to your actual financial situation so you can make a confident, responsible borrowing decision.
A personal loan EMI calculator uses the standard reducing balance formula. You enter three inputs: loan amount (principal), annual interest rate, and tenure in months. The calculator returns your equated monthly instalment.
For example, a Rs 50,000 loan at 24% annual interest for 12 months produces an EMI of approximately Rs 4,707. Extend the tenure to 18 months and the EMI drops to roughly Rs 3,378, but total interest paid rises.
mPokket's calculator is designed to let borrowers experiment with these variables quickly. Adjusting tenure or amount by even small increments reveals how sensitive your monthly payment is to each change. That sensitivity is the foundation of the worksheet below.
This worksheet is a five step self assessment. Complete each step honestly. The goal is not to maximize the loan amount you can get; it is to find the loan amount and tenure combination that leaves your monthly budget healthy.
Write down your total monthly take home pay after tax deductions. If you are self employed or a freelancer, use the average of your last six months of net deposits. Freshers should use their confirmed offer letter salary or stipend amount.
Add up every recurring monthly payment: rent, existing EMIs, insurance premiums, subscription services, and any regular family contributions. This total is your fixed outflow.
Reserve a portion of your remaining income for unplanned expenses. A reasonable starting point is 10% to 15% of net monthly income. If you have no emergency fund saved, lean toward 15%. This buffer protects you from missing an EMI when an unexpected bill arrives.
Subtract fixed outflow (Step 2) and emergency buffer (Step 3) from net monthly income (Step 1). The result is the maximum EMI you can handle without cutting into essentials. Financial discipline suggests keeping total EMI obligations (old plus new) below 40% of net income.
Use mPokket's personal loan EMI calculator to test different loan amount and tenure combinations. Pick the combination whose EMI sits comfortably below your ceiling from Step 4.
The table below turns the worksheet into a quick scoring framework. Rate yourself on each criterion, then read across to see whether your planned loan sits in a comfortable, cautious, or risky zone.
| Criterion | Comfortable (score 3) | Cautious (score 2) | Risky (score 1) |
|---|---|---|---|
| EMI as % of net income | Below 25% | 25% to 40% | Above 40% |
| Existing obligations ratio | Below 20% of income | 20% to 35% of income | Above 35% of income |
| Emergency buffer after EMI | 15% or more of income | 10% to 14% of income | Below 10% of income |
| Tenure relative to need | Shortest tenure you can afford | Mid range tenure | Maximum tenure to lower EMI |
| Income stability | Salaried with 6+ months tenure | Salaried under 6 months or steady freelance | Irregular or seasonal income |
Add your scores. A total of 12 to 15 signals strong repayment comfort. A total of 8 to 11 means you should consider reducing the loan amount or extending tenure slightly. Below 8, pause and reassess whether borrowing right now is the right move.
Tenure is the single biggest lever most borrowers overlook. Extending tenure lowers the monthly EMI but increases total interest. Shortening tenure raises the EMI but saves on interest cost.
Consider two scenarios for a Rs 1,00,000 loan at 24% annual interest. A 12 month tenure produces an EMI near Rs 9,414 and total interest of roughly Rs 12,968. An 18 month tenure drops the EMI to about Rs 6,756 but pushes total interest to approximately Rs 21,608.
Neither option is universally better. The right choice depends on your EMI ceiling from Step 4. If Rs 9,414 sits comfortably below your ceiling, the shorter tenure saves you money. If it pushes you into the risky zone, the longer tenure is the responsible pick.
Borrowers often inflate their repayment capacity by ignoring irregular expenses like annual insurance premiums or festival spending. Others forget to account for upcoming life changes such as a job switch or a planned relocation.
Another frequent error is treating the EMI calculator output as a guarantee. The calculator shows an estimate based on the inputs you provide. Actual interest rates depend on your credit profile, lender terms, and the loan product you choose. mPokket's transparent approach is designed to help borrowers see the full cost before committing.
Finally, some first time borrowers skip the worksheet entirely because they plan to borrow a small amount. Even a Rs 10,000 loan can strain a tight budget if the EMI lands on the same week as rent and utility bills. The worksheet works at every loan size.
Before you open any loan application, complete the five steps above. Write the numbers down. Run at least three scenarios in mPokket's personal loan EMI calculator: one at the amount you want, one 20% lower, and one with a longer tenure. Score each scenario using the decision matrix.
Pick the scenario that scores highest. That is your borrowing plan. It protects your monthly budget, keeps your credit profile healthy, and ensures your EMI never becomes a source of stress.
mPokket's calculator led, transparent lending model is designed to support exactly this kind of disciplined decision making. Responsible borrowing starts before the application, not after the disbursal.
Enter your loan amount, annual interest rate, and tenure in months into an online EMI calculator such as the one mPokket provides. The tool applies the reducing balance formula and displays your estimated monthly instalment instantly.
A personal loan EMI calculator is a digital tool that computes your equated monthly instalment based on principal, interest rate, and tenure. It helps you compare different loan scenarios before applying so you can choose a comfortable repayment plan.
Financial discipline suggests keeping total EMI obligations below 40% of your net monthly income. Staying below 25% is considered comfortable and leaves adequate room for savings, emergencies, and other monthly expenses.
Yes. A longer tenure lowers your monthly EMI but increases the total interest you pay over the loan's life. A shorter tenure raises the EMI but reduces overall interest cost. Use mPokket's EMI calculator to compare both scenarios before deciding.
Absolutely. The worksheet is especially useful for freshers, salaried employees new to credit, and self employed professionals. It replaces guesswork with a structured self assessment that aligns borrowing with actual repayment capacity.
A responsible borrowing framework for instant personal loans in India
3 mins min read • 22 September 2026
Best practices for first time borrowers using loan apps in India
5 min read • 11 September 2026
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
