3 mins min read • 23 October 2026


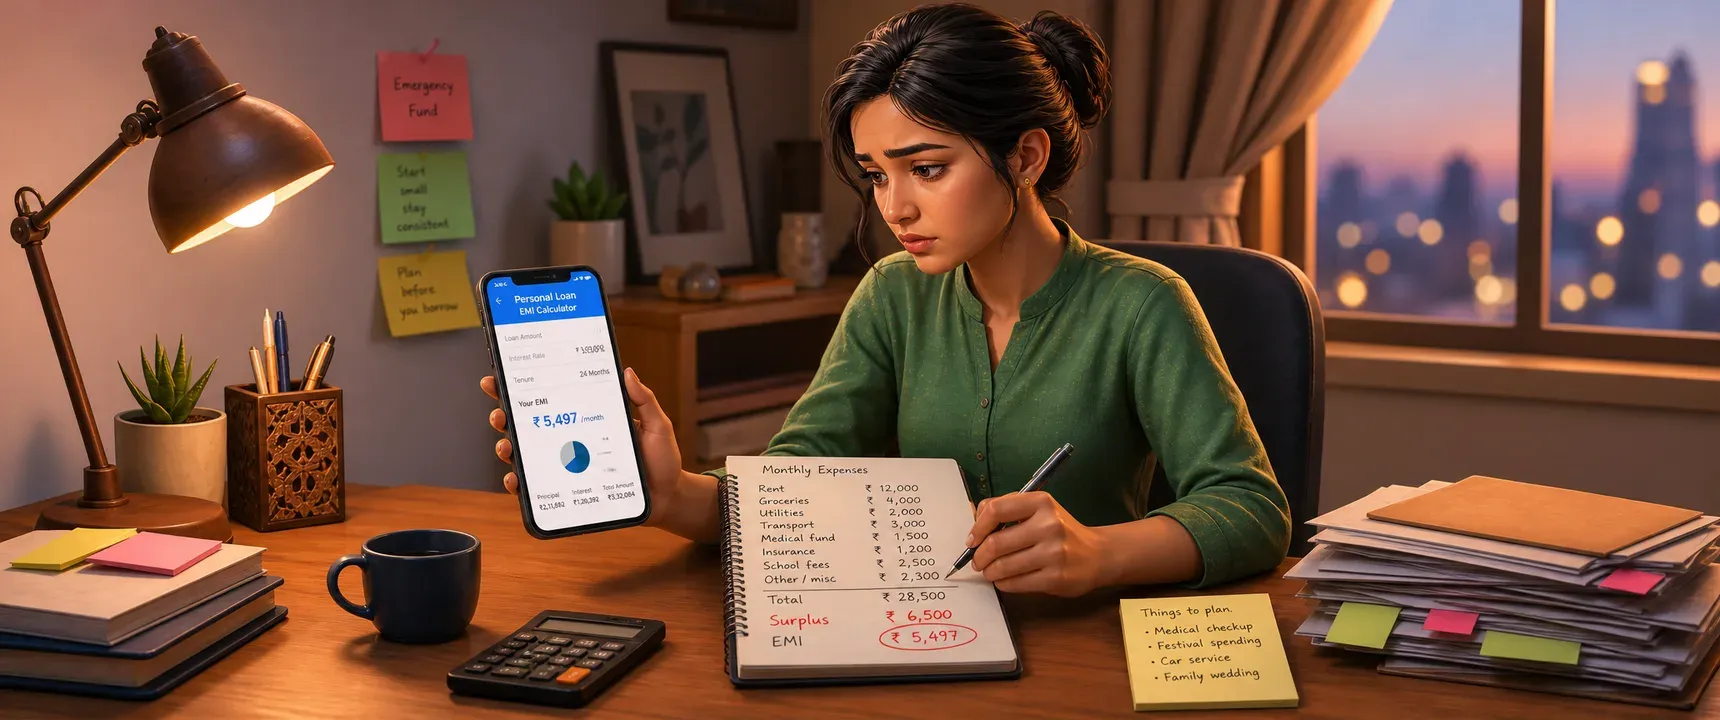
Table of content
Overview
Why calculators miss the full picture
Warning signs EMI may not fit
Who faces this gap most?
How to stress test before borrowing
What mPokket recommends
FAQs
You ran the numbers. The personal loan EMI calculator showed a figure that looked comfortable. You signed the loan agreement, and the funds landed in your account. Then real life started. Rent went up. A family wedding demanded contributions. Your freelance income dipped for two months. Suddenly that "affordable" EMI felt like a weight you had not planned for. mPokket sees this pattern often among Indian borrowers, and it points to a gap between calculator math and lived financial reality.
Follow our Whatsapp Community for more offers and updates.
Join nowA personal loan EMI calculator does one job well. It takes your loan amount, interest rate, and tenure, then returns a monthly instalment figure. That output is mathematically correct. It is also incomplete.
The calculator assumes your income stays constant. It assumes your expenses stay constant. It assumes no surprises arrive between month one and the final EMI. None of those assumptions hold for most Indian borrowers.
Consider a salaried employee earning Rs 35,000 per month. The calculator says an EMI of Rs 5,500 is affordable because it falls below the common 40 percent debt to income guideline. But that guideline ignores the Rs 12,000 rent, Rs 3,000 commute cost, Rs 4,000 in groceries, Rs 2,000 in utility bills, and the Rs 1,500 monthly contribution to a parent's medical fund. After these fixed outflows, the real surplus is closer to Rs 7,000. One unplanned expense, a dentist visit, a phone repair, a cousin's wedding gift, and the EMI suddenly competes with essentials.
Recognizing the symptoms early can help borrowers avoid repayment stress. Here are the most common warning signs that an EMI looks manageable on paper but will not work in practice.
Your surplus after fixed expenses is thin. If the gap between your monthly income and non negotiable outflows is less than 1.5 times the proposed EMI, any disruption will create a shortfall.
You have no emergency buffer. Without even one month of expenses saved, any sudden cost (medical bills, home repairs, job transition) forces a choice between the EMI and the emergency.
You are already servicing other debt. Existing credit card dues, another EMI, or informal borrowing from family reduces your true repayment capacity below what a standalone calculator suggests.
Seasonal or annual expenses are not budgeted. School fees in June, festival spending in October, insurance premiums in March. These lumpy costs do not appear in a monthly EMI calculation but compete for the same money.
Your tenure does not match your income horizon. A fresher on a six month internship stipend taking a 24 month EMI loan faces a structural mismatch. If the stipend ends and the next job pays differently, the EMI commitment remains unchanged.
You chose tenure based on lowest EMI, not total cost. Stretching tenure to reduce the monthly number feels easier, but it increases total interest paid and extends the period during which your budget stays constrained.
Certain borrower profiles are more exposed to the calculator versus reality gap. Understanding which group you belong to can help you prepare better before taking a loan.
Salaried employees on starting salaries often have tight budgets. A fresher earning Rs 18,000 to Rs 25,000 per month may qualify for a small personal loan, but rent, food, and transport already consume most of that income. Even a modest EMI can tip the balance.
Self employed professionals and freelancers face income volatility. A graphic designer might earn Rs 40,000 in one month and Rs 15,000 the next. The EMI calculator does not ask which month you are planning for. It assumes every month looks the same.
Housewives managing household finances often juggle unpredictable costs. Kids fall sick. Appliances break. School demands fees mid term. A small loan for a home based tiffin or stitching business can feel affordable until these household shocks arrive.
Gig workers, including delivery partners and cab drivers, earn on a per task basis. Weekly earnings fluctuate based on demand, weather, and platform incentives. A fixed monthly EMI does not align with this earning pattern.
The solution is not to avoid borrowing. It is to test the EMI against your actual life, not just your calculator screen. Here are practical steps any borrower can take.
First, map your real monthly outflows. Write down every recurring expense for the past three months, including the irregular ones. Add them up. Subtract from your lowest earning month, not your average. The remainder is your true repayment capacity.
Second, simulate the EMI for two months before borrowing. Set aside the proposed EMI amount in a separate account for 60 days. If you struggle to do this without cutting essentials, the EMI is too high for your current situation.
Third, factor in at least one surprise per quarter. Medical costs, vehicle repairs, and family obligations are not surprises in India. They are certainties with uncertain timing. Build a buffer of at least Rs 3,000 to Rs 5,000 above your EMI commitment.
Fourth, consider tenure carefully. A shorter tenure means higher monthly payments but less total interest. A longer tenure means lower monthly payments but more total cost and a longer period of budget constraint. Neither is universally better. The right tenure matches your income stability and expense pattern.
Fifth, explore flexible repayment options. mPokket offers flexible repayment structures that can help borrowers whose income does not arrive in neat monthly packages. Features like choosing your repayment mode and tenure selection can align your loan with your actual cash flow rather than forcing your cash flow to match a rigid schedule.
mPokket positions itself as a digital lending platform that goes beyond just disbursing funds. The platform encourages borrowers to understand repayment fit before committing. Tools like the personal loan EMI calculator on mPokket can help estimate monthly instalments, but mPokket also emphasizes that calculator output is a starting point, not a final answer.
For borrowers with irregular income, mPokket's flexible repayment loan options and tenure selection features are designed to reduce the mismatch between fixed EMI commitments and variable earning patterns. The platform's paperless, mobile first process also means borrowers can access loan management tools, repayment reminders, and autopay options that help prevent missed payments.
Responsible borrowing starts with honest self assessment. A calculator tells you what you can technically afford. Only you know what you can practically sustain.
Before your next loan decision, take the time to map your real expenses, test the EMI against your worst month, and choose a repayment structure that fits your life. mPokket is designed to support that kind of informed borrowing, whether you are a salaried professional, a freelancer, a gig worker, or a housewife managing a household budget.
Use a personal loan EMI calculator by entering your loan amount, interest rate, and tenure in months. The tool applies a standard formula to show your estimated monthly instalment. mPokket offers an EMI calculator on its platform to help borrowers estimate payments before applying.
A personal loan EMI calculator is a digital tool that computes your monthly instalment based on principal, interest rate, and loan tenure. It gives a quick estimate but does not account for your actual monthly expenses, irregular costs, or income fluctuations.
Calculators only consider loan variables like amount, rate, and tenure. They ignore rent, groceries, medical bills, family obligations, and income variability. When these real costs stack up, the EMI competes with essentials and feels heavier than the number suggested.
Set aside the proposed EMI amount for two months before borrowing. Track all your real expenses during that period. If you struggle to save the EMI amount without cutting necessities, the loan may not be a good fit at that amount or tenure.
Yes. mPokket is designed to offer flexible repayment options and tenure selection that can help borrowers with variable income align their loan payments with their actual cash flow patterns, rather than forcing a rigid monthly schedule.
Common emergency borrowing mistakes when a medical bill feels urgent
4 mins min read • 22 October 2026
Which app gives emergency loan instantly
4 mins min read • 22 October 2026
EMI for Furniture: Turn Your Dream Home into Reality Without Financial Stress
4 min read • 23 July 2026
What Are the Advantages of Using a Short-Term Loan for Emergencies?
3 min read • 2 June 2026