4 mins min read • 19 October 2026


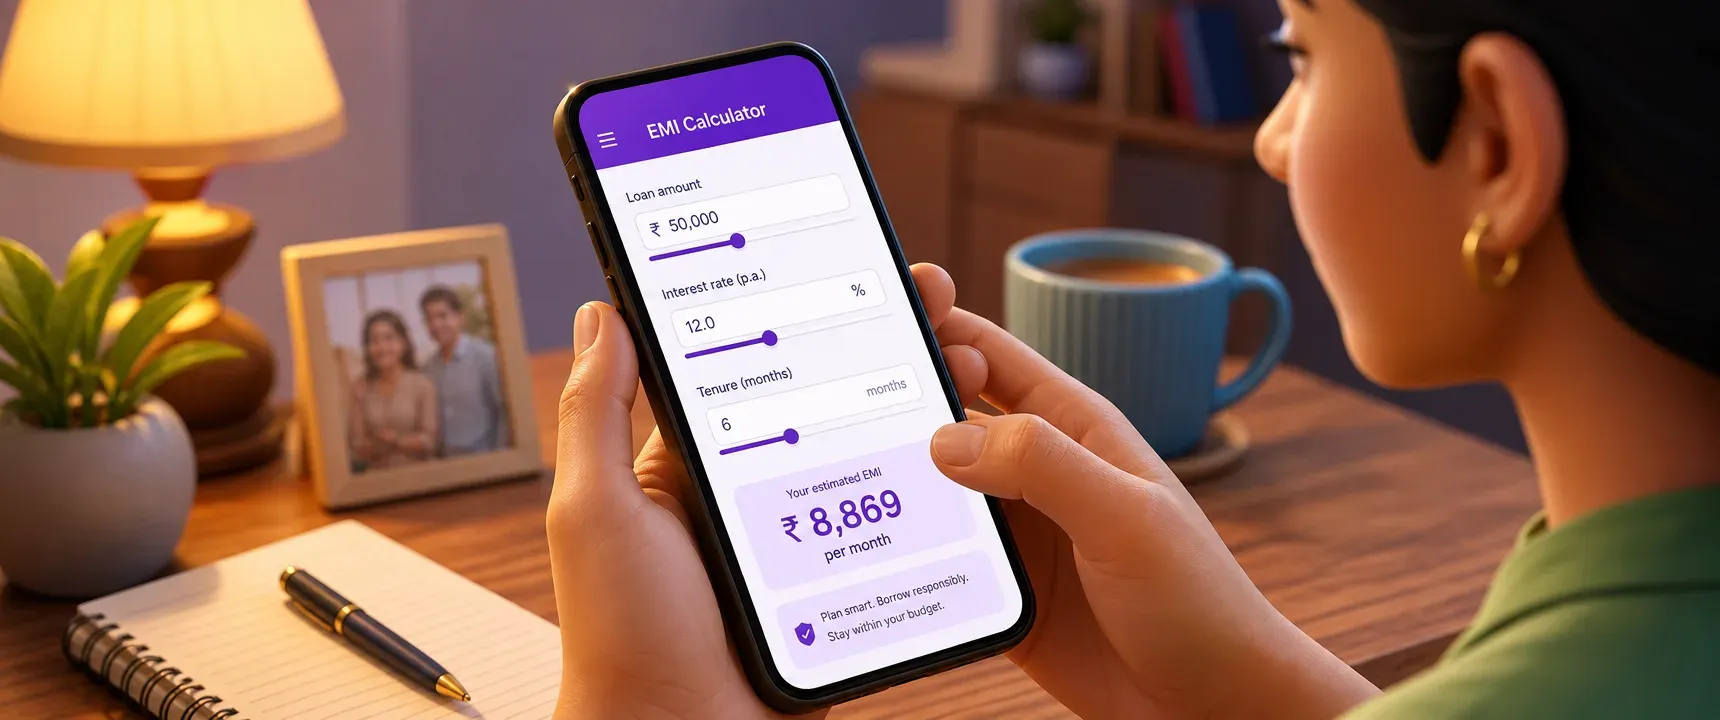
Table of content
Summary
What is a personal loan EMI calculator?
Why check EMI before an emergency loan?
How to use the calculator step by step
What inputs change your EMI most?
Avoiding common emergency borrowing mistakes
FAQs
What is a personal loan EMI calculator? - A personal loan EMI calculator is a digital tool that estimates your monthly instalment based on the loan amount, interest rate, and tenure you enter. It helps you see the exact repayment burden before you borrow, so you can decide whether the EMI fits your monthly budget.
Why use it before an emergency loan? - Emergencies push people to borrow fast without checking repayment fit. Running a quick EMI estimate on a tool like the one available on the mPokket app can reveal whether the monthly outflow will strain your budget or stay manageable alongside rent, groceries, and other fixed costs.
How do you adjust EMI to fit your budget? - You can change three inputs: loan amount, tenure, and interest rate. Borrowing only what you need, choosing a slightly longer tenure, or comparing rates across options can lower your EMI to a comfortable range, typically under 30% to 40% of your monthly income.
What steps should you follow? - Open the EMI calculator, enter the loan amount matching your emergency expense, select a realistic tenure, note the estimated EMI, compare it against your monthly income, and only then proceed with the loan application on a platform like mPokket.
Follow our Whatsapp Community for more offers and updates.
Join nowA personal loan EMI calculator is an online tool that computes your equated monthly instalment. You enter three numbers: the principal amount you want to borrow, the annual interest rate, and the repayment tenure in months. The calculator applies a standard formula and returns the fixed monthly payment you would owe.
Most digital lending platforms, including mPokket, offer this tool within their app or website. It requires no login, no documents, and no commitment. You simply plug in numbers and get an instant estimate. This transparency is designed to help borrowers make informed decisions before they tap "apply."
The formula behind most EMI calculators is straightforward. EMI equals the principal multiplied by the monthly interest rate, divided by one minus the monthly interest rate raised to the negative power of the tenure. You do not need to memorize this. The calculator handles the math in under a second.
Emergencies create tunnel vision. When a hospital asks for a deposit or a landlord demands overdue rent, the only question feels like "how fast can I get money?" Repayment planning drops off the radar entirely.
That gap is where financial trouble begins. A borrower who takes a quick loan without checking the EMI may discover weeks later that the monthly deduction leaves too little for groceries, transport, or other bills. Missed payments can follow, leading to late fees and stress.
Spending 60 seconds on an EMI calculator before applying can prevent this cycle. It forces a simple comparison: "Is this EMI less than 30% to 40% of my monthly income?" If yes, the loan is likely manageable. If not, you can adjust the amount or tenure before borrowing.
mPokket is designed to support this kind of responsible, transparent borrowing. The platform combines speed (approval can happen within minutes) with tools that help users evaluate repayment fit, so urgency and caution work together rather than against each other.
Follow these steps before you apply for an emergency loan on any digital lending platform.
Open the EMI calculator. Find it on the mPokket app, website, or any reliable personal loan EMI calculator online. No registration is needed for most calculators.
Enter the loan amount. Type only the amount your emergency actually requires. If the hospital bill is Rs 25,000, do not round up to Rs 50,000 out of convenience. Borrowing more than you need increases your EMI unnecessarily.
Review the estimated EMI. The calculator will display a monthly figure. Write it down or screenshot it.
Compare EMI to your income. Place the EMI next to your monthly take home pay. Subtract rent, food, transport, and other fixed expenses. If the remaining amount comfortably covers the EMI, the loan fits your budget.
Adjust if needed. If the EMI feels tight, reduce the loan amount or extend the tenure by a month or two. Each small change shifts the monthly burden. Re run the calculator until the number feels safe.
Only after completing these steps should you proceed to the loan application. On mPokket, the application itself is designed to be paperless and fast, with approval possible in minutes and funds transferred directly to your bank account.
Three variables control your EMI. Understanding which one moves the number most helps you make smarter adjustments.
Loan amount. This has the most direct impact. Doubling the principal roughly doubles the EMI. The simplest way to lower your monthly payment is to borrow less. In an emergency, that means calculating the exact expense and resisting the urge to add a buffer.
Tenure. Extending the repayment period spreads the principal over more months, reducing each instalment. However, longer tenure means you pay more total interest. For emergency loans, a moderate tenure (3 to 6 months) often strikes the right balance.
Interest rate. This is usually set by the lender based on your profile. You may not control it directly, but comparing rates across platforms before borrowing can help. mPokket is designed to offer transparent terms, including a Key Fact Statement that shows the applicable rate before you accept the loan.
Even with a calculator in hand, borrowers sometimes stumble. Here are pitfalls to watch for.
Borrowing more than the emergency requires. Extra funds feel like a safety net, but they become extra EMIs. Stick to the actual expense amount.
Ignoring existing obligations. If you already have an active EMI or recurring expense, factor that in before adding a new loan. Your total monthly debt payments should stay within a manageable share of your income.
Skipping the calculator entirely. Speed is important, but 60 seconds of calculation can save weeks of repayment stress. Platforms like mPokket are designed to disburse funds quickly, so the few moments spent on an EMI check do not meaningfully delay access to cash.
Choosing the shortest tenure without checking affordability. A 1 month repayment sounds efficient, but the single large payment may strain your next paycheck. Spreading the cost over 2 or 3 months often makes the loan easier to absorb.
Responsible borrowing during emergencies is not about slowing down. It is about making one small, informed decision before you commit. mPokket supports this approach by combining instant disbursal with transparent repayment tools, so borrowers can move fast and still protect their monthly budget.
A personal loan EMI calculator is a free online tool that estimates your monthly instalment based on the loan amount, interest rate, and tenure you enter. It helps you check repayment affordability before borrowing, and platforms like mPokket offer this tool within their app.
mPokket is designed to offer instant personal loans with a paperless application process. Approval can happen within minutes, and funds are transferred directly to your bank account, making it suitable for urgent needs like medical bills or unexpected repairs.
Financial planning guidelines suggest keeping total EMI payments below 30% to 40% of your monthly take home income. Running an EMI calculator before applying for an emergency loan on mPokket can help you verify that the instalment stays within this safe range.
Yes. Extending the repayment tenure spreads the principal over more months, which lowers each instalment. However, a longer tenure increases total interest paid. Use the mPokket EMI calculator to find a tenure that balances affordable monthly payments with reasonable total cost.
What Are the Most Common Business Loan Myths Holding Entrepreneurs Back?
3 min read • 19 August 2026
Can You Cancel a Business Loan After Sanction but Before Disbursement?
3 min read • 18 September 2026
Working Capital Loan, Cash Credit, or Overdraft: Which One Actually Fits Your Business?
3 min read • 16 September 2026
How to Secure a Startup Business Loan Without Upfront Capital
3 min read • 14 August 2026