4 mins min read • 27 October 2026


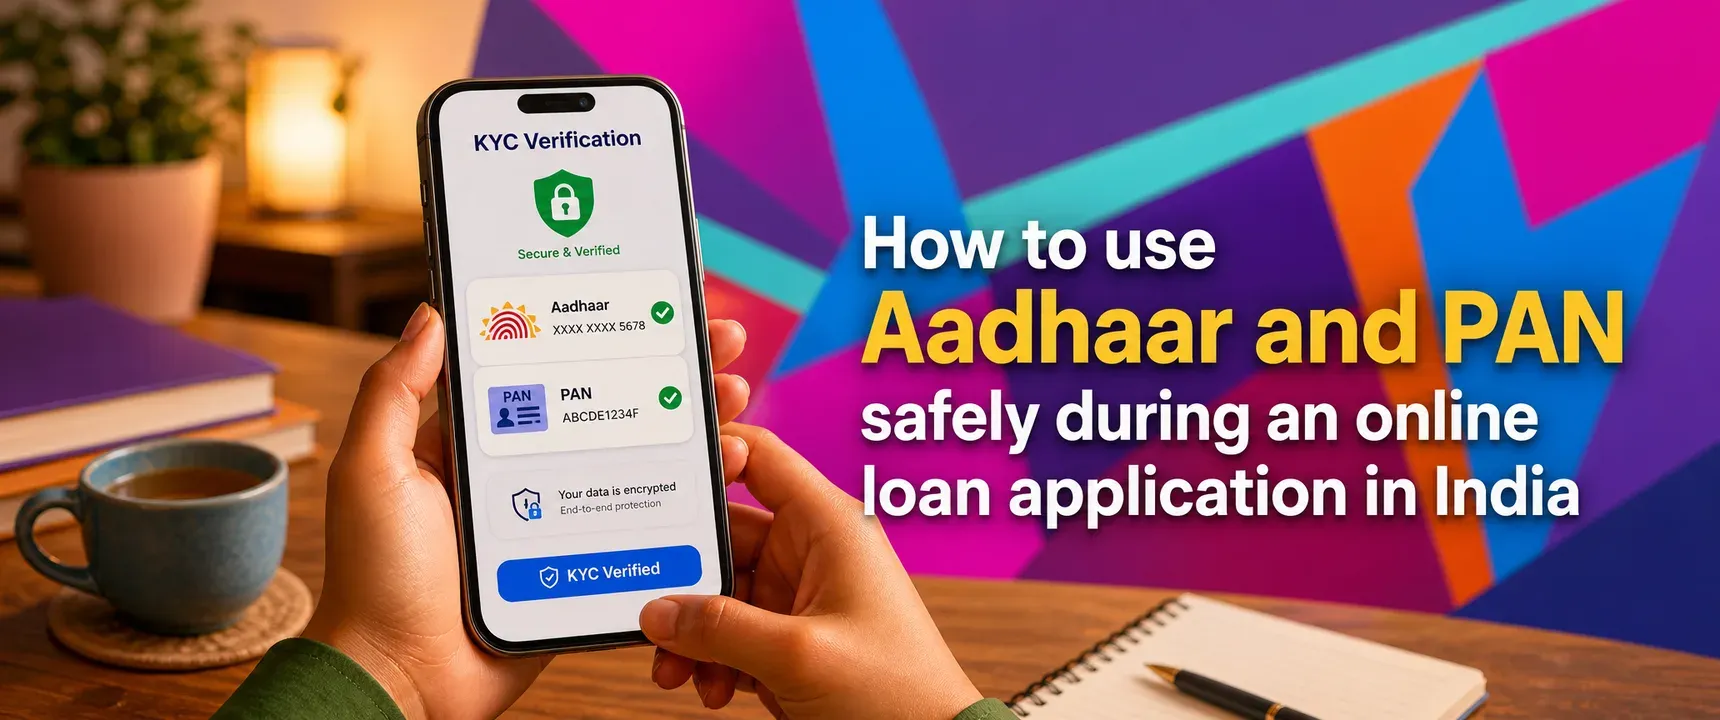
Table of content
How to use Aadhaar and PAN safely for an online loan application
Why Aadhaar and PAN matter
How legitimate KYC works
Red flags to watch for
Safe borrower habits
What mPokket does differently
FAQs
Sharing your Aadhaar and PAN with an online lender feels risky, especially when you have never borrowed before. Stories of identity misuse circulate widely, and the hesitation is understandable. mPokket believes that responsible digital borrowing starts with knowing exactly how your documents are handled, what a legitimate KYC flow looks like, and which red flags signal trouble. This guide walks you through every safety step so you can apply for an Aadhaar PAN loan with confidence.
Follow our Whatsapp Community for more offers and updates.
Join nowAadhaar is your 12 digit unique identity number issued by UIDAI. PAN is your 10 character alphanumeric code issued by the Income Tax Department. Together, they let a digital lender confirm who you are, verify your tax identity, and check your creditworthiness without paper documents.
RBI mandates that every regulated lender complete Know Your Customer verification before disbursing funds. Aadhaar based OTP verification and PAN validation satisfy this requirement digitally. This is why platforms like mPokket can offer a 100 percent online, paperless loan process that takes minutes instead of days.
Understanding the actual verification flow removes much of the anxiety around sharing documents. Here is what happens step by step when you apply on a compliant platform like mPokket.
You type your Aadhaar number and PAN into the app. The app sends your Aadhaar number to UIDAI's authentication server. UIDAI sends an OTP to your registered mobile number. You enter the OTP in the app. At no point does the lender see or store your biometrics.
Your PAN is validated against the Income Tax Department database. This confirms your legal name, date of birth, and tax filing status. The lender uses this to link your identity with credit bureau records.
With verified identity, the lender pulls your credit report (if one exists) and assesses eligibility. Platforms like mPokket can also use alternative data assessment for first time borrowers who lack a credit score.
Before you accept the loan, the lender must display a Key Fact Statement showing the interest rate, total repayment amount, EMI schedule, and all charges. RBI requires this disclosure. Read it carefully before proceeding.
Not every app claiming to offer an Aadhaar PAN loan follows RBI rules. Protect yourself by recognizing these warning signs before you share any document.
An app asks you to send a photo of your Aadhaar or PAN via WhatsApp or email. Legitimate lenders never collect documents through messaging apps. They use encrypted, in app upload or direct API verification with UIDAI.
The app demands upfront fees before loan approval. RBI digital lending guidelines (RBI, 2022) prohibit lenders from charging processing fees before disbursal. Any pre approval payment request is a red flag.
The app has no named NBFC or bank partner. Every legitimate loan app in India must operate through an RBI registered entity. Check the app's terms for the partner NBFC name, then verify it on the RBI website.
The app requests your Aadhaar biometrics (fingerprint or iris scan) directly. Only authorized agencies can collect biometrics, and personal loan apps are not among them. OTP based verification is the standard for digital lending.
Even on a trusted platform like mPokket, your own practices add a critical layer of protection. Follow these habits every time you apply for an online loan.
Use a masked Aadhaar when a full number is not required. UIDAI lets you download a masked version that hides the first eight digits. Some lenders accept this for initial verification before OTP authentication.
Never share your OTP with anyone, including someone claiming to be from the lender's support team. The OTP is sent to your phone for you alone to enter into the app. No legitimate employee will ask for it verbally or via chat.
Check the app's privacy policy before uploading documents. Look for clear statements about data encryption, storage duration, and third party sharing restrictions. RBI compliant lenders must follow specific data handling norms.
After applying, monitor your credit report for unfamiliar hard inquiries. Both CIBIL and other bureaus allow free annual checks. An inquiry you did not authorize could indicate your PAN was misused.
Review the Key Fact Statement line by line. Confirm the interest rate, tenure, EMI amount, and any charges match what was shown during the application. If anything differs, do not proceed.
mPokket is designed to help first time borrowers, students, women, and working professionals access credit safely. The platform uses OTP based digital KYC with Aadhaar and PAN, following RBI digital lending guidelines. Documents are verified through secure API connections, not manual collection. Loan terms are disclosed transparently through a Key Fact Statement before acceptance.
Because mPokket offers a paperless loan process with direct bank transfer, borrowers never need to visit a branch or hand over physical copies of identity documents. This reduces the risk of document interception or unauthorized photocopying that can happen with offline lending.
Applying for an online loan with Aadhaar and PAN is safe when you choose an RBI compliant lender, verify the app's credentials, and practice good document hygiene. mPokket combines digital convenience with transparent KYC, making it possible for first time borrowers and cautious applicants to access credit without compromising their identity. Before your next application, run through the red flags checklist above, and borrow with confidence.
Yes. RBI regulated digital lenders like mPokket use Aadhaar and PAN for online KYC verification. These two documents are sufficient for identity confirmation, enabling paperless, collateral free loan approval through a secure app based process.
It is safe when the app operates through an RBI registered NBFC, uses OTP based Aadhaar verification, encrypts your data, and does not ask for documents via WhatsApp or email. Always verify the lender's registration on the RBI website first.
Download an RBI compliant loan app like mPokket, complete digital KYC with your Aadhaar and PAN, submit income proof if required, review the Key Fact Statement, and accept the offer. Funds are transferred directly to your verified bank account.
Confirm the app has a named RBI registered NBFC partner, uses OTP based Aadhaar authentication, displays a clear privacy policy, and provides a Key Fact Statement before disbursal. Never share OTPs or send document photos through messaging apps.
Working Capital Loan: Everything Small Businesses Should Know
5 min read • 17 July 2026
What Are the Best Options for Instant Financial Assistance?
2 min read • 5 June 2026
Tips to Improve Your Credit Score Before Applying for a Business Loan
3 min read • 30 July 2026
What is CKYC? Central KYC Registry Explained
3 min read • 26 September 2025