4 mins min read • 3 November 2026


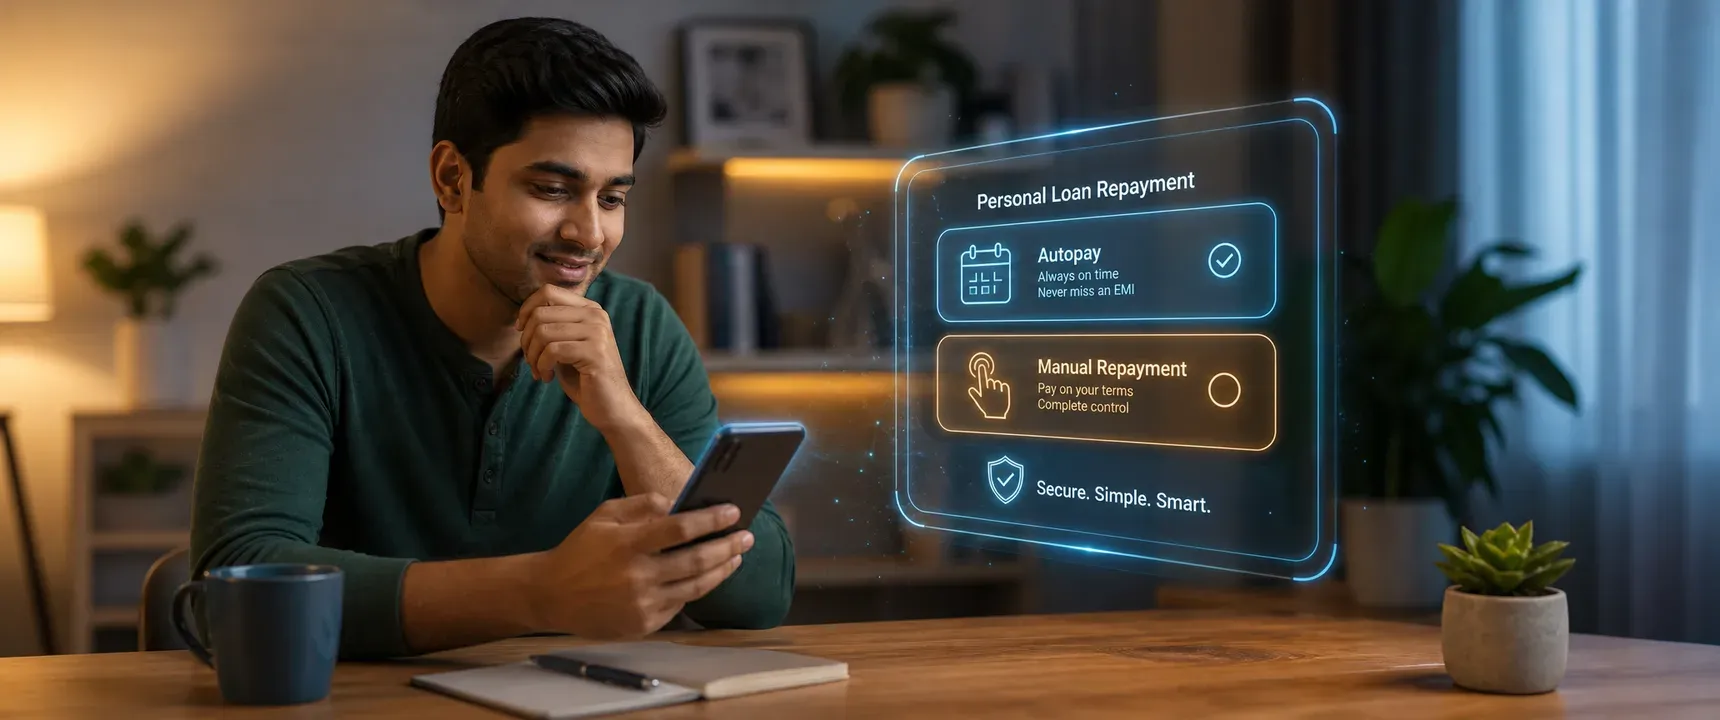
Table of content
Overview
What is autopay for loans?
How does manual repayment work?
Autopay versus manual: key factors
How UPI loan repayment works
Step by step: setting up autopay
When to choose which option
FAQs
Your personal loan from mPokket just landed in your bank account. Now comes the question that quietly stresses most first time borrowers: should you set up autopay for your EMI, or pay manually each month? The answer depends on your income pattern, your comfort with technology, and how much control you want over each payment. This guide from mPokket walks you through both options so you can pick the one that fits your life.
Follow our Whatsapp Community for more offers and updates.
Join nowAutopay is a pre authorized instruction you give to your bank, card provider, or UPI app. On each EMI due date, the agreed amount is deducted automatically. You set it up once, and it runs until the loan is fully repaid or you cancel the mandate.
For digital personal loans on platforms like mPokket, autopay typically works through a UPI autopay mandate or an e-NACH (electronic National Automated Clearing House) registration. Both methods are governed by Reserve Bank of India guidelines on recurring payments.
Once active, autopay removes the step of opening your app, entering the amount, and confirming payment every month. The trade off is that you need sufficient balance in your account on the due date, or the transaction will fail.
Manual repayment means you initiate each EMI payment yourself. On or before the due date, you open your loan app, select the repayment option, and pay using UPI, a debit card, or another supported method.
This approach gives you full visibility into every transaction before it happens. You decide exactly when the money leaves your account, which can matter if your salary or freelance income arrives on unpredictable dates.
The risk is straightforward: if you forget or delay, you may miss the due date. A missed EMI can attract late fees and may affect your credit profile over time.
Choosing between the two is not about which method is objectively better. It is about which method matches your financial habits. Consider these factors before deciding.
Salaried employees with a fixed pay date each month are natural candidates for autopay. The EMI deducts on a predictable date, and the salary has already arrived. Gig workers, freelancers, or those with project based income may prefer manual repayment so they can pay once funds are actually available.
If you tend to forget dates or travel frequently, autopay acts as a safety net. It ensures your EMI is never late as long as your account has sufficient balance. For borrowers building credit history for the first time, this consistency can be valuable.
Manual repayment lets you decide the exact moment money leaves your account. Some borrowers prefer this because they juggle multiple expenses around month end. If you are disciplined about due dates, manual payment gives you that extra layer of control.
Autopay is not foolproof. If your bank account balance is too low on the deduction date, the transaction will bounce. Most lenders, including mPokket, send due date reminders so you can top up your account in advance. A failed autopay attempt does not automatically count as a default, but you still need to make the payment promptly.
UPI has become one of the most common ways to repay personal loan EMIs in India. Whether you choose autopay or manual mode, UPI supports both.
For manual UPI repayment, you open your loan app on the due date, select the pay now option, and complete the transaction through any UPI app linked to your bank account. The payment reflects almost instantly.
For UPI autopay, you approve a one time mandate through your UPI app. This mandate authorizes the lender to pull the EMI amount on each due date. You receive a notification before each deduction, and you can revoke the mandate at any time through your UPI app if you want to switch to manual payments.
mPokket supports UPI based repayment, making it convenient for borrowers who already use UPI for daily transactions. The process is paperless and does not require a branch visit.
Select the autopay or auto debit option.
Choose your preferred method (UPI autopay mandate or e-NACH through your bank account).
Approve the mandate through your UPI app or bank authentication.
Confirm the EMI amount and deduction date.
Ensure your linked account has sufficient balance before each due date.
There is no single right answer. Here is a practical way to think about it. If your salary arrives on a fixed date every month and your EMI due date falls after that, autopay is designed to save you effort and reduce the chance of a missed payment. If your income is irregular or you want to pay a few days early some months and on the due date other months, manual repayment through UPI gives you that flexibility.
Some borrowers start with manual repayment to get comfortable with the process, then switch to autopay after a few months. Others use autopay from day one and simply monitor their bank balance around the due date. Both approaches are valid.
The most important thing is not the method you choose. It is that you never miss a due date. On time repayment protects your credit profile, avoids late fees, and builds the disciplined borrowing habit that can help you access better loan terms in the future. mPokket provides due date reminders and in app repayment options to support whichever path you pick.
Autopay loan repayment is a standing instruction that automatically deducts your EMI from a linked bank account or UPI on the scheduled due date. It removes the need to initiate payment manually each month, which can help prevent missed EMI penalties.
Yes. Digital lenders like mPokket support UPI based EMI repayment. You can pay manually through any UPI app on the due date, or set up a UPI autopay mandate so the EMI is deducted automatically each month.
For manual UPI repayment, you open your loan app, select the payment option, and complete the transaction via your UPI app. For UPI autopay, you approve a one time mandate that authorizes the lender to pull the EMI amount on each due date.
Yes. You can revoke your autopay mandate through your UPI app or bank at any time and switch to manual repayment. Check with your lender's app for the exact steps to cancel or modify the mandate.
How digital lending works in India step by step
5 min read • 10 September 2026
How to Choose the Right Urgent Personal Loan During Financial Emergencies
4 min read • 10 August 2026
What Are the Eligibility Requirements for an Instant Rs. 1000 Loan?
3 min read • 5 June 2026
Need ₹10,000 Urgent Loan Today — What Should You Do To Get It Fast?
4 min read • 30 April 2026
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
