4 mins min read • 31 October 2026


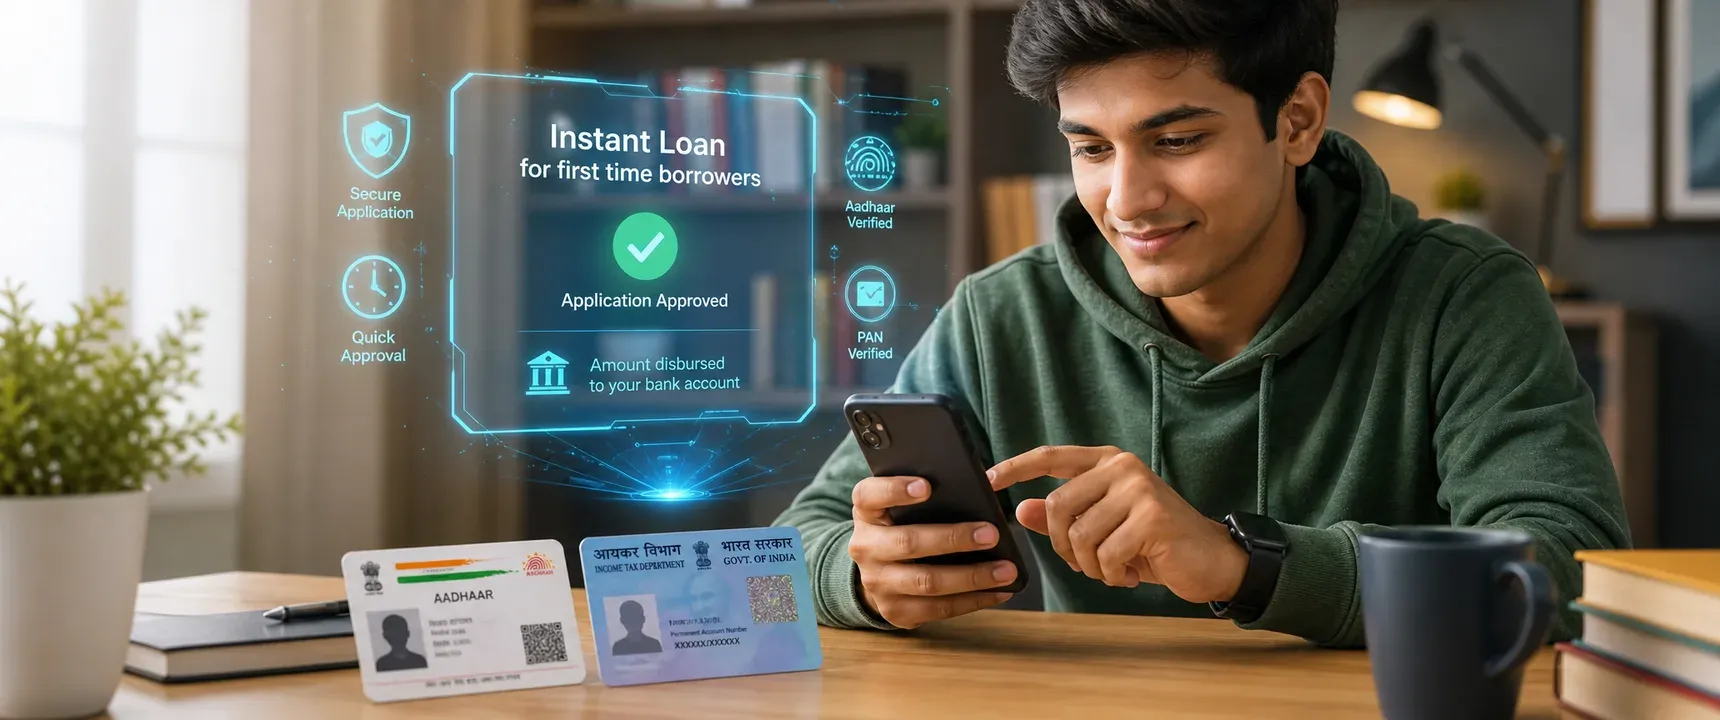
Table of content
How to apply for your first loan in India without credit history
Why no credit history blocks you
How mPokket assesses borrowers differently
Steps
What to avoid as a first time borrower
FAQs
Applying for your first loan feels intimidating when you have no credit history to show. Banks want a CIBIL score. Traditional lenders want proof you have borrowed before. For students, freshers, and young workers in India, this creates a frustrating loop: you cannot build credit without a loan, and you cannot get a loan without credit. mPokket is designed to break that loop by using alternative data signals instead of relying solely on a traditional credit score.
Follow our Whatsapp Community for more offers and updates.
Join nowMost traditional lenders in India rely on CIBIL scores to judge whether a borrower will repay. If you have never taken a loan or used a credit card, your CIBIL file is either empty or shows "no history." Banks treat this as high risk, even if you earn a steady income.
This affects millions of young Indians. College students, interns on stipends, freshers in their first job, and young self employed workers all face the same barrier. They need credit to handle month end expenses, upskilling costs, or medical bills, but the system was not built for them.
mPokket uses an alternative data based lending model. Instead of requiring a perfect CIBIL cutoff, the platform looks at signals that reflect your actual financial behavior. These can include your bank account activity, regular deposits (salary, stipend, or freelance payments), and your digital identity verification through Aadhaar and PAN.
This approach means a first time borrower with consistent bank deposits and valid KYC documents can qualify even without a formal credit profile. The assessment focuses on repayment capacity rather than past borrowing history.
Before you open the app, collect these essentials. Having them ready speeds up the process significantly.
Aadhaar card for identity verification
PAN card for financial identity
Active bank account in your name
Proof of income or occupation
Income proof varies by situation. Salaried employees can use salary slips or bank statements showing regular credits. Interns can use a stipend letter. Freelancers and gig workers can show bank deposits from clients or platform payouts.
Install the mPokket app and register with your mobile number. The app uses OTP based verification to confirm your identity. Fill in your personal details, upload your Aadhaar and PAN, and link your bank account.
Profile completion matters. The more accurate and complete your information, the better the platform can assess your eligibility. mPokket's paperless process means you do not need to visit a branch or submit physical documents.
Once your profile is complete, you can apply for a loan directly within the app. mPokket's digital KYC and alternative assessment process is designed to deliver a decision quickly, often within minutes. If approved, the loan amount can be transferred directly to your verified bank account.
Because the entire process is 100 percent online, there is no waiting for branch appointments or courier pickups. The app handles everything from application to disbursal digitally.
Getting approved is only half the story. How you handle your first loan shapes your financial future. Start with a small amount that fits comfortably within your monthly budget. Do not borrow more than you can repay from your next paycheck or stipend cycle.
Set up autopay or use UPI repayment through the app to make sure you never miss a due date. On time repayment on your first loan helps build a formal credit history. Over time, this can improve your CIBIL score and open doors to larger credit products.
Review the Key Fact Statement before accepting any loan. It shows the interest rate, tenure, total repayment amount, and any applicable charges. Transparent loan terms help you plan repayment without surprises.
Avoid borrowing from multiple apps simultaneously. Each application can trigger inquiries that complicate your thin credit file. Stick with one trusted, RBI compliant platform like mPokket until you establish a repayment track record.
Do not ignore repayment reminders. A single missed EMI on your first loan can make future borrowing harder. Treat your first loan as a credit building opportunity, not just a cash shortfall fix.
Your first loan is a stepping stone. Students, freshers, and young professionals in India can use mPokket's alternative data based assessment to access credit without a traditional credit score. Keep your documents ready, borrow only what you need, repay on time, and you will start building the credit history that traditional lenders require.
Yes. Digital lenders like mPokket use alternative data such as bank account activity, Aadhaar and PAN verification, and income signals to approve first time borrowers who do not have a CIBIL score or prior borrowing record.
mPokket is designed to help first time borrowers access credit without a traditional credit score. The app uses alternative assessment methods, including bank statement analysis and digital KYC, instead of relying solely on CIBIL.
Yes. mPokket uses Aadhaar and PAN for digital KYC verification during the paperless application process. Along with a verified bank account and proof of income, these documents are typically sufficient to apply.
Borrow a small amount you can repay comfortably. Make every EMI payment on time using autopay or UPI. Consistent, timely repayment on your first loan creates a formal credit record that can help improve your CIBIL score over time.
How are Mobile Loan Apps Transforming Borrowing in India in 2026?
4 min read • 11 May 2026
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
How mPokket serves borrowers with limited or no prior credit history
3 mins min read • 20 September 2026
What Mistakes Should Female Business Owners Avoid While Taking a Business Loan?
3 min read • 20 August 2026