How EMI awareness is changing personal loan decisions in India in 2026

4 mins min read  • 17 November 2026

share
copy
img

Table of content

Overview

Why EMI awareness is rising

How a personal loan EMI calculator works

Key trends shaping loan decisions

Affordability checks before application

Tenure choices and total cost

Repayment planning and tools

What this means for borrowers

FAQs

Overview

Before applying for a personal loan, most Indian borrowers now ask a single question: what will my monthly EMI be? That shift from headline loan amounts to monthly outgo is reshaping how people borrow, compare, and repay. mPokket, a digital lending platform focused on responsible borrowing, sees this EMI awareness trend as a turning point for personal loan decisions across India in 2026.

Why EMI awareness is rising

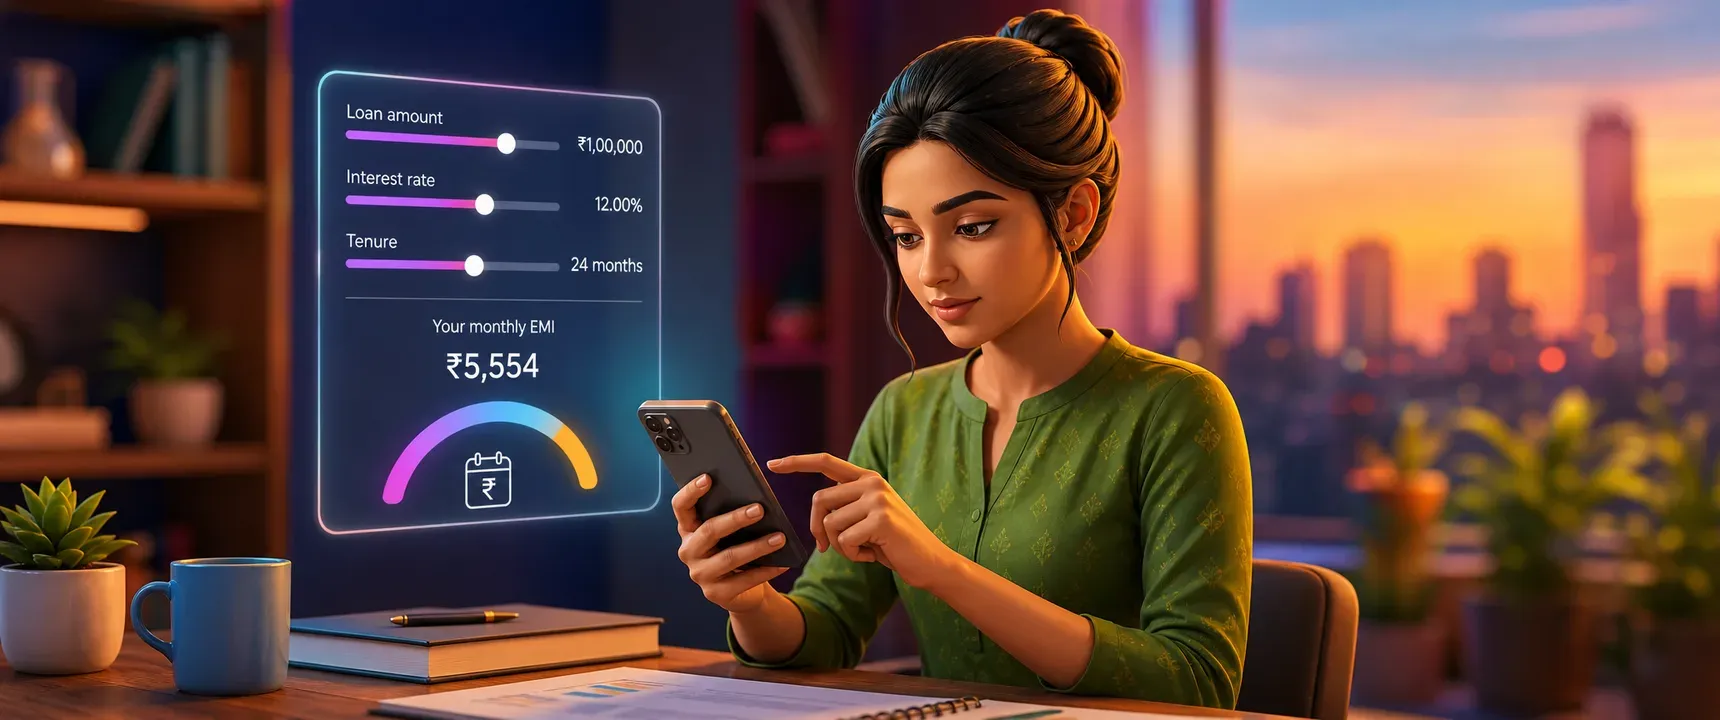
India's digital lending ecosystem has matured rapidly. Borrowers no longer walk into a branch and accept whatever terms are offered. Instead, they open a calculator on their phone, enter a loan amount, adjust the tenure slider, and watch the EMI figure change in real time.

Several forces drive this behaviour. Smartphone penetration keeps climbing. Financial literacy content on social media reaches millions of young adults. And digital lenders like mPokket surface EMI estimates inside the app itself, making the number impossible to ignore.

The result is a borrower who thinks in monthly instalments rather than lump sums. A salaried professional earning Rs 25,000 per month no longer asks "can I get Rs 1,00,000?" but rather "can I handle Rs 5,500 every month for 24 months?" That reframing changes every downstream decision.

How a personal loan EMI calculator works

A personal loan EMI calculator uses a standard mathematical formula. It takes three inputs: principal amount, annual interest rate, and loan tenure in months. The output is the fixed monthly instalment the borrower will pay.

The formula behind most calculators is the reducing balance method. Each EMI contains a portion of principal and a portion of interest. Early instalments carry more interest; later ones repay more principal. Calculators display this split so borrowers see exactly where their money goes.

Using the tool is straightforward. Enter Rs 50,000 as the loan amount, set the interest rate, and choose 12 months. The calculator shows the EMI, total interest, and total repayment. Change the tenure to 6 months and the EMI rises but total interest drops. That instant comparison is what makes the tool powerful.

Key trends shaping loan decisions

EMI awareness does not exist in isolation. It connects to several broader trends in Indian personal lending. The table below summarizes the most important shifts observed in 2026.

TrendWhat is changingImpact on borrower decisions
Pre application EMI checksBorrowers calculate EMI before submitting an applicationFewer applications for unaffordable amounts
Tenure optimizationBorrowers compare 6, 12, and 18 month tenures side by sideBetter alignment between EMI and monthly salary cycle
Affordability first mindsetMonthly budget drives loan size, not the other way aroundLower default risk and reduced financial stress
Calculator led comparisonBorrowers use EMI calculators to compare lenders on total costShift from interest rate alone to total repayment as the key metric
Flexible repayment demandBorrowers expect options like autopay, UPI repayment, and custom EMIHigher adoption of digital repayment tools and fewer missed due dates

Each of these trends reinforces the others. A borrower who checks EMI before applying is more likely to pick a tenure that fits. A borrower who picks the right tenure is more likely to repay on time. And a borrower who repays on time builds credit history, which improves future loan terms.

Affordability checks before application

The most significant behavioural change is the affordability check. In earlier years, many borrowers applied first and worried about repayment later. That sequence created stress, missed payments, and damaged credit profiles.

Now, platforms like mPokket encourage borrowers to run an EMI calculation before they even start the application. The personal loan EMI calculator on mPokket can help users see whether a particular loan amount fits within their monthly budget. If the EMI exceeds a comfortable share of income, the borrower can reduce the amount or extend the tenure.

Financial advisors often suggest keeping total EMI obligations below 30 to 40 percent of monthly income. A calculator makes that guideline actionable. A fresher earning Rs 18,000 per month can instantly see that an EMI of Rs 7,000 would consume nearly 39 percent of income, which is at the upper edge of comfort.

Tenure choices and total cost

Tenure selection is where EMI awareness delivers the clearest value. Consider a simple example. A borrower takes Rs 1,00,000 at a given interest rate. With a 12 month tenure, the EMI is higher but total interest paid is lower. With a 24 month tenure, the EMI drops but total interest rises.

Before calculators became widespread, many borrowers defaulted to the longest available tenure because it produced the smallest monthly number. They did not see the total cost difference. Now, with both figures displayed side by side, borrowers make more informed trade offs.

mPokket supports this by offering flexible repayment options. Borrowers can choose a tenure that matches their cash flow pattern. A salaried employee with a stable monthly income might prefer a shorter tenure to save on interest. A gig worker with variable earnings might choose a slightly longer tenure to keep each instalment manageable.

Repayment planning and tools

EMI awareness extends beyond the moment of borrowing. It shapes how people plan repayment. Borrowers who understand their EMI schedule are more likely to set up autopay, use UPI for timely payments, and avoid late fees.

Digital lenders have responded by building repayment tools directly into their apps. mPokket, for instance, supports autopay EMI and UPI loan repayment, making it easier for borrowers to stay on track. When a borrower knows the exact EMI amount and due date, setting up an automatic deduction becomes a natural next step.

Repayment planning also helps borrowers decide whether to make a lump sum prepayment when they have extra funds. A calculator can show how a partial prepayment reduces remaining tenure or lowers future EMIs. That visibility encourages disciplined borrowing and faster debt clearance.

What this means for borrowers

The rise of EMI awareness is good news for Indian borrowers. It shifts power from the lender to the borrower. When you can see the full cost of a loan before you commit, you make better choices. You borrow what you can afford. You pick a tenure that fits your life. You repay on time and build a stronger credit profile.

For first time borrowers, freshers, and self employed individuals, this trend is especially valuable. These groups often lack deep financial experience. A personal loan EMI calculator gives them a concrete, numbers based way to evaluate a loan, rather than relying on guesswork or peer advice.

mPokket is designed to support this kind of informed borrowing. The platform combines a personal loan EMI calculator with flexible repayment options, paperless application, and direct bank transfer. Together, these features can help borrowers move from curiosity to confident decision making.

As EMI awareness continues to grow, the gap between informed and uninformed borrowers will widen. Those who calculate before they borrow will consistently get better outcomes. The trend is clear: in 2026, the EMI calculator is not just a convenience tool. It is the starting point of every smart personal loan decision in India.

FAQs

1. How to calculate personal loan EMI online?

Enter your loan amount, interest rate, and tenure into an online EMI calculator. The tool applies the reducing balance formula and displays your monthly instalment, total interest, and total repayment instantly. mPokket offers a personal loan EMI calculator that can help you check affordability before applying.

2. What is a personal loan EMI calculator?

A personal loan EMI calculator is a digital tool that estimates your equated monthly instalment based on three inputs: principal, interest rate, and tenure. It helps borrowers compare different loan scenarios and choose an amount and tenure that fit their monthly budget.

3. Does changing loan tenure affect total interest paid?

Yes. A longer tenure lowers each monthly EMI but increases the total interest you pay over the loan's life. A shorter tenure raises the EMI but reduces overall cost. Using a calculator to compare both options helps you find the right balance.

4. How much of my salary should go toward EMI?

Financial advisors generally suggest keeping total EMI obligations below 30 to 40 percent of monthly income. An EMI calculator can help you check whether a specific loan amount and tenure stay within that range before you apply.

5. Can EMI awareness help first time borrowers?

Absolutely. First time borrowers who calculate EMI before applying tend to choose affordable loan amounts and suitable tenures. This reduces the risk of missed payments and helps them build a positive credit history from the start.