3 mins min read • 1 October 2026


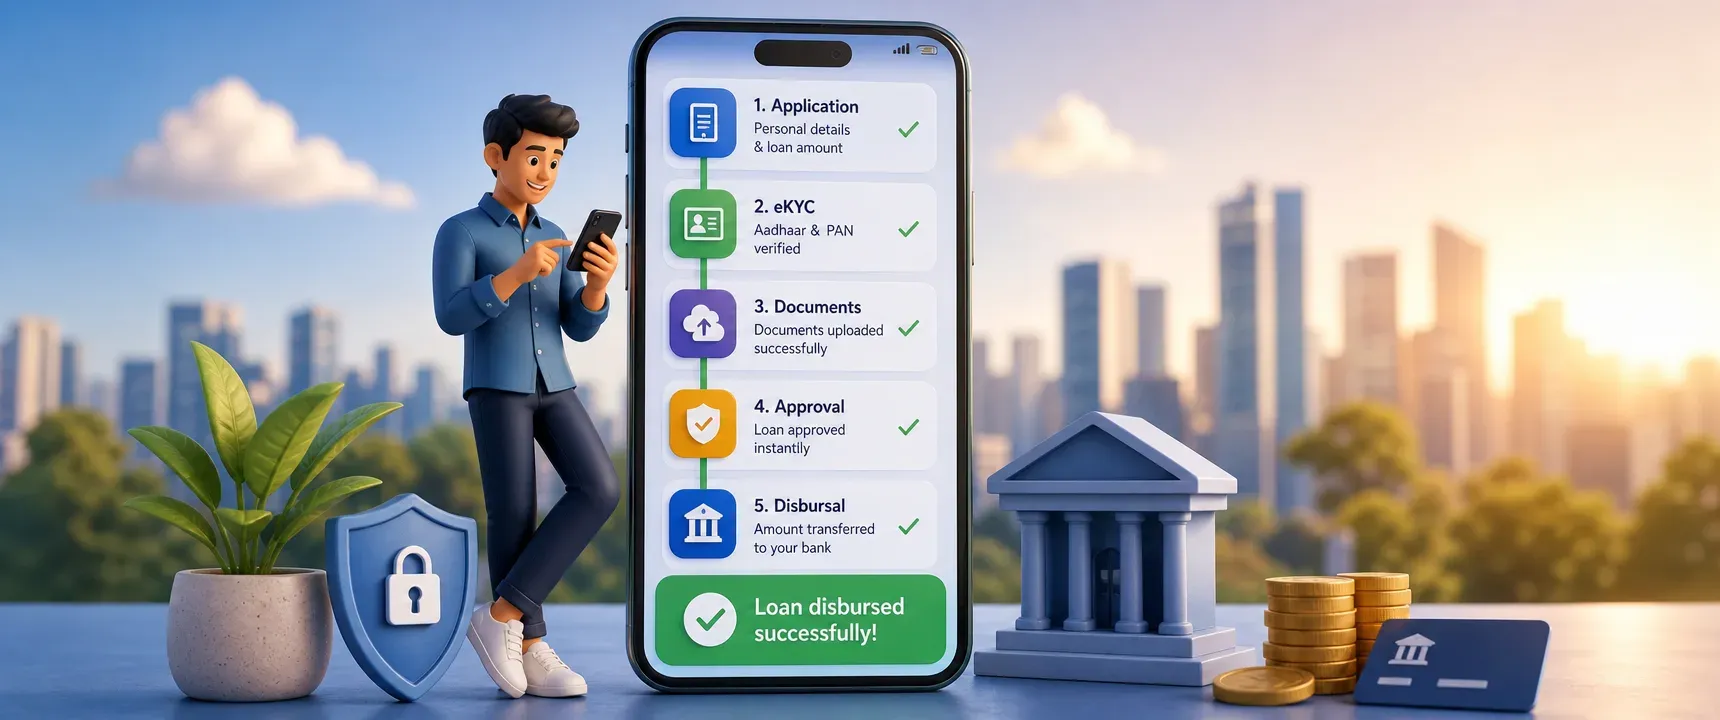
Table of content
What makes an online personal loan fully digital in India
What fully digital means
Five stages of a digital journey
How to spot a partial process
FAQs
Dozens of loan apps in India call themselves "online," yet many still require phone calls, courier documents, or a branch visit before funds reach your account. If you have ever abandoned a loan application halfway because the process turned offline, you are not alone. mPokket operates a 100% digital personal loan journey, and this post defines exactly what "fully digital" means so you can spot the difference before you apply.
Follow our Whatsapp Community for more offers and updates.
Join nowA fully digital online personal loan handles the entire borrower journey through a screen. No courier envelopes, no call center verification, no branch appointment. The borrower downloads an app, submits information, completes identity checks, and receives funds, all without leaving the digital environment.
Many lenders advertise online loans but insert offline steps. A tele-verification call, a request to mail notarized documents, or a mandate to visit a branch for signature can each break the digital chain. These hybrid processes add hours or days and create friction that defeats the purpose of borrowing online.
Under RBI digital lending guidelines, the loan must be disbursed directly into the borrower's bank account by the regulated entity. A truly digital lender follows this by transferring approved funds straight to a verified bank account, completing the loop without intermediaries or cash handoffs.
A personal loan qualifies as fully digital only when each of these five stages stays inside the app or platform.
Mobile application. The borrower fills out a form on a smartphone app. Profile details like name, address, occupation, and income are entered digitally. No printed forms or wet signatures are involved.
eKYC with Aadhaar and PAN. Identity verification happens through OTP based digital KYC. The borrower enters Aadhaar and PAN details, receives an OTP, and completes verification in seconds. A selfie verification step can add an extra layer of fraud prevention, all within the app.
Digital document upload. Income proof, bank statements, or other supporting documents are photographed or uploaded as files. Nothing is couriered or faxed. mPokket is designed to accept these uploads directly inside its app, keeping the process paperless.
Automated approval. The lender's system evaluates the application using digital data. Approval or rejection is communicated through the app or via notification. No loan officer calls to confirm details or request additional physical paperwork.
Direct bank transfer disbursal. Once approved, funds move straight into the borrower's verified bank account. There is no cheque, no demand draft, and no cash pickup. mPokket can help complete this transfer quickly, often within minutes of approval.
Before choosing a lender, check whether any step requires you to go offline. Ask these questions: Does the app require a phone call before approval? Must you visit a branch to sign documents? Will a courier collect or deliver paperwork? Does disbursal happen through a cheque or cash?
If the answer to any of these is yes, the loan is not fully digital. A genuinely paperless loan application, like the one mPokket is designed to offer, keeps every interaction within the app from start to finish.
Borrowers comparing loan apps in India should also confirm that the lender is registered with the RBI or operates through a registered NBFC partner. A digital process is only trustworthy when it follows regulatory norms for data privacy, KYC, and direct bank account disbursal.
Digital lending in India works through mobile apps or web platforms where borrowers apply, complete eKYC using Aadhaar and PAN, upload documents digitally, receive automated approval, and get funds disbursed directly to their bank account without any branch visit or physical paperwork.
Download a loan app like mPokket, fill in your profile, complete OTP based eKYC with Aadhaar and PAN, upload income proof or other required documents, and submit. If approved, the loan amount is transferred directly to your verified bank account.
A fully digital loan app completes application, KYC, document collection, approval, and disbursal entirely within the app. If any step requires a phone call, branch visit, courier, or physical signature, the process is only partially online.
Working Capital Loan: Everything Small Businesses Should Know
5 min read • 17 July 2026
How digital lending works in India step by step
5 min read • 10 September 2026
What Is an NBFC Loan and How Does It Work?
3 July 2026
What is CKYC? Central KYC Registry Explained
3 min read • 26 September 2025
