3 mins min read • 19 October 2026


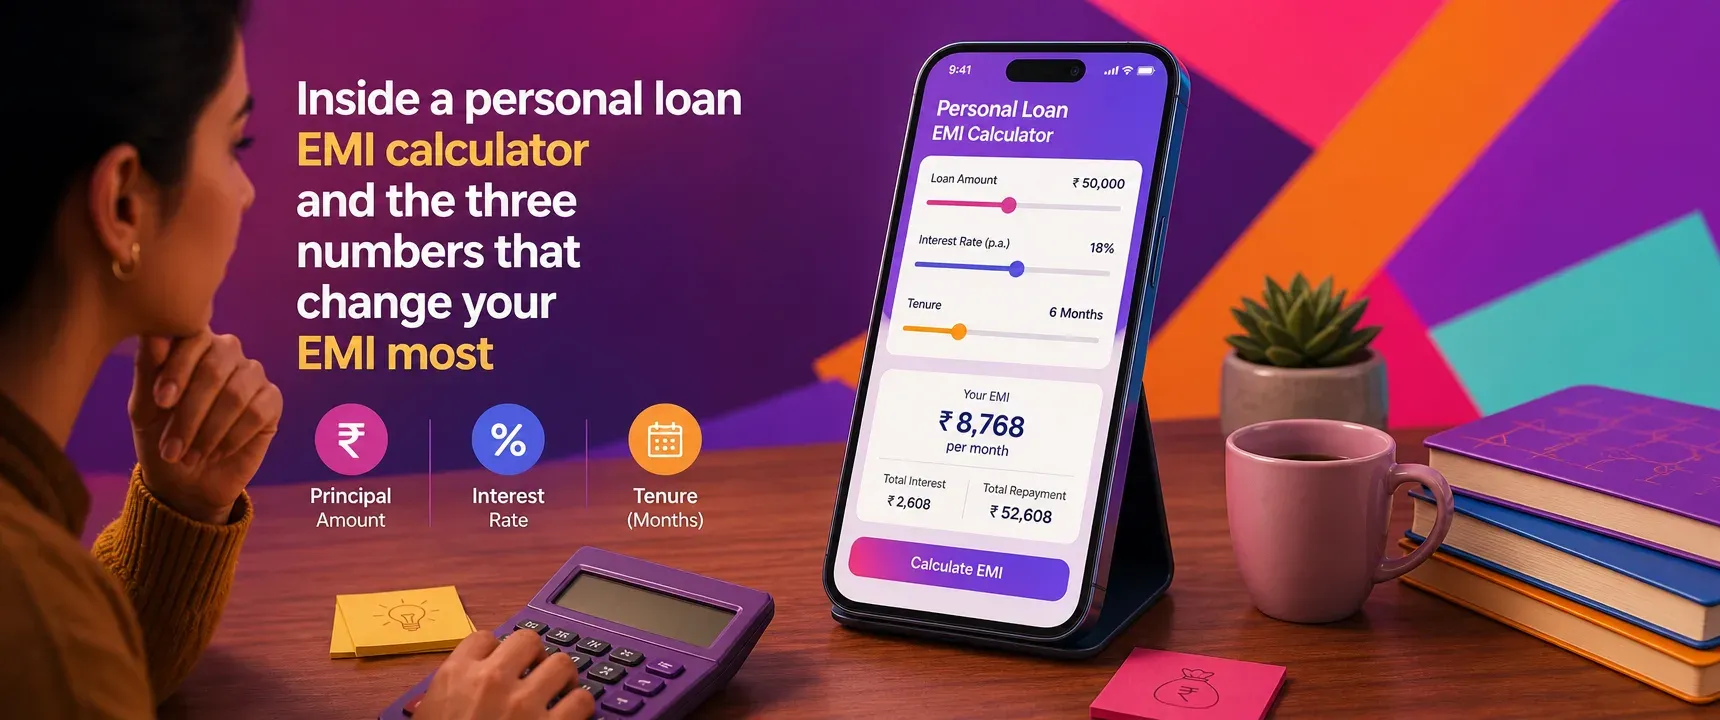
Table of content
Overview
What does the calculator do?
How the EMI formula works
Principal: the amount you borrow
Interest rate: the cost of credit
Tenure: the repayment window
Putting it all together
FAQs
Before you borrow, the monthly number matters more than the total. A personal loan EMI calculator lets you test different scenarios in seconds, yet most borrowers in India never explore what actually moves that number up or down. mPokket believes transparency starts before the application, and understanding the three inputs that shape your EMI is the first step toward borrowing responsibly.
Follow our Whatsapp Community for more offers and updates.
Join nowA personal loan EMI calculator is a simple digital tool. You enter three values and it returns your estimated monthly instalment along with total interest and total repayment. No paperwork, no commitment. The result updates the moment you change any input.
On platforms like mPokket, the calculator sits inside the app or website. It is designed to help salaried employees, self employed professionals, freshers, and other borrowers gauge affordability before they submit an application. Think of it as a budgeting checkpoint.
The math behind every EMI calculator follows one standard equation. EMI equals P multiplied by R multiplied by (1+R) raised to the power N, divided by (1+R) raised to the power N minus 1. Here, P is the principal amount, R is the monthly interest rate (annual rate divided by 12 and then by 100), and N is the tenure in months.
Suppose you borrow Rs 50,000 at an annual interest rate of 18% for 6 months. The monthly rate R becomes 0.015. Plugging those numbers in, the calculator returns an EMI of roughly Rs 8,768. Your total repayment would be about Rs 52,608, meaning you pay approximately Rs 2,608 as interest.
You do not need to memorize this formula. The calculator handles it. What matters is knowing which inputs to adjust and how each one pulls the result in a different direction.
Principal is the loan amount you request. It has the most direct relationship with EMI. Double the principal and your EMI nearly doubles, all else being equal. Halve it and the EMI drops proportionally.
The lesson is straightforward. Borrow only what you need. If you require Rs 30,000 for a medical bill, do not round up to Rs 50,000 for convenience. Every extra rupee increases both your monthly payment and total interest. mPokket encourages borrowers to use the calculator to test the exact amount they need rather than a round figure.
The annual interest rate determines how much the lender charges for providing funds. Even a small change in rate can shift your EMI noticeably over longer tenures. For example, on a Rs 1,00,000 loan over 12 months, moving from 15% to 18% annual interest raises the EMI by roughly Rs 150 per month.
Borrowers often focus on approval speed and overlook the rate. Before you apply, enter the rate quoted in the Key Fact Statement into the calculator. Compare it against your monthly budget. Digital lenders like mPokket display the applicable rate upfront, which supports informed decision making.
Keep in mind that your interest rate can depend on factors such as your credit profile, income stability, and the lender's assessment. A stronger profile can help you access a more favorable rate, which directly lowers your EMI.
Tenure is the number of months over which you repay the loan. A longer tenure reduces your monthly EMI but increases the total interest you pay. A shorter tenure raises the EMI but saves on overall interest cost.
Consider a Rs 1,00,000 loan at 18% annual interest. At 6 months, the EMI is about Rs 17,553 and total interest is roughly Rs 5,318. Stretch the tenure to 12 months and the EMI drops to about Rs 9,168, but total interest climbs to around Rs 10,016. The monthly burden falls, yet you pay nearly double the interest.
This trade off is the most important insight the calculator reveals. Use it to find the tenure where your EMI stays comfortably below 30% to 40% of your monthly income. That range can help you avoid month end cash crunches and missed payments.
| Scenario | Principal (Rs) | Annual rate (%) | Tenure (months) | Approx. EMI (Rs) | Total interest (Rs) |
|---|---|---|---|---|---|
| Low amount, short tenure | 30,000 | 18 | 3 | 10,303 | 909 |
| Medium amount, medium tenure | 50,000 | 18 | 6 | 8,768 | 2,608 |
| Higher amount, longer tenure | 1,00,000 | 18 | 12 | 9,168 | 10,016 |
The table above shows how changing one or two inputs reshapes the outcome. Run your own numbers on the mPokket personal loan EMI calculator before you apply. Adjust principal first, then tenure, then compare rates if multiple options are available.
Borrowing with clarity reduces surprises. When you know exactly what your EMI will be, you can set up autopay, plan your monthly budget, and repay on time. That consistency can help build a positive credit history, which may improve your eligibility for future borrowing. mPokket provides these calculator tools as part of its commitment to transparent, responsible digital lending.
Enter your loan amount, annual interest rate, and repayment tenure into a personal loan EMI calculator. The tool applies the standard EMI formula and returns your estimated monthly instalment, total interest, and total repayment instantly. mPokket offers this calculator on its platform.
It is a digital tool that computes your equated monthly instalment based on three inputs: principal, interest rate, and tenure. It helps borrowers plan repayment before applying for a loan, supporting informed and responsible borrowing decisions.
Three factors drive your EMI: the principal amount you borrow, the annual interest rate charged by the lender, and the tenure in months. Changing any one of these inputs will raise or lower your monthly payment.
You can reduce EMI by borrowing a smaller principal, choosing a longer tenure, or securing a lower interest rate. Use a personal loan EMI calculator to test different combinations and find the monthly payment that fits your budget comfortably.
What Determines Your Personal Loan Eligibility? 5 Key Factors Explained
6 min read • 9 July 2026
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
What Is a Key Facts Statement (KFS) in an Online Business Loan?
2 min read • 10 September 2026
What should you compare before choosing a loan app in India for urgent needs?
3 mins min read • 21 September 2026
A responsible borrowing framework for instant personal loans in India
3 mins min read • 22 September 2026