3 mins min read • 10 November 2026


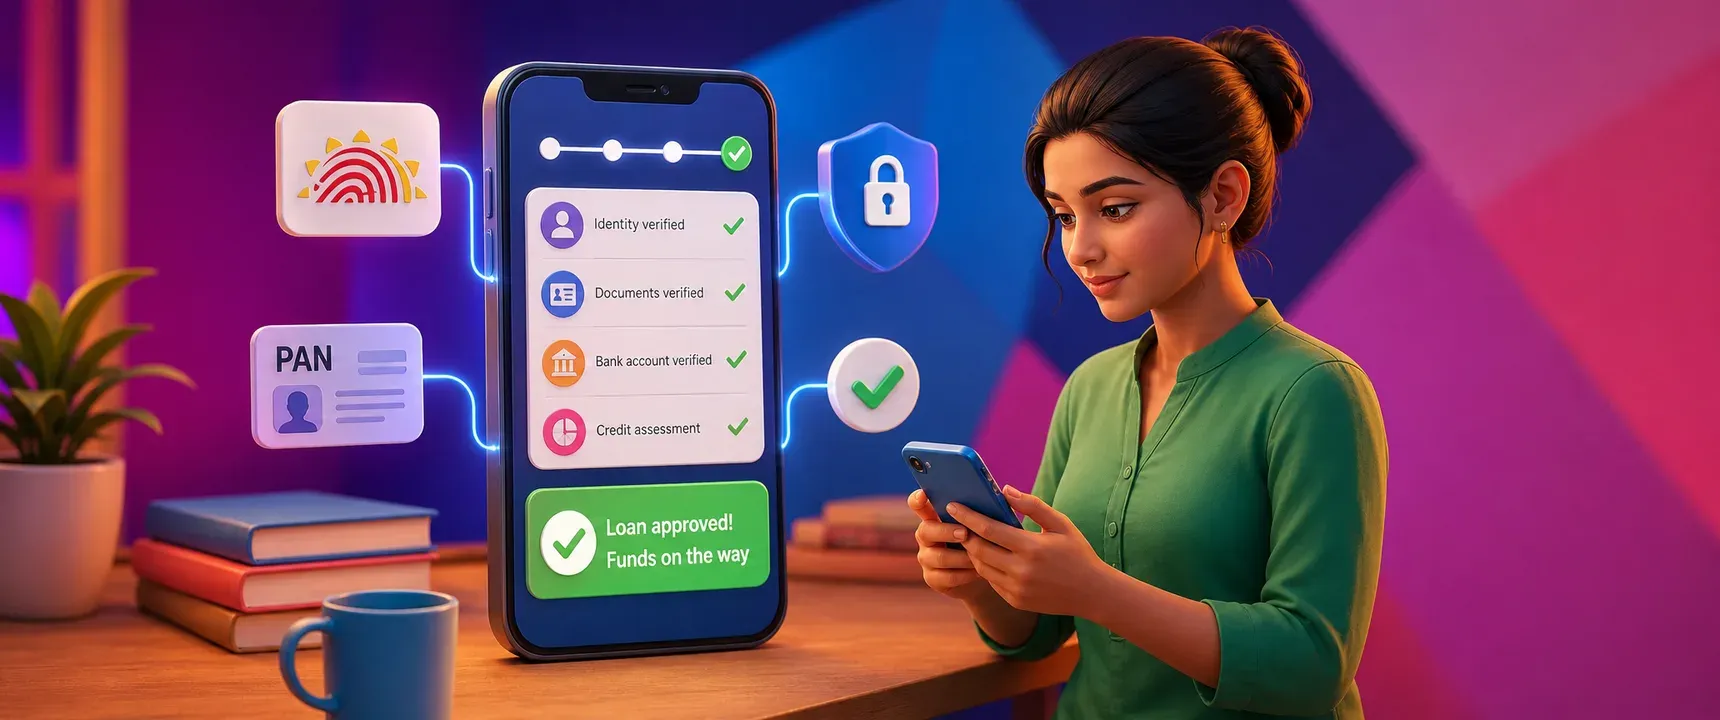
Table of content
Summary
What triggers the process?
How does digital KYC verify identity?
How is creditworthiness assessed?
What happens at decisioning?
How are funds disbursed?
Why does speed matter?
FAQs
Every time you tap "apply" on a digital loan app, a sequence of automated checks fires in the background. For borrowers in India, understanding what happens between that tap and the approval notification can be the difference between trusting a platform and abandoning it. mPokket, a digital lending platform designed for quick personal loans, is designed to complete this entire journey in as few as seven minutes. Here is exactly how instant approval works inside a digital loan app in India.
Follow our Whatsapp Community for more offers and updates.
Join nowThe journey begins when a borrower downloads the loan app and registers with a mobile number. Profile completion follows: basic personal details, occupation, and income information. On mPokket, this step is paperless and can be done entirely on a smartphone.
Once the profile is submitted, the app initiates the first layer of checks. The borrower's declared information is matched against the documents they upload. This is where digital KYC enters the picture.
Digital KYC, or Know Your Customer verification, replaces the traditional in person document check. On a platform like mPokket, borrowers upload their Aadhaar card and PAN card. The system then sends an OTP to the Aadhaar linked mobile number for verification.
This OTP based verification confirms that the person applying is the actual holder of the Aadhaar number. The PAN card is cross referenced to validate the borrower's tax identity. A selfie may also be captured and matched against the photo on the identity document.
The entire KYC step is governed by Reserve Bank of India (RBI) guidelines on digital lending, which require lenders to verify borrower identity before disbursing funds. Because these checks are automated, they complete in seconds rather than the hours or days a physical branch visit would require.
After identity verification, the app moves to underwriting. This is the stage where the system decides whether the borrower qualifies and, if so, for how much.
Traditional banks rely heavily on CIBIL scores and salary slips. Digital lenders like mPokket can supplement or replace those signals with alternative data assessment. This approach evaluates factors such as:
| Assessment factor | What it reveals |
|---|---|
| Bank account activity | Income regularity and spending patterns |
| Occupation and employer details | Employment stability and earning potential |
| Existing repayment history (if any) | Past borrowing discipline |
| App based behavioral signals | Profile completeness and consistency |
For first time borrowers, freshers, or those without a formal credit score, alternative data assessment is designed to help bridge the gap. mPokket positions itself as a platform where a perfect CIBIL score is not necessarily a prerequisite for approval.
The underwriting engine processes these data points through automated rules and scoring models. If the borrower meets the platform's eligibility criteria, the system generates a loan offer with a specific amount, tenure, and interest rate.
Decisioning is the moment the system says yes or no. On mPokket, this step is designed to happen within minutes of application submission. The borrower receives a Key Fact Statement that outlines the loan amount, interest rate, EMI schedule, and total repayment obligation.
This transparency step is mandated by RBI's digital lending guidelines. The Key Fact Statement ensures borrowers understand the cost of the loan before they accept it. Once the borrower reviews and accepts the offer, the system triggers disbursal.
After acceptance, the approved loan amount is transferred directly to the borrower's verified bank account. mPokket uses direct bank transfer for disbursal, which means funds move from the lender to the borrower's account without passing through a third party wallet or intermediary.
This direct transfer model aligns with RBI's requirement that loan funds must be credited to the borrower's bank account, not to a prepaid instrument or wallet. For many borrowers, the funds can arrive on the same day the application is approved.
Speed in digital lending is not just a convenience feature. For a salaried employee facing a month end cash crunch, a fresher covering relocation costs, or a housewife managing an unexpected household expense, waiting days for a bank decision is not practical.
mPokket's seven minute approval positioning reflects the efficiency of automated KYC, alternative data scoring, and instant decisioning working together. Each layer removes a manual bottleneck that traditional lending processes carry.
Borrowers benefit from this speed only when the process is also transparent. Knowing that your Aadhaar is verified through government databases, that your repayment capacity is assessed through real data, and that your loan terms are disclosed upfront through a Key Fact Statement builds the kind of trust that keeps borrowers coming back.
If you are considering a digital loan in India, understanding these steps can help you evaluate any instant loan app with confidence. mPokket is designed to make each stage visible, fast, and compliant with RBI's digital lending framework.
Loan apps like mPokket use automated digital KYC, alternative data assessment, and real time underwriting to verify identity and assess repayment capacity within minutes. This removes manual steps and is designed to enable same day approval and disbursal to a verified bank account.
Digital lending refers to the process of applying for, receiving, and repaying loans through online platforms or mobile apps. In India, RBI regulates digital lending to ensure borrower protection, requiring identity verification, transparent terms, and direct bank account disbursal.
mPokket is designed to approve eligible borrowers in approximately seven minutes through a paperless, app based process. Approval speed depends on profile completeness, successful KYC verification, and meeting the platform's eligibility criteria.
RBI regulated digital lenders are required to follow strict data protection and KYC norms. On mPokket, Aadhaar and PAN are used for OTP based identity verification against government databases. Always verify that a loan app is RBI compliant before sharing documents.
What Mistakes Should Female Business Owners Avoid While Taking a Business Loan?
3 min read • 20 August 2026
5 Reasons Your Business Needs a Working Capital Loan
4 min read • 28 July 2026
Which Is The Most Trusted Loan App In India?
4 min read • 1 May 2026
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
