3 mins min read • 13 November 2026


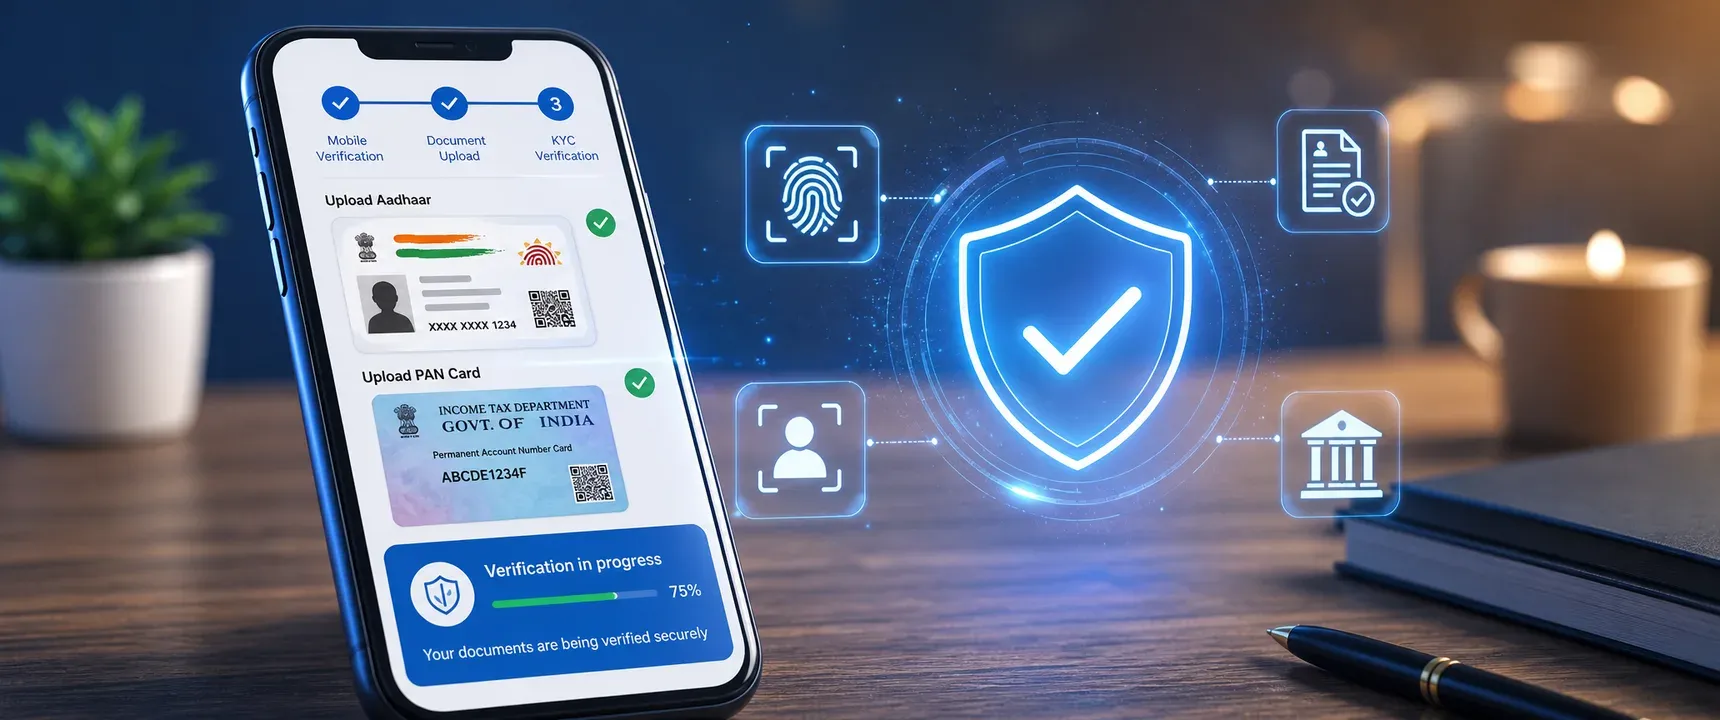
Table of content
Summary
Why Aadhaar and PAN matter
How onboarding works on mPokket
What digital KYC verifies
Who can use this process
Keeping your data safe
FAQs
What is Aadhaar PAN based onboarding? - It is a digital KYC process where an online loan app like mPokket uses your Aadhaar card and PAN card to verify your identity, complete KYC, and move your application forward without physical paperwork or branch visits.
What documents are required for an instant personal loan? - At a minimum, you need a valid Aadhaar card (for identity and address verification) and a PAN card (for financial identity). mPokket may also ask for a selfie, bank account details, and proof of occupation depending on your profile.
Can I get a loan with Aadhaar and PAN card? - Yes. mPokket is designed to let eligible borrowers apply using Aadhaar and PAN as core documents. OTP based Aadhaar verification and PAN validation together satisfy digital KYC requirements set by regulatory guidelines.
How fast is the onboarding process? - mPokket's onboarding can be completed in minutes. After downloading the app, you upload documents, complete OTP verification, and receive a decision quickly, with funds transferred directly to your verified bank account upon approval.
Follow our Whatsapp Community for more offers and updates.
Join nowAadhaar is India's biometric identity system, issued by UIDAI. It links your name, photograph, and address to a unique 12 digit number. PAN, issued by the Income Tax Department, ties your financial transactions to a permanent account number. Together, they form the backbone of digital KYC in India.
Regulatory guidelines from the Reserve Bank of India (RBI) allow lenders to perform video or OTP based KYC using Aadhaar. PAN verification confirms your tax identity and helps the lender assess basic financial eligibility. mPokket uses both documents to run a paperless verification that replaces the traditional in person KYC process.
This combination is especially important for first time borrowers, freshers, and individuals without extensive documentation. Instead of gathering salary slips, utility bills, or employer letters, applicants can begin their loan journey with just these two cards.
The onboarding process on the mPokket app follows a structured sequence. Each step is designed to verify identity, confirm eligibility, and prepare the application for a lending decision.
| Step | What happens | Document or action required |
|---|---|---|
| 1. App download and registration | You register with your mobile number and create a profile | Mobile number, basic personal details |
| 2. Aadhaar upload and OTP verification | The app validates your identity and address through UIDAI's OTP based system | Aadhaar card number, OTP sent to Aadhaar linked mobile |
| 3. PAN card upload | Your financial identity is verified against Income Tax Department records | PAN card image or number |
| 4. Selfie verification | A live selfie is matched against your Aadhaar photograph for liveness check | Camera access on your device |
| 5. Bank account and occupation details | You provide your bank account for disbursal and share proof of occupation or income | Bank account number, IFSC, occupation proof |
| 6. Eligibility assessment and approval | mPokket evaluates your profile and assigns a credit limit if eligible | No additional action needed |
The entire flow is completed within the app. There is no branch visit, no courier of physical documents, and no waiting for manual verification queues.
Digital KYC through Aadhaar and PAN is not just a formality. Each verification step serves a specific compliance and risk purpose.
Aadhaar OTP verification confirms that the person applying is the legitimate holder of that Aadhaar number. The OTP is sent to the mobile number registered with UIDAI, which adds a layer of authentication that prevents impersonation.
PAN verification cross checks the applicant's name and date of birth against Income Tax Department records. It also helps the lender confirm whether the PAN is active and valid, which is a regulatory requirement for financial transactions above certain thresholds.
The selfie or liveness check ensures that the person submitting documents is physically present during the application. This step guards against identity fraud where someone might use another person's Aadhaar and PAN details.
Together, these checks satisfy the KYC norms that RBI mandates for digital lenders. mPokket completes this verification digitally, which is why the process can move from application to approval in minutes rather than days.
mPokket's Aadhaar and PAN based onboarding is designed to be accessible across borrower segments. Salaried employees, self-employed professionals, freshers starting their first job, gig workers, and even homemakers exploring small loans can initiate the process with these two documents.
For borrowers without a credit history, this approach is particularly valuable. Traditional lenders often require CIBIL scores or extensive financial records. mPokket's digital KYC flow can help first time borrowers enter the formal credit system by using alternative data assessment alongside Aadhaar and PAN verification.
The paperless nature of the process also benefits applicants in smaller cities or rural areas who may not have easy access to a bank branch or document notarization services.
Sharing Aadhaar and PAN details with any app raises legitimate security concerns. mPokket follows RBI's digital lending guidelines, which require that borrower data is stored securely and used only for the stated purpose of loan processing.
Before sharing your documents, verify that the app is RBI compliant and that the lending partner is a registered NBFC. Check that the app requests only the permissions it needs, such as camera access for selfie verification. Avoid apps that ask for unnecessary access to contacts, gallery, or SMS.
mPokket's OTP based Aadhaar verification means the app does not store your biometric data. The OTP mechanism, managed by UIDAI, ensures that verification happens through a secure government channel rather than through the app's own servers.
Borrowers who complete onboarding through mPokket can expect transparent loan terms, including a Key Fact Statement that outlines interest rates, tenure, and total repayment before they accept the loan offer.
If you are considering an online loan and want a process that starts and finishes on your phone, mPokket's Aadhaar and PAN based onboarding is designed to reduce friction while meeting regulatory standards. Download the app, keep your Aadhaar and PAN ready, and complete your profile to check your eligibility.
mPokket requires a valid Aadhaar card and PAN card as core documents. Depending on your profile, you may also need to provide a selfie, bank account details, and proof of occupation or income.
Yes, mPokket is designed to let eligible borrowers start and complete the application using Aadhaar and PAN. OTP based Aadhaar verification and PAN validation together fulfill digital KYC requirements for the loan process.
mPokket follows RBI digital lending guidelines for data security. Aadhaar verification uses UIDAI's OTP system, so biometric data is not stored by the app. Always confirm the app is linked to a registered NBFC before sharing documents.
The entire onboarding process on mPokket can be completed in minutes. After uploading your Aadhaar and PAN, completing OTP verification, and submitting a selfie, you can receive an eligibility decision quickly within the app.
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
What Are the Most Common Business Loan Myths Holding Entrepreneurs Back?
3 min read • 19 August 2026
5 Reasons Your Business Needs a Working Capital Loan
4 min read • 28 July 2026
