3 mins min read • 15 October 2026


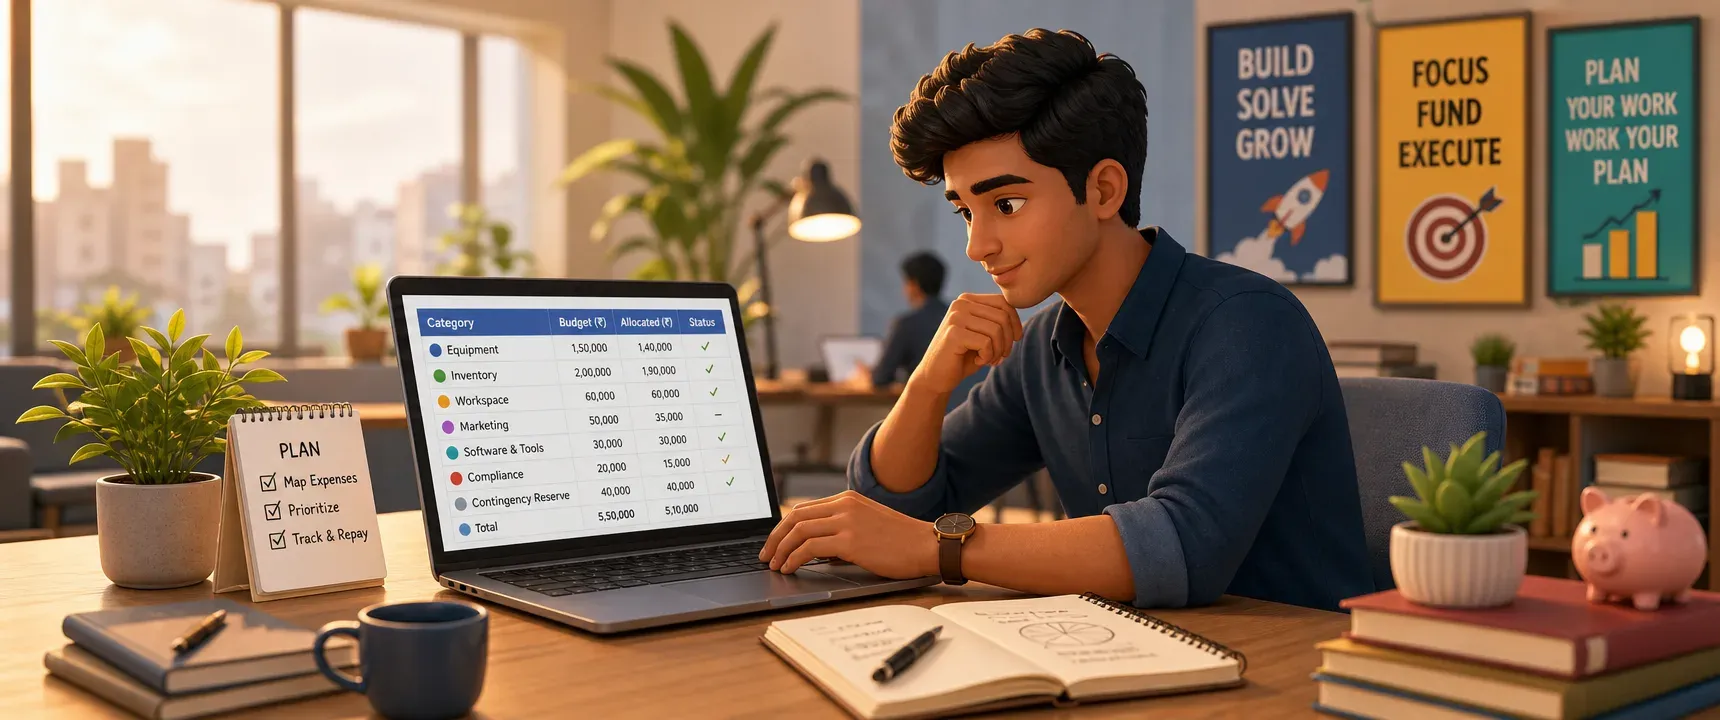
Table of content
Summary
Why launch stage loans need a plan
Best practices for using startup loan funds
Common mistakes founders make
How mPokket supports founders
FAQs
What is a startup business loan? - A startup business loan is short-term capital designed for early stage operating expenses such as equipment, inventory, workspace setup, and initial marketing. mPokket offers collateral-free digital access to such funds with minimal documentation, making it accessible to founders without long business histories.
Why does launch spending discipline matter? - Founders who allocate loan funds without a plan often exhaust capital before revenue stabilizes. Categorizing every rupee across fixed costs, variable costs, and a contingency reserve can help prevent cash flow gaps during the first 90 days.
How should founders prioritize expenses? - Revenue generating expenses (inventory, equipment, sales tools) should come first. Non-essential costs like premium office space or large branding campaigns should wait until the business generates consistent income.
What repayment approach works best? - Aligning EMI due dates with expected revenue cycles, using autopay to avoid missed payments, and keeping total EMI below 30% of projected monthly income can help founders repay without straining operations.
Follow our Whatsapp Community for more offers and updates.
Join nowA startup business loan is not a windfall. It is borrowed capital with a repayment obligation. Founders who treat it as free money often face a cash crunch within 60 days. The difference between a surviving startup and a struggling one frequently comes down to how the first loan was deployed.
Digital lenders like mPokket offer quick loan access with minimal documentation and no collateral requirement. This speed is valuable, but it also means founders must bring their own spending discipline. No lender will audit how you spend the funds. That responsibility sits entirely with the founder.
Before applying, write down every expense your business will face in the first 90 days. Separate these into three categories: essential (without which the business cannot operate), important (which accelerate growth), and optional (which can wait). This simple exercise prevents reactive spending.
Calculate the exact amount you need. Many founders borrow a round number without matching it to actual costs. List every line item: equipment, raw materials, packaging, rent deposit, digital tools, and regulatory fees. Add a 10% buffer for unexpected costs. Borrow only what this total demands.
Spend first on items that directly produce income. For a food delivery startup, that means kitchen equipment and initial ingredients. For an e-commerce venture, it means inventory and a functional website. Marketing and branding matter, but they should follow, not lead, your spending sequence.
Open a dedicated business bank account and route all loan funds through it. This creates a clear audit trail, simplifies GST compliance, and prevents the common mistake of dipping into business capital for personal expenses. mPokket disburses funds directly to your verified bank account, making this separation straightforward from day one.
Use part of your loan strategically by negotiating bulk or advance payment discounts with suppliers. Paying a vendor upfront for three months of raw materials at a 10% discount effectively stretches your loan further. This works especially well for inventory purchase and equipment finance.
Premium office space, expensive branding, and large team hires can wait. Many successful Indian startups launched from home or shared workspaces. Allocate loan funds to operational necessities first. Upgrade your workspace and team size only after revenue covers basic operating costs.
Set aside 15% to 20% of your loan amount as an untouched reserve. Launch timelines almost always slip. A delayed supplier shipment, an unexpected compliance fee, or a slow first month of sales can derail a business that spent every rupee on day one. This reserve acts as your financial safety net during the startup runway period.
When selecting your repayment tenure, match EMI due dates to your expected cash inflow pattern. If your business collects payments weekly, set aside EMI funds each week rather than scrambling at month end. mPokket offers flexible repayment options and autopay features that can help founders avoid missed payments and protect their credit profile.
Overspending on marketing before product readiness is one of the most frequent errors. Founders pour loan money into social media ads before their product or service can handle the resulting demand. This wastes capital and damages early customer relationships.
Another mistake is ignoring repayment planning entirely. Some founders assume revenue will arrive fast enough to cover EMIs. A safer approach is to plan repayment as if revenue will be 50% lower than your optimistic projection. This conservative estimate protects against the reality that most startups take longer to generate consistent income than their founders expect.
Borrowing more than necessary is equally dangerous. A larger loan means higher EMIs and more interest paid over the tenure. Borrow the minimum viable amount. You can always apply for additional working capital later if the business grows and your repayment history is strong.
mPokket is designed to help early stage entrepreneurs access unsecured business loans through a 100% online process. The application requires minimal documentation, and funds can be disbursed directly to a verified bank account. For founders without a long credit history, mPokket uses alternative assessment methods, which can help first-time borrowers access formal credit.
The platform also supports disciplined repayment through autopay EMI options and UPI loan repayment, reducing the risk of missed due dates. Founders can use the business loan EMI calculator to estimate monthly obligations before borrowing, ensuring the EMI fits within projected cash flow.
Responsible use of a startup loan through mPokket can also help founders build a credit profile early. On-time repayment creates a positive credit history, which improves eligibility for larger business expansion loans as the venture grows.
Launch stage funding is a tool, not a solution. The founders who succeed are those who pair fast capital access with careful, category-wise deployment. Map your expenses, prioritize revenue generating costs, maintain a contingency reserve, and plan repayment conservatively. These practices turn a startup business loan from a risk into a runway.
Collateral-free digital loans from platforms like mPokket can help MSMEs and startups access quick working capital with minimal documentation. These unsecured business loans are designed for founders who need funds for inventory, equipment, or early operations without pledging assets.
List every launch expense, including equipment, inventory, rent, and regulatory costs. Add a 10% to 20% buffer for unexpected needs. Borrow only the total required rather than rounding up to a larger amount, which increases EMI burden unnecessarily.
Digital lenders like mPokket use alternative data assessment methods to evaluate applicants who are new to formal credit. Founders without an established credit score can still apply through a paperless process using Aadhaar and PAN verification.
Revenue generating expenses such as inventory, production equipment, and essential digital tools should come first. Non-essential costs like premium office space or large branding campaigns should be deferred until the business generates consistent income.
Setting up autopay through mPokket can help ensure EMI payments are deducted automatically on the due date. Founders should also align their repayment tenure with expected revenue cycles and keep total EMI below 30% of projected monthly income.
Is GST Registration Mandatory for a Business Loan in India?
3 min read • 10 September 2026
Unsecured Business Loans: Benefits, Features, and Reasons to Consider One
4 min read • 27 July 2026
How Your CIBIL Score Affects Business Loan Approval
4 min read • 3 August 2026
How Self-Employed Individuals Should Compare Loan Apps: A 2026 Guide
2 min read • 13 May 2026
