4 mins min read • 2 November 2026


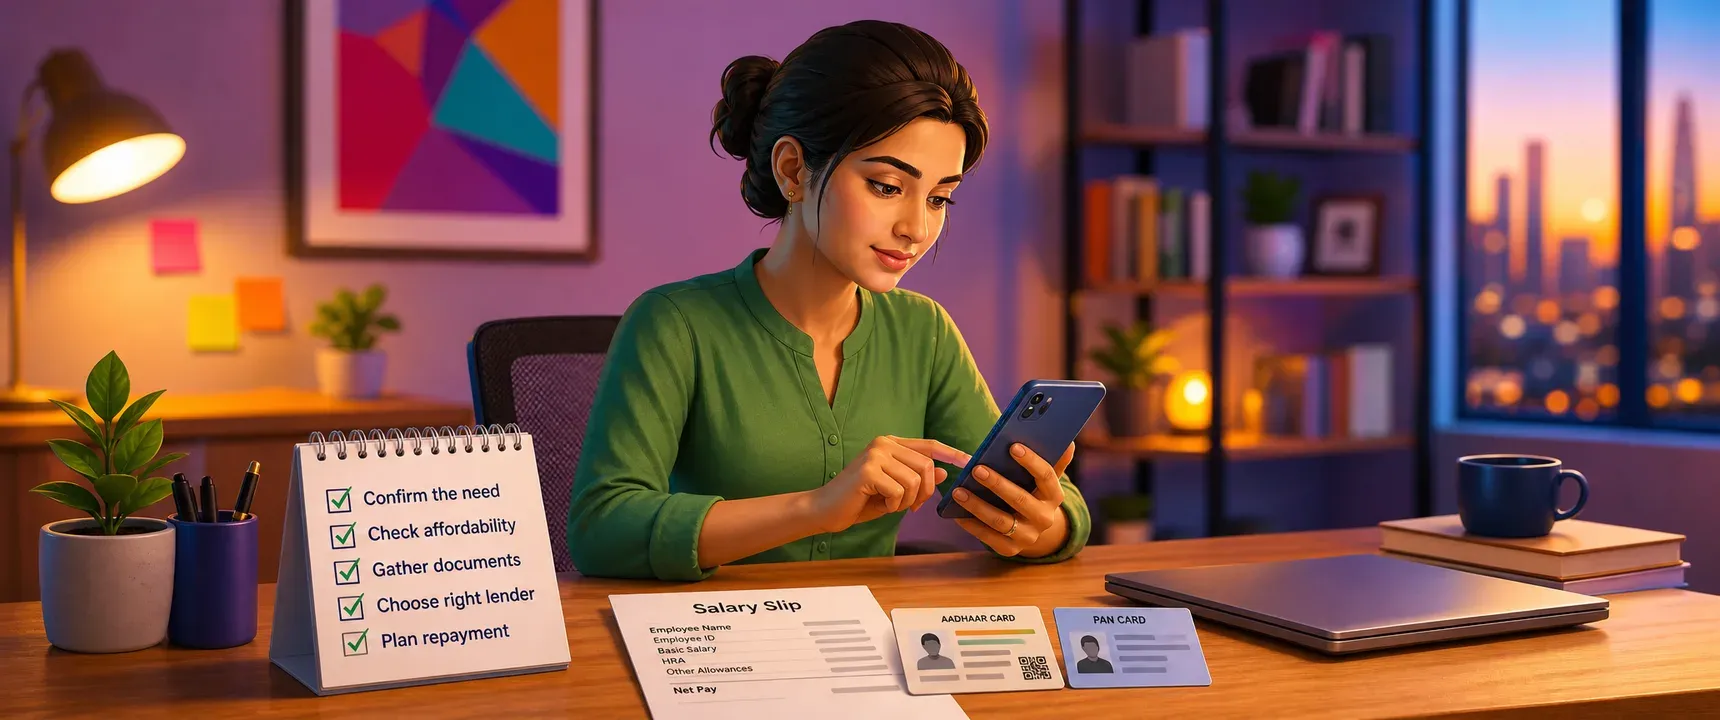
Table of content
Fresher loan decision checklist for first salary, no credit history
Why freshers face a unique borrowing gap
The fresher loan decision checklist
How no credit history approval works
Building credit with your first loan
Mistakes freshers should avoid
FAQs
You just received your first salary credit. Maybe you relocated for a new job, need a laptop, or have a security deposit due next week. The money is real, but it is not enough yet. And when you search for a personal loan, every lender seems to want a credit history you have not had time to build. mPokket created this fresher loan decision checklist so early career borrowers can assess readiness, compare options honestly, and borrow in a way that starts their credit journey on solid ground.
Follow our Whatsapp Community for more offers and updates.
Join nowTraditional banks score applicants on repayment history, credit utilization, and account age. A fresher has none of these. The result is a catch 22: you need credit to build a score, but you need a score to get credit.
Digital lending platforms changed this equation. Lenders like mPokket can evaluate alternative signals such as salary account activity, employment verification, and KYC documents. This alternative data based approval process means a first time borrower loan is no longer impossible.
Still, approval alone is not the goal. The real question is whether borrowing right now is the smartest move for your finances. That is what this checklist helps you decide.
Work through each checkpoint before you apply. Skipping even one can turn a helpful loan into a stressful obligation.
Separate genuine needs from wants. Relocation deposits, work devices, professional clothing, and medical bills qualify as needs that cannot wait. A vacation or gadget upgrade usually can.
Ask yourself: will delaying this expense cost me more than the interest on a loan? If yes, borrowing makes sense. If no, saving for two or three pay cycles is cheaper.
Your starting salary sets a hard ceiling on what you can repay each month. A common guideline is to keep total EMI obligations below 30% of net monthly income. On a starting salary of Rs 20,000, that means your EMI should stay under Rs 6,000.
Use a personal loan EMI calculator to test different amounts and tenures before you commit. mPokket lets borrowers choose flexible EMI schedules, which can help align repayment with your paycheck timing.
| Decision criterion | Green (go ahead) | Yellow (proceed with caution) | Red (wait or reduce amount) |
|---|---|---|---|
| Purpose of loan | Essential setup cost (deposit, device, relocation) | Semi urgent (upskilling course, minor repair) | Discretionary (vacation, lifestyle upgrade) |
| EMI to salary ratio | Below 20% | 20% to 30% | Above 30% |
| Emergency buffer after EMI | At least one month of expenses saved | Partial buffer, tight but manageable | Zero savings left after EMI |
| Repayment tenure clarity | Loan fully repaid within 3 to 6 months | 6 to 12 months, still comfortable | Tenure stretches beyond comfort zone |
| Lender reports to credit bureau | Yes, confirmed | Unclear, need to verify | No bureau reporting (no credit building benefit) |
Paperless loan platforms keep document requirements minimal. For mPokket, the typical checklist includes Aadhaar card, PAN card, a verified bank account, and proof of occupation or income. OTP based digital KYC replaces branch visits entirely.
Having these ready before you open the app saves time and avoids incomplete applications that stall approval.
Not every loan app reports repayment data to credit bureaus. If your goal is to build credit history early, confirm that the lender shares your repayment record with CIBIL or another recognized bureau.
mPokket is designed to help first time borrowers establish a formal credit profile. Each on time repayment contributes to your emerging score, which matters when you apply for larger loans or credit cards later.
Decide your repayment method on day one. Options typically include UPI repayment, debit card payment, or autopay EMI. Setting up autopay loan repayment can help you avoid missed EMI penalties and protect the credit score you are trying to build.
mPokket offers in app repayment and autopay options so borrowers can manage due dates without manual effort each month.
Early career borrowers often need funds for specific, time sensitive costs. Here are scenarios where a small personal loan for freshers makes practical sense.
Relocation deposits come first. Moving to a new city for work usually requires a rental deposit, broker fee, and basic furnishing. These costs hit before your first full paycheck arrives.
Work devices are another common need. Many employers expect you to have your own laptop or smartphone. A loan that covers this cost and gets repaid in three to four EMIs is often more practical than waiting months to save.
Professional upskilling also qualifies. If a certification or short course directly improves your earning potential, borrowing a small amount now can pay for itself through higher income within a year.
When a fresher applies on a platform like mPokket, the system does not reject the application simply because no CIBIL score exists. Instead, the platform uses alternative assessment methods.
These can include verifying your bank account activity, confirming employment or college enrollment, and completing digital KYC through Aadhaar and PAN verification. The entire process is designed to be 100 percent online, with approval possible within minutes.
This approach is part of a broader shift in digital lending in India. The Reserve Bank of India (RBI) has issued guidelines for digital lending that require transparency, direct bank account disbursal, and clear disclosure of loan terms through a Key Fact Statement. Borrowers should always review this statement before accepting any loan offer.
Your first loan is not just about the money. It is your entry point into the formal credit system. Here is how to make it count.
Borrow only what you need. A smaller loan repaid on time looks better on your credit profile than a larger loan where you struggle with EMIs.
Never miss a due date. Even one late payment can lower a new credit score significantly. Autopay and due date reminders inside the mPokket app are designed to help prevent this.
Keep the tenure short. Repaying quickly demonstrates disciplined borrowing and repayment behavior, which is exactly what future lenders want to see.
After your first loan is fully repaid, your CIBIL profile will reflect a completed account with a positive repayment track record. This single data point can make your next borrowing experience faster and cheaper.
Borrowing from multiple apps at once splits your repayment capacity and confuses your credit profile. Stick to one lender for your first loan.
Ignoring the total repayment cost is another trap. Always check the interest rate, processing fees, and total repayment amount before accepting. The EMI calculator and Key Fact Statement exist for this reason.
Borrowing for someone else is risky when you are still establishing your own financial footing. Your credit score reflects your repayment behavior, not your intentions.
If you land in the "red" zone on more than one row of the decision matrix above, the responsible choice is to wait. A loan you cannot comfortably repay does more harm than the expense it was meant to cover.
Freshers who use this checklist before applying through mPokket or any other platform put themselves in a stronger position. They borrow with clarity, repay with confidence, and walk away with a credit history that opens doors for years to come. The first loan is small. The decision behind it is not.
Yes. Digital lenders like mPokket use alternative data assessment, including bank account verification and Aadhaar plus PAN KYC, to approve first time borrowers who have no existing credit score or CIBIL history.
Freshers typically need an Aadhaar card, PAN card, a verified bank account, and proof of occupation or income. The entire KYC process is digital and paperless, with no branch visit required.
Loan amounts for freshers depend on income and the lender's assessment. mPokket is designed to offer personal loans suited to early career borrowers, with amounts calibrated to starting salary levels and repayment capacity.
Yes, provided the lender reports repayment data to a credit bureau. On time repayment of a loan through mPokket can help establish a positive credit profile that benefits future borrowing.
Financial guidance suggests keeping total EMI obligations below 30% of net monthly income. For freshers on a starting salary, staying closer to 20% leaves a healthier buffer for unexpected expenses.
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
Need ₹10,000 Urgent Loan Today — What Should You Do To Get It Fast?
4 min read • 30 April 2026
How to Choose the Right Digital Lending Platform: A Comparison Guide for 2026
4 min read • 12 May 2026
