4 mins min read • 19 October 2026


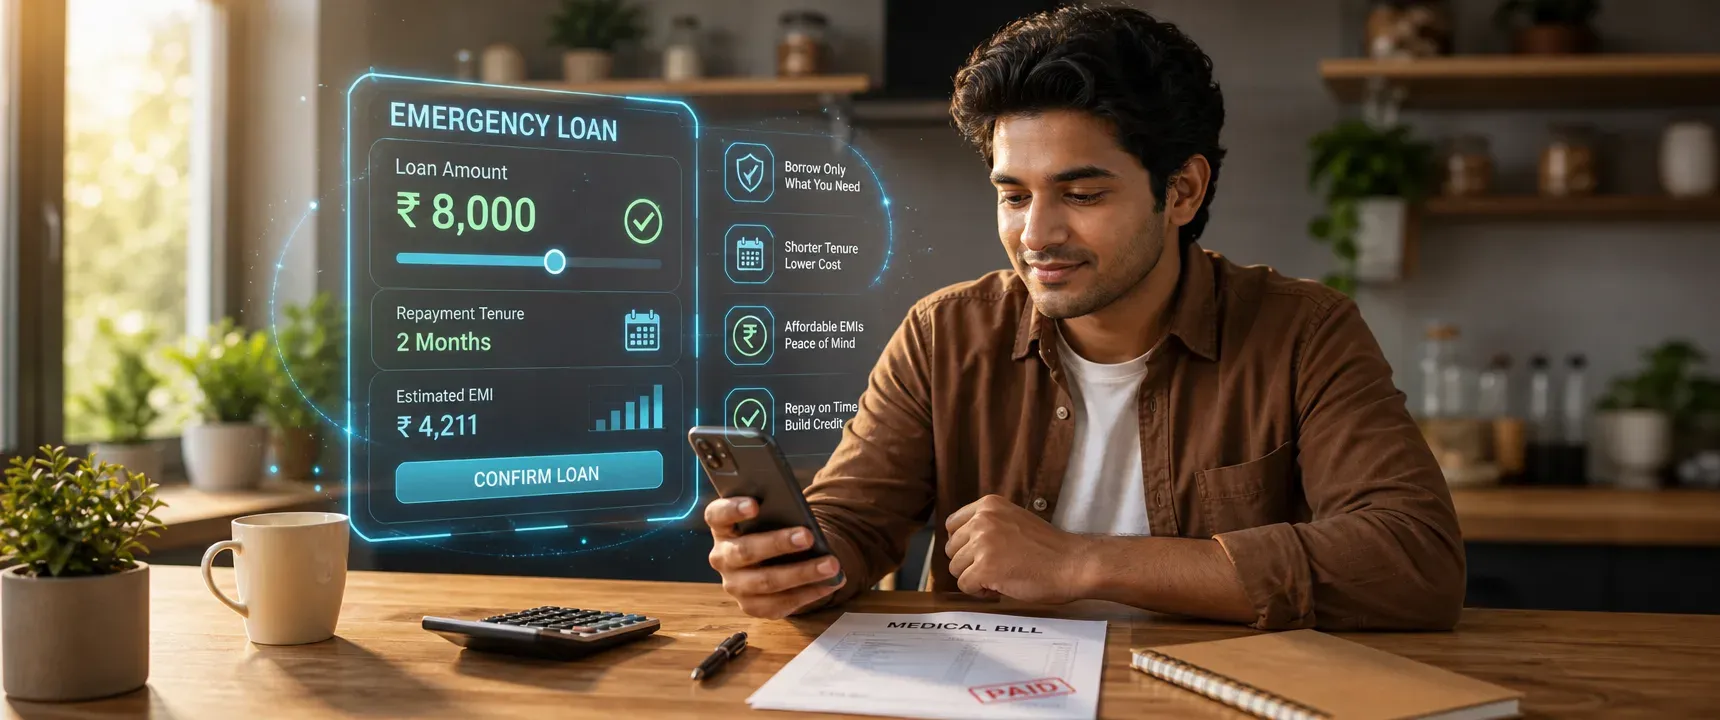
Table of content
Summary
Why urgency distorts borrowing decisions
Smaller amounts reduce real cost
Shorter tenures build discipline
The maximum eligibility trap
How to decide the right amount
Emergency borrowing for different profiles
Repayment as part of the plan
FAQs
Why borrow less in emergencies? - Borrowing only the amount you need reduces your total interest cost and keeps monthly EMI payments manageable. Smaller loans are easier to repay on time, which protects your credit profile and prevents a debt spiral.
What is a shorter repayment plan? - A shorter tenure means you clear the debt in fewer months, pay less total interest, and free up your budget sooner. mPokket offers flexible tenure options so borrowers can match repayment to their actual cash flow.
How does this differ from maximum eligibility borrowing? - Many lenders market the highest amount you qualify for. Borrowing at maximum eligibility increases EMI burden and default risk. Disciplined borrowers choose the minimum amount that solves the immediate problem.
Who benefits most from this approach? - Salaried employees facing month end cash crunches, freshers on starting salaries, gig workers with irregular income, and housewives managing household emergencies all benefit from controlled, smaller emergency loans through platforms like mPokket.
What makes mPokket different here? - mPokket is designed to support borrowers with flexible repayment options, a paperless digital process, and transparent loan terms. The platform encourages responsible borrowing rather than pushing maximum loan amounts.
Follow our Whatsapp Community for more offers and updates.
Join nowFinancial emergencies compress decision making into minutes. When a hospital asks for a deposit or a landlord demands overdue rent, the brain shifts into survival mode. Rational comparison of loan amounts, tenures, and interest rates feels impossible under that pressure.
This is exactly why so many borrowers end up with more debt than they needed. They see a pre approved limit, accept the full amount, and choose the longest tenure available. The immediate crisis gets solved, but a new problem begins: months of stretched repayment that eats into regular expenses like groceries, transport, and utilities.
mPokket's approach to emergency lending is built around a simple principle. The loan should match the problem, not the eligibility. A borrower who needs Rs 8,000 for a medical bill does not benefit from withdrawing Rs 50,000 simply because the app allows it.
Interest on a personal loan accumulates on the principal. When you borrow Rs 10,000 instead of Rs 30,000, you pay interest on a much smaller base. Over a three month tenure, that difference can translate into hundreds of rupees saved.
Consider a practical scenario. A salaried employee earning Rs 20,000 per month faces an unexpected vehicle repair costing Rs 7,000. If she borrows exactly Rs 7,000 with a short tenure, her EMI stays well within 10 to 15 percent of her monthly income. If she borrows Rs 25,000 because the app shows that as her limit, the EMI jumps to a level that forces her to cut essential spending or risk missing a payment.
mPokket's digital lending platform can help borrowers see their estimated monthly EMI before confirming the loan amount. This transparency is designed to encourage borrowers to adjust the amount downward until the EMI fits comfortably within their monthly budget.
A common misconception is that longer tenures are always safer because the EMI is smaller. While a lower EMI feels easier each month, the total repayment over a longer period is higher. More importantly, a long tenure keeps the borrower in debt for months after the emergency has passed.
Shorter repayment plans create a clear finish line. A borrower who takes a two month tenure knows exactly when the obligation ends. That certainty reduces financial anxiety and frees up future income for savings or planned expenses.
For gig workers, freelancers, and delivery partners whose earnings fluctuate weekly, a shorter tenure also limits exposure to income volatility. A three month loan carries more risk of a missed EMI during a slow earning week than a one month loan does.
mPokket offers flexible repayment options, including the ability to repay via UPI or set up autopay for EMI. These features are designed to make shorter tenures practical, not just aspirational.
Digital lending platforms often highlight the maximum amount a borrower qualifies for. This is a marketing convention, not financial advice. Eligibility reflects what a lender is willing to offer based on your profile. It does not reflect what you can comfortably repay alongside your existing obligations.
Borrowing at maximum eligibility is especially risky for first time borrowers, freshers on starting salaries, and housewives managing household budgets. These groups often have thin or no credit histories, which means a single missed EMI can disproportionately damage their credit profile.
mPokket's platform is designed to support first time borrowers and individuals without extensive credit histories. By encouraging smaller, manageable loans, the platform can help users build a positive repayment record over time. On time repayment of even a small emergency loan contributes to credit history building, which improves future borrowing options.
Before opening any loan app during an emergency, take sixty seconds to answer three questions. First, what is the exact rupee amount needed to solve this specific problem? Second, can any portion be covered from existing savings or by delaying a non essential expense? Third, what EMI can you afford without skipping meals, rent, or other fixed costs?
This exercise sounds simple, but it is the single most effective guard against overborrowing. Most emergencies have a defined cost. A medical bill is a specific number. A repair invoice is a specific number. Borrowing beyond that number does not make the emergency smaller; it only makes the repayment larger.
mPokket's personal loan EMI calculator can help borrowers estimate their monthly obligation before they commit. Adjusting the loan amount and tenure in the calculator reveals how small changes in either variable affect the total cost of borrowing.
The principle of smaller amounts and shorter plans applies across borrower types, but the specifics vary.
Salaried employees facing a month end cash crunch before payday may need only a few thousand rupees to bridge the gap. An advance salary loan or a short term personal loan from mPokket can help cover next paycheck expenses without locking the borrower into months of repayment.
Freshers and interns on stipend income often encounter sudden expenses during internship or their first job. A small, short tenure loan can help manage the gap without creating a debt burden that outlasts the internship itself.
Housewives managing household emergencies, whether medical bills, home repairs, or kids education expenses, benefit from borrowing only the deficit after accounting for household savings. mPokket can help housewives access small loans without collateral through a paperless, 100 percent online process.
Gig workers and freelancers with irregular cash flow face a unique challenge. Their income next month is uncertain, so a shorter repayment plan reduces the risk of a missed EMI during a low earning period. mPokket's flexible repayment options are designed to accommodate variable income patterns.
Smart emergency borrowing does not end when the funds hit your bank account. The repayment plan is part of the emergency response. Setting up autopay for EMI through mPokket can help ensure you never miss a due date, which protects your credit profile and avoids late payment consequences.
Borrowers who repay on time also position themselves for better terms on future loans. Disciplined borrowing and repayment is a long term financial strategy, not just a short term fix. Each successful repayment cycle builds trust with the lender and strengthens the borrower's credit building journey.
mPokket supports multiple online repayment methods, including UPI loan repayment and debit card repayment, making it convenient to stay on schedule regardless of which payment method the borrower prefers.
Emergency loans do not have to become long term burdens. The next time an unexpected expense appears, consider borrowing less, repaying sooner, and using a platform like mPokket that is designed to support responsible, borrower first decisions. That single shift in approach can mean the difference between solving a crisis and creating a new one.
mPokket is designed to offer instant personal loans through a paperless, 100 percent online process. Borrowers can apply using Aadhaar and PAN for digital KYC, and funds are transferred directly to a verified bank account after approval, which can help cover urgent medical bills quickly.
Calculate the exact amount needed for the specific emergency. Use a personal loan EMI calculator to check whether the monthly instalment fits your budget. Borrow only that amount, choose the shortest comfortable tenure, and set up autopay to avoid missed payments.
Yes. mPokket offers unsecured personal loans that do not require collateral or a guarantor. Eligibility is assessed through digital verification and alternative data, making it accessible to salaried employees, freshers, gig workers, and housewives.
Borrow only the gap between your current funds and the expense. Choose a short tenure that aligns with your next salary date. Platforms like mPokket offer advance salary loans and flexible repayment options designed for short term, pre payday borrowing needs.
Yes. On time repayment of even a small loan contributes to credit history building. For first time borrowers and freshers without a credit score, a small, responsibly repaid loan through mPokket can help establish a positive credit profile for future borrowing.
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
What Is an NBFC Loan and How Does It Work?
3 July 2026
₹1,000 Instant Loan: Why Can the Amount Credited Be Lower Than the Sanctioned Amount?
3 min read • 11 October 2026
10 money management tips you can take to the bank
2 min read • 6 December 2024