4 mins min read • 15 October 2026


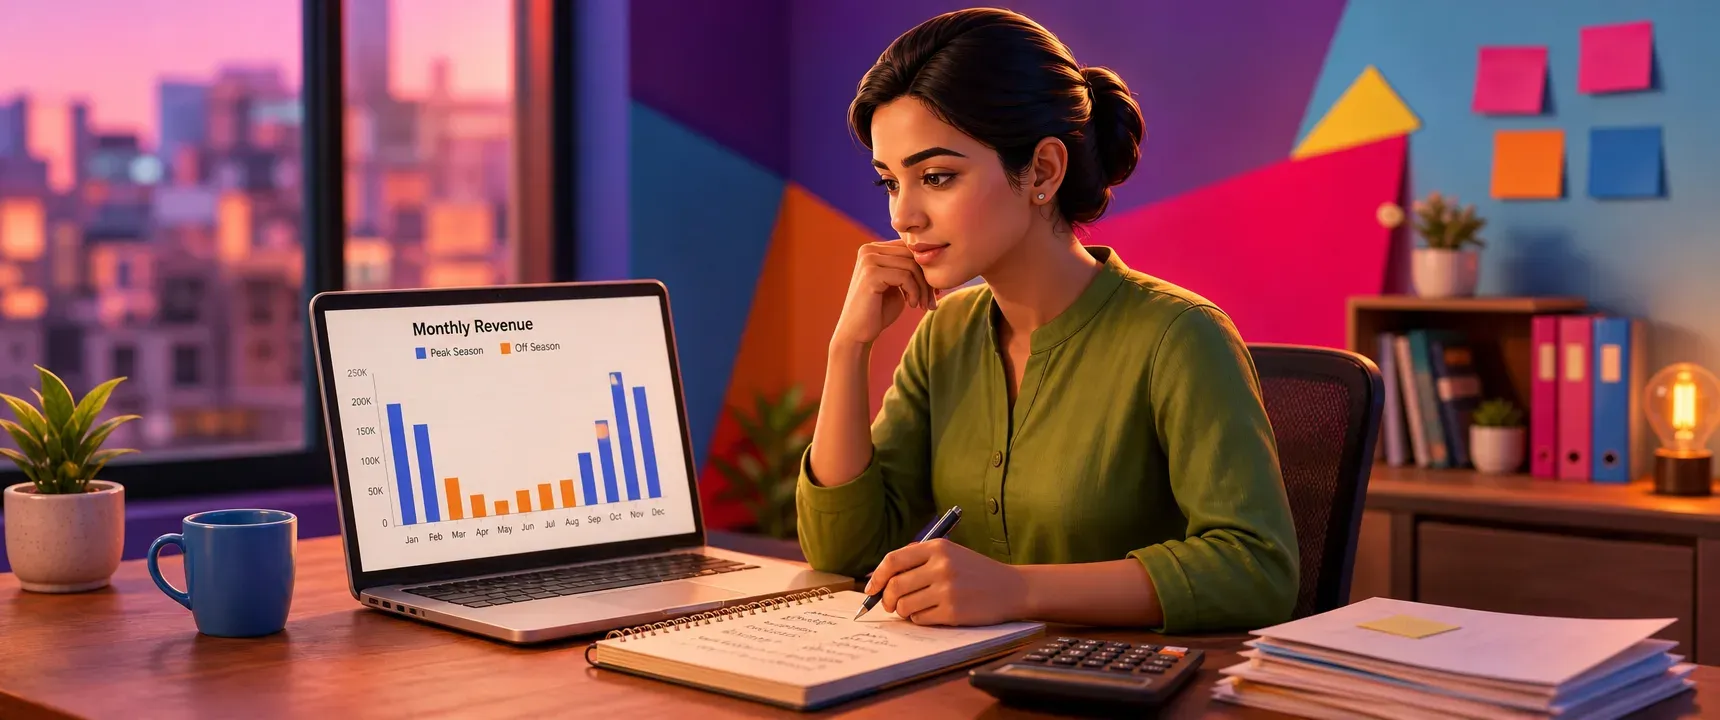
Table of content
Overview
Why standard EMI math fails seasonal businesses
The seasonal EMI safety framework
Decision matrix for seasonal borrowers
How to stress test before you borrow
Building a repayment buffer
What lenders look for in seasonal applications
When a working capital loan fits better
FAQs
A garment trader in Surat earns 60% of annual revenue between September and January. A beach shack owner in Goa collects almost nothing from June through September. For businesses like these, a fixed monthly EMI can feel manageable during peak months and suffocating during lean ones. mPokket believes that responsible borrowing starts with stress testing your EMI against your weakest earning months, not your strongest. This guide walks seasonal business owners through a practical framework for estimating whether a business loan EMI is genuinely safe.
Follow our Whatsapp Community for more offers and updates.
Join nowMost business loan EMI calculators divide total repayment evenly across months. They assume your revenue is roughly the same each month. That assumption works for a salaried professional. It does not work for a retailer whose Diwali season sales are five times higher than July sales.
Consider a small fireworks retailer in Tamil Nadu. Annual revenue might be Rs 12 lakh, suggesting Rs 1 lakh per month on average. A business loan EMI calculator might show that an EMI of Rs 18,000 is comfortable at that income level. But if eight months of the year bring in only Rs 40,000 to Rs 60,000 each, that Rs 18,000 EMI suddenly consumes 30% to 45% of monthly revenue. Add rent, inventory holding costs, and wages, and the retailer faces a genuine repayment crisis.
mPokket encourages seasonal business owners to move beyond average income calculations. The real question is not whether you can afford the EMI in a good month. It is whether you can afford it in your worst month without cutting into essential operating expenses.
This framework helps traders, retailers, and cyclical small enterprises estimate safe borrowing limits. It uses three inputs you already have: your bank statements, your monthly fixed costs, and your proposed loan terms.
Pull 12 months of bank account credits. Exclude any one time windfalls like asset sales or personal transfers. Sort the remaining months from lowest to highest. Your revenue floor is the average of the three lowest months.
For example, if your three weakest months brought in Rs 35,000, Rs 42,000, and Rs 38,000, your revenue floor is Rs 38,333.
List every expense you must pay regardless of sales volume. This typically includes rent, utility bills, minimum staff wages, insurance premiums, and any existing loan EMIs. Total these for one month.
Suppose your fixed costs are Rs 22,000 per month. That leaves Rs 16,333 of your revenue floor available for new obligations and personal needs.
Divide your proposed new EMI by your revenue floor. mPokket recommends keeping this ratio at or below 0.25 for seasonal businesses. A ratio between 0.25 and 0.30 is borderline. Anything above 0.30 signals danger.
| Seasonal EMI safety ratio | Risk level | Recommended action |
|---|---|---|
| Below 0.20 | Low risk | EMI is likely safe even in weak months |
| 0.20 to 0.25 | Moderate risk | Safe if you maintain a one month cash reserve |
| 0.25 to 0.30 | Elevated risk | Consider reducing loan amount or extending tenure |
| Above 0.30 | High risk | EMI is likely unsafe; restructure before borrowing |
Using the example above, if the proposed EMI is Rs 8,000 and the revenue floor is Rs 38,333, the ratio is 0.21. That falls in the moderate risk zone, manageable with a small cash buffer.
Different seasonal patterns call for different borrowing strategies. The matrix below maps common Indian business cycles to EMI planning considerations.
| Business type | Peak season | Off season months | EMI planning tip |
|---|---|---|---|
| Festival goods retailer | Sep to Jan | Feb to Aug | Build a 3 month EMI reserve during peak sales |
| Agricultural trader | Harvest months (varies by crop) | Pre harvest and monsoon | Align loan disbursal with pre harvest inventory needs |
| Tourism and hospitality | Oct to Mar (varies by region) | Monsoon months | Choose shorter tenure to clear debt before next off season |
| School supplies retailer | Apr to Jun, Dec to Jan | Jul to Nov | Split borrowing into two smaller loans timed to each peak |
| Wedding services provider | Nov to Feb, Apr to Jun | Jul to Oct, Mar | Use flexible repayment to pay more during wedding season |
This matrix is not exhaustive. The principle is consistent: map your cash flow peaks and valleys before committing to a fixed monthly obligation.
A stress test simulates what happens if your off season is worse than usual. Seasonal businesses face weather disruptions, delayed harvests, regulatory changes, or simply a slow festival season. Your EMI plan should survive a 20% revenue drop in your weakest quarter.
Take your revenue floor from Step 1 and reduce it by 20%. Recalculate the safety ratio with this stressed figure. If the ratio stays below 0.30, your EMI plan has reasonable resilience. If it crosses 0.30, you are borrowing too aggressively for your cash flow pattern.
mPokket's business loan EMI calculator can help you model different loan amounts and tenures quickly. By adjusting the principal amount and tenure selection, you can find a combination where the EMI stays within your stressed revenue capacity.
Seasonal businesses that borrow responsibly often set aside a portion of peak season earnings into a dedicated repayment buffer. A practical target is three months of EMI payments saved before the off season begins. This buffer acts as a financial safety net, preventing missed EMI payments and protecting your credit profile.
Lenders evaluate repayment history when you apply for future credit. On time repayment during lean months signals disciplined borrowing and strengthens your business credit profile for larger loans later.
Digital lenders like mPokket assess seasonal businesses differently from salaried applicants. Understanding what they evaluate can help you present a stronger application.
Bank statements showing 12 months of transaction history are essential. They reveal your revenue cycle, average balances, and spending patterns. GST returns, if applicable, provide independent confirmation of seasonal sales volumes. Udyam registration or other MSME documentation establishes your business vintage and formal status.
Some digital lenders use alternative data assessment methods. They may consider transaction frequency, vendor payment regularity, and digital payment volumes alongside traditional income proof. mPokket's digital lending process is designed to accommodate borrowers whose income does not follow a straight monthly pattern.
Not every seasonal funding need requires a term loan with fixed EMI. A working capital loan can be a better fit when you need short term funds for inventory restocking before a peak season and expect to repay quickly once sales begin.
Working capital loans for small businesses typically have shorter tenures and are designed to bridge cash flow gaps. If your need is specifically to stock inventory for Diwali, a harvest season, or a tourism rush, a working capital loan aligned to that cycle may carry lower total interest cost than a longer term business loan.
mPokket offers collateral free business loan options that seasonal enterprises can evaluate alongside traditional term loans. The key comparison point is total repayment cost relative to the revenue the borrowed funds are expected to generate.
Seasonal business owners who approach borrowing with a clear cash flow map, a conservative EMI safety ratio, and a repayment buffer are far less likely to face repayment stress. mPokket's digital lending tools, including the business loan EMI calculator and flexible repayment options, are designed to support exactly this kind of careful, informed decision making. Before you commit to any EMI, run the stress test. Your weakest month, not your best one, should determine how much you borrow.
Find your average revenue for the three weakest months of the year. Your EMI should not exceed 25% of that figure. mPokket recommends stress testing by reducing that floor by 20% and checking whether the EMI ratio stays below 0.30.
Yes. Use a business loan EMI calculator to model different loan amounts and tenures. Then compare the resulting EMI against your off season revenue floor rather than your annual average. mPokket's calculator can help you adjust tenure and principal to find a safe combination.
Seasonal businesses should look for collateral free business loans with flexible repayment options and digital application processes. mPokket offers instant business loan options with paperless KYC and quick disbursal, designed to accommodate borrowers with variable income patterns.
A working capital loan suits short term, cycle specific needs like pre season inventory. A term business loan suits longer investments like equipment. Seasonal businesses should compare total repayment cost and tenure alignment with their revenue cycle before choosing.
Typically you need 12 months of bank statements, PAN and Aadhaar for KYC, Udyam or MSME registration, and GST returns if applicable. These documents help lenders like mPokket understand your seasonal revenue pattern and assess repayment capacity accurately.
Which app gives loan without credit score in India
3 mins min read • 18 September 2026
What Are the Best Options for Instant Financial Assistance?
2 min read • 5 June 2026
Does Udyam Registration Improve MSME Loan Eligibility?
2 min read • 10 September 2026
How Does GST Return Filing History Affect Business Loan Eligibility?
4 min read • 15 September 2026
