4 mins min read • 29 September 2026


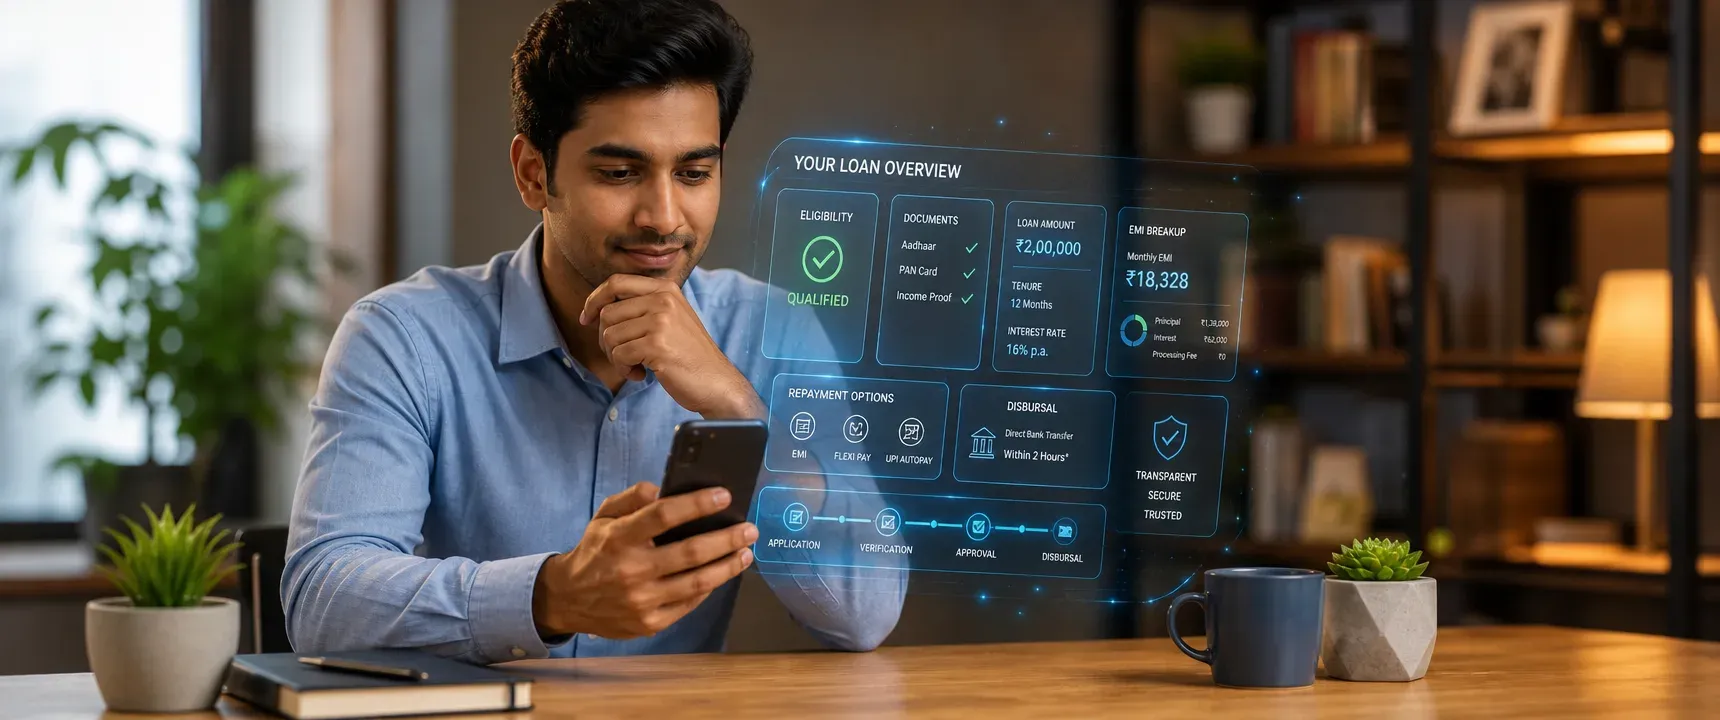
Table of content
Indian borrowers expect instant clarity more than instant marketing in 2026
Speed is table stakes now
Clarity on eligibility changes everything
Documents should not be a mystery
Repayment clarity builds confidence
Disbursal transparency matters too
Every borrower segment deserves answers
Trust as a product standard
What borrowers should demand
FAQs
Every loan app in India promises speed. Approvals in minutes, disbursal in hours, paperless everything. Yet the borrower sitting on the other side of that screen often has a different question: "Do I actually qualify, and what happens next?" mPokket believes that the next wave of digital lending in India will not be won by the fastest marketing claim. It will be won by the clearest borrowing experience.
Follow our Whatsapp Community for more offers and updates.
Join nowIndia's digital lending ecosystem has matured rapidly. According to the Reserve Bank of India's guidelines on digital lending (RBI, 2022), regulated entities must disclose all loan terms upfront. The regulatory direction is clear: borrowers deserve full information before they commit.
Most instant loan apps already offer quick approval and paperless applications. A borrower comparing five apps will find similar speed claims on each. What separates one experience from another is no longer how fast the app says it is. It is how well the app prepares the borrower for what comes next.
mPokket recognizes this shift. When a salaried employee, a fresher starting a first job, or a housewife exploring a home business loan opens the app, the first question is rarely "how fast?" It is "do I qualify, and what do I need?"
Consider a freelancer with project-based income. Traditional eligibility checks rely on salary slips and CIBIL scores. Digital lenders that use alternative data assessment can serve borrowers without conventional credit histories. But the borrower needs to know this before applying.
A clear eligibility explanation should answer several questions upfront. What income proof does the app accept? Can someone without a credit score still apply? Is Aadhaar and PAN verification sufficient for digital KYC? Does the app serve gig workers, delivery partners, or interns on stipend income?
mPokket's approach is designed to address these questions early. By stating eligibility criteria for each borrower segment, whether salaried employees, self-employed professionals, or homemakers, the app can help reduce the anxiety that comes with applying and getting rejected without explanation.
One of the most common frustrations in digital lending is discovering halfway through an application that you need a document you do not have. A paperless loan process should mean fewer documents, not hidden ones.
A responsible instant loan app lists exact requirements before the borrower begins. For personal loans, this typically means Aadhaar card, PAN card, and proof of income. For business loans, it may include GST registration, Udyam certificate, or bank statements. mPokket's digital application process is designed to make these requirements visible from the start, so borrowers can gather what they need before they tap "apply."
This small act of transparency saves time on both sides. The borrower avoids repeated attempts. The lender avoids incomplete applications. Everyone moves faster because the process was clear, not because someone cut corners.
Borrowers in India face a wide range of repayment structures. EMI loans, flexi personal loans, lump sum repayment, UPI autopay, debit card payments. Each option suits a different financial situation. A gig worker with variable weekly income needs a different repayment rhythm than a salaried employee with a fixed monthly paycheck.
The problem is not a lack of options. It is a lack of explanation. When a borrower does not understand how EMI is calculated, what flexible repayment actually means, or whether autopay can be cancelled, they borrow with uncertainty. That uncertainty erodes trust.
mPokket's EMI calculator and repayment guidance are designed to help borrowers see the total cost before they commit. Knowing the principal amount, interest rate, tenure, and estimated monthly EMI in advance lets a borrower decide whether the loan fits their monthly budget. This is not a feature to advertise. It is a responsibility to fulfill.
"Instant disbursal" is one of the most common phrases in Indian loan app marketing. But what does "instant" mean? Five minutes? Two hours? Next business day? The answer varies, and borrowers deserve specifics.
A direct bank transfer loan should clearly state when funds will reach the borrower's verified bank account after approval. If there are conditions, like banking hours or verification steps, those should be visible. mPokket's process is designed to provide this clarity, so a borrower waiting for emergency funds or month-end cash support knows exactly what to expect.
When someone needs money for a medical bill, an unexpected repair, or inventory restocking for a small shop, vague promises create stress. Specific timelines create confidence.
India's borrower base is extraordinarily diverse. A personal loan for salaried employees involves different documentation than a small loan for a housewife starting a tiffin service. A startup business loan has different eligibility criteria than a working capital loan for an established MSME.
The best instant loan apps do not treat all borrowers the same. They provide segment-specific guidance. mPokket serves multiple borrower profiles, including freshers, women, self-employed professionals, gig workers, freelancers, and small business owners. Each profile has distinct needs around collateral (or the lack of it), income proof formats, and repayment flexibility.
A collateral-free business loan applicant wants to know whether their business vintage and turnover qualify them. A fresher wants to know whether a first salary or internship stipend counts as income. A homemaker wants to know whether alternative income assessment is available. Answering these questions clearly is not just good UX. It is the product itself.
In a crowded market of instant loan apps, trust is the hardest thing to build and the easiest thing to lose. RBI's digital lending guidelines (RBI, 2022) mandate that borrowers receive a key fact statement with all loan terms before disbursal. This regulatory baseline exists because the industry needed it.
mPokket's position is that compliance is the floor, not the ceiling. Clarity should extend beyond regulatory requirements into every interaction: the eligibility check, the document upload, the EMI selection, the repayment reminder, and the disbursal confirmation. When a borrower feels informed at every step, they are more likely to repay on time, borrow responsibly, and return when they need funds again.
This is not about slowing down the process. A loan can be both fast and clear. Speed without clarity is just noise. Clarity with speed is a lending experience that respects the borrower.
Indian borrowers searching for the best quick loan app or the best paperless loan app with instant approval should evaluate more than speed. Before choosing any instant loan app, consider whether it answers these questions without making you dig through fine print.
Does the app state eligibility for your specific situation, whether you are salaried, self-employed, a fresher, or a homemaker? Does it list the exact documents needed, such as Aadhaar, PAN, and income proof? Does it show your EMI calculation before you accept the loan? Does it explain when and how funds reach your bank account? Does it offer flexible repayment options like UPI, autopay, or custom EMI tenure?
If the answer to any of these is unclear, the app is optimizing for its own conversion rate, not for your confidence. mPokket is designed to put these answers in front of borrowers before they commit, because informed borrowers make better financial decisions.
The next chapter of digital lending in India belongs to platforms that treat clarity as a product standard. Borrowers who demand transparency will find that the best instant loan apps are not just the fastest ones. They are the ones that help you understand exactly what you are signing up for, every single time.
mPokket is designed to offer instant personal loans in India with a paperless digital process. The app provides eligibility checks, Aadhaar and PAN based KYC, and direct bank transfer after approval, with clear upfront information on documents, EMI, and repayment options.
Check whether the app clearly states eligibility criteria for your profile, lists required documents like Aadhaar and PAN, shows EMI calculations before you accept, explains disbursal timelines, and offers flexible repayment through UPI or autopay.
The best paperless loan apps provide a fully digital application with Aadhaar and PAN verification, transparent loan terms, and quick disbursal. mPokket is designed to deliver this experience with upfront clarity on eligibility, documents, and repayment structure.
Some digital lenders, including mPokket, are designed to use alternative data assessment for borrowers without a formal credit history. Freshers, interns, and first-time borrowers can potentially qualify based on income proof and digital KYC verification.
mPokket is designed to show eligibility criteria, required documents, EMI calculations, and disbursal timelines before a borrower commits. This approach helps borrowers across segments, from salaried employees to housewives, make informed decisions.
Which is the best loan app in India?
3 mins min read • 21 September 2026
The growing role of alternative borrower signals in India's digital credit market
3 mins min read • 20 September 2026
Flexi Loan Meaning and How It Works: A Complete Guide
4 min read • 4 August 2026
What Is a Fully Digital Loan Application Process? Steps, Documents & Approval Timeline
4 min read • 11 May 2026
