4 mins min read • 14 October 2026


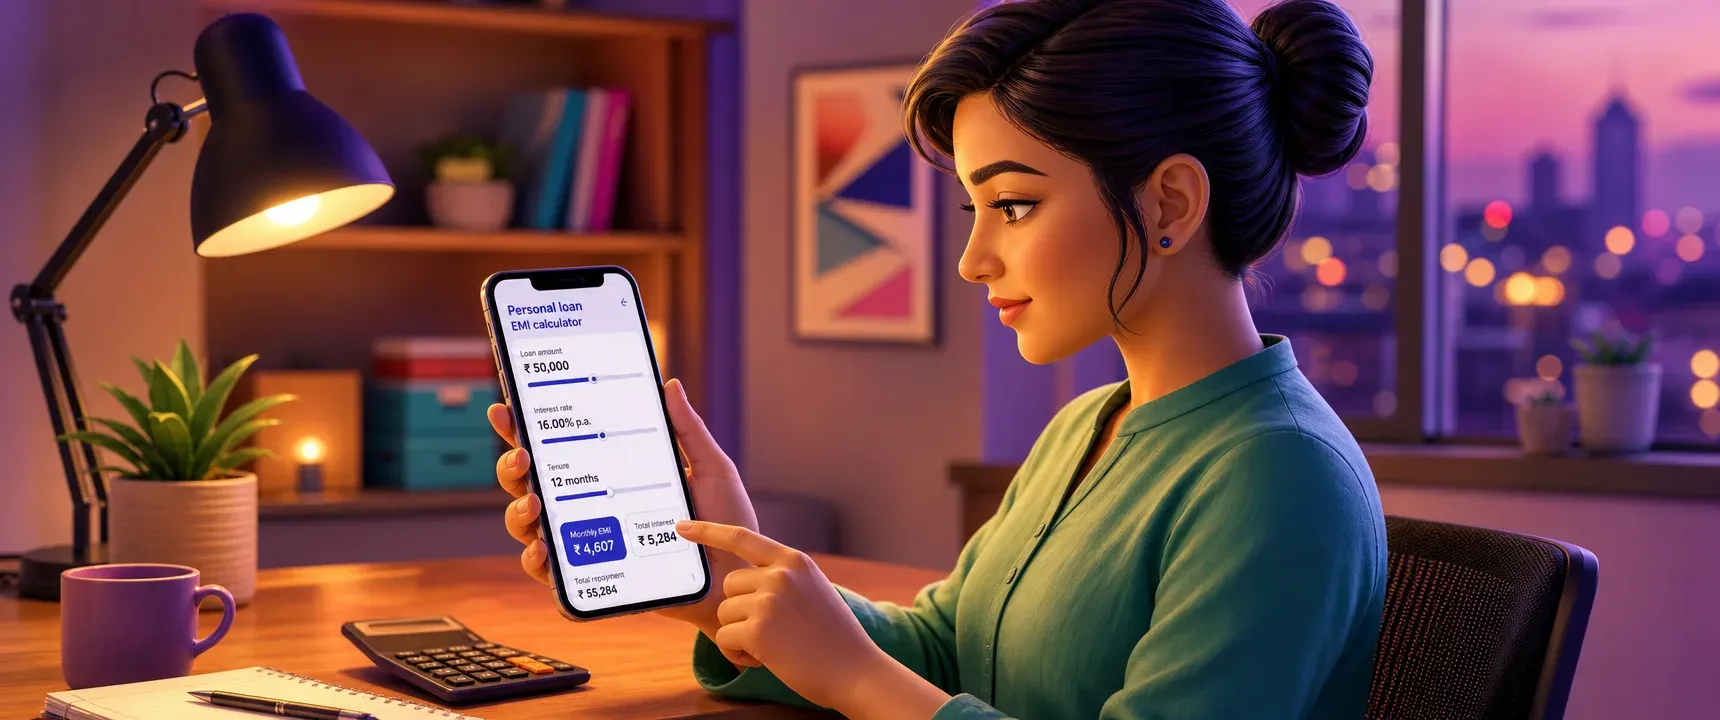
Table of content
Overview
Why tenure matters more than you think
How to calculate personal loan EMI online
What changes EMI more: tenure or interest rate?
A simple framework for choosing tenure
Common mistakes to avoid
FAQs
Picking the wrong repayment tenure on a personal loan can quietly drain your budget for months. A shorter tenure means higher monthly payments that squeeze your cash flow. A longer tenure keeps EMIs low but inflates total interest. Before you submit your application on mPokket or any digital lending platform, understanding this tradeoff is designed to help you borrow responsibly and repay comfortably.
Follow our Whatsapp Community for more offers and updates.
Join nowMost borrowers focus on the loan amount and approval speed. Tenure, however, determines two things that shape your financial comfort for months: the EMI you pay each month and the total cost of borrowing.
Consider a simple example. On a personal loan of Rs 50,000 at a given interest rate, a 3 month tenure produces a high EMI but minimal total interest. Stretch that to 12 months and each EMI drops significantly, but the cumulative interest rises. Neither option is universally better. The right choice depends on your monthly budget and how much extra cost you are willing to accept for breathing room.
A personal loan EMI calculator is a tool that takes three inputs: loan amount (principal), interest rate, and tenure in months. It applies the standard reducing balance formula to show your estimated monthly instalment and total repayment.
Here is how to use one effectively before submitting your application on mPokket or any digital lending platform.
Enter your loan amount. Start with the exact sum you need, not the maximum you qualify for. Borrowing only what is necessary keeps both EMI and total interest lower.
Try multiple tenures. Run the calculator at least three times with different tenure values. Compare the EMI column and the total repayment column side by side.
Check your monthly surplus. Subtract rent, groceries, utilities, and other fixed costs from your take home income. The leftover amount is your repayment capacity. Your EMI should sit comfortably within it.
Pick the tenure that balances both numbers. Choose the shortest tenure whose EMI still leaves you a cash buffer for unexpected expenses like medical bills or home repairs.
This process takes under five minutes and can save you from months of repayment stress. mPokket is designed to support this kind of informed decision making through transparent loan terms and flexible repayment options.
Tenure has a larger practical impact on your EMI than small differences in interest rate. Doubling the tenure roughly halves the EMI, while a one or two percentage point rate change shifts it by a smaller margin. That is why choosing tenure carefully matters even more than negotiating a slightly lower rate.
For salaried employees with predictable monthly income, a moderate tenure often works well. Freshers on a starting salary may prefer a slightly longer tenure to keep EMIs manageable while they build savings. Self employed borrowers or freelancers with irregular cash flow can benefit from flexible repayment plans that let them adjust payments when earnings fluctuate.
Use this three step approach before you finalize your application.
First, calculate your debt affordability ratio. Financial planners generally suggest that total EMI obligations should not exceed 30 to 40 percent of your monthly income. If you already have other EMIs, subtract those first.
Second, define your repayment goal. If you want to minimize total cost, lean toward a shorter tenure. If you want to protect monthly cash flow, lean longer. Neither goal is wrong; the key is choosing deliberately.
Third, stress test the EMI. Ask yourself whether you could still pay it if your income dipped for a month or an unplanned expense appeared. If the answer is no, extend the tenure by one or two months and recalculate.
mPokket's flexible repayment loan structure is designed to help borrowers align tenure with real life cash flow, whether you are a salaried professional, a gig worker, or a housewife managing household finances.
Choosing the maximum tenure by default is a frequent error. It feels safe because the EMI looks small, but you end up paying noticeably more in total interest. Another mistake is picking the shortest tenure without budgeting for emergencies. One missed EMI can hurt your credit profile and trigger late fees.
A third pitfall is ignoring the EMI calculator entirely. Many borrowers accept whatever tenure the app suggests without comparing alternatives. Spending a few minutes with a personal loan EMI calculator before submitting your application on mPokket can reveal a better option that saves money and reduces stress.
Responsible borrowing starts before the application, not after disbursal. By choosing a tenure that fits your income, expenses, and financial goals, you set yourself up for on time repayment and a stronger credit history over time.
Enter your loan amount, interest rate, and preferred tenure into a personal loan EMI calculator. The tool applies the reducing balance formula and shows your estimated monthly instalment along with total repayment. mPokket is designed to display transparent loan terms so you can verify these numbers before applying.
A personal loan EMI calculator is an online tool that estimates your monthly instalment based on principal amount, interest rate, and tenure in months. It helps you compare different tenure options and choose one that fits your monthly budget before submitting a loan application.
Yes. A longer tenure reduces each monthly EMI but increases the total interest paid over the loan's life. A shorter tenure raises the EMI but lowers total cost. Using an EMI calculator to compare both outcomes can help you find the right balance for your cash flow.
Financial planners generally recommend keeping total EMI obligations within 30 to 40 percent of your monthly income. Before choosing a tenure on mPokket or any lender, subtract existing EMIs and fixed expenses from your income to determine a comfortable repayment amount.
How to Choose the Right Digital Lending Platform: A Comparison Guide for 2026
4 min read • 12 May 2026
Best practices for first time borrowers using loan apps in India
5 min read • 11 September 2026
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
