4 mins min read • 31 October 2026


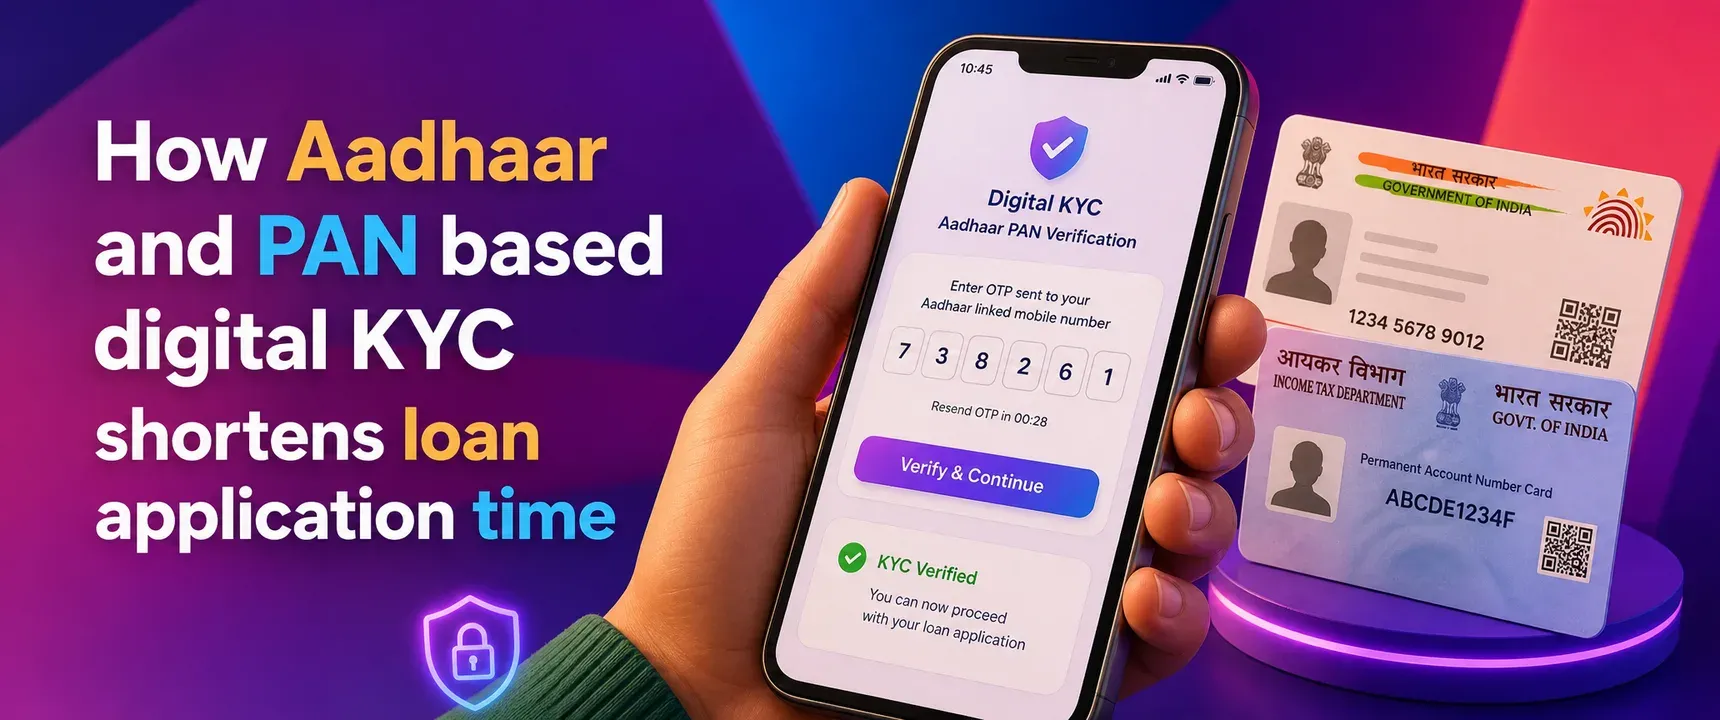
Table of content
How Aadhaar and PAN based digital KYC shortens loan application time
Why traditional KYC slows loans
How Aadhaar and PAN replace paperwork
From KYC to disbursal in minutes
Who benefits most?
Compliance and borrower safety
Beyond approval: repayment readiness
FAQs
Waiting days for a loan decision feels outdated when your rent is due tomorrow. For borrowers across India, the gap between needing money and actually receiving it has historically been filled with photocopies, branch queues, and manual document checks. mPokket compresses that gap by using Aadhaar and PAN based digital KYC to verify identity in minutes, not days, turning a paperless loan application into funds credited directly to a verified bank account.
Follow our Whatsapp Community for more offers and updates.
Join nowA conventional loan application at a bank branch involves submitting identity proof, address proof, income documents, and sometimes utility bills. Each document is manually checked by an officer. Errors or missing pages mean a return visit.
This process can stretch across two to five working days. For someone facing a medical bill, a month end cash crunch, or an unexpected repair, that timeline defeats the purpose of borrowing. The bottleneck is not the lending decision itself; it is the identity verification layer sitting before it.
Aadhaar is India's biometric identity system managed by UIDAI, covering over a billion residents. PAN is issued by the Income Tax Department and links financial transactions to an individual. Together, they form a reliable digital identity pair.
When a borrower applies on mPokket, the app requests the Aadhaar number and PAN details. The Aadhaar number triggers an OTP sent to the registered mobile number. Once the borrower enters that OTP, the system validates identity against the UIDAI database electronically. PAN verification cross references the applicant's tax identity. No paper changes hands.
This OTP based digital KYC process eliminates three friction points at once: the need for physical documents, the need for a branch visit, and the need for manual officer review. The entire check can complete in under two minutes within the app.
Speed in digital lending is not just about one fast step. It is about removing delays across the entire journey. Here is how the mPokket process is designed to flow after digital KYC clears.
| Step | What happens | Estimated time |
|---|---|---|
| App download and registration | Borrower registers with mobile number | Under 1 minute |
| Profile completion | Basic details, occupation, income proof upload | 2 to 3 minutes |
| Aadhaar PAN digital KYC | OTP based verification against UIDAI and PAN databases | Under 2 minutes |
| Credit assessment | Alternative data based evaluation of repayment capacity | Automated |
| Approval and Key Fact Statement | Loan terms displayed transparently | Within 7 minutes total |
| Direct bank transfer | Funds sent to verified bank account | After approval |
The seven minute approval window that mPokket is designed to offer becomes possible because digital KYC removes the single longest manual step in the traditional process. Without it, even a fully digital app would stall at identity verification.
Digital KYC with Aadhaar and PAN is particularly valuable for borrowers who lack access to traditional banking infrastructure or who cannot afford time away from work for branch visits.
Freshers entering their first job often have no credit history. Salaried employees facing a month end cash crunch need funds before their next paycheck. Self employed professionals, freelancers, gig workers, and housewives running home based ventures may not have conventional salary slips. For all these segments, the ability to verify identity digitally through Aadhaar and PAN means the loan application does not require documents they may not possess.
mPokket's paperless loan process is designed to serve borrowers who are new to formal credit. By accepting Aadhaar and PAN as the primary KYC documents, the platform can help first time borrowers access a compliant digital borrowing journey without the barriers that physical documentation creates.
A common concern among first time digital borrowers is whether sharing Aadhaar and PAN online is safe. The RBI's digital lending guidelines require that all KYC data be handled through secure, encrypted channels. OTP based Aadhaar verification ensures that only the account holder, with access to the registered mobile number, can authorize the check.
mPokket displays a Key Fact Statement before disbursal, showing the loan amount, interest rate, tenure, and total repayment obligation. This transparency is part of the RBI's framework for responsible digital lending. Borrowers see exactly what they owe before accepting the loan.
Sharing Aadhaar and PAN with an RBI compliant digital lender is not the same as sharing it with an unverified source. Borrowers should always confirm that the lending app follows RBI guidelines before submitting identity details.
Fast KYC also accelerates repayment setup. Because the borrower's bank account is verified during the application process, mPokket can offer direct bank transfer of loan funds and convenient repayment options including UPI, debit card, and autopay EMI.
Autopay loan repayment, once enabled, helps borrowers avoid missed EMI due dates. This is especially useful for salaried employees and working professionals whose income arrives on a fixed schedule. Setting up autopay during the same digital session as the loan application means the borrower is fully set up, from KYC to repayment, in a single sitting.
For borrowers looking to build credit history, on time repayment of a digitally disbursed loan can contribute to establishing a formal credit profile. This makes the first loan experience on mPokket not just a short term solution but a potential step toward broader financial access.
If you need a quick loan and have your Aadhaar and PAN card ready, mPokket's digital KYC process is designed to move you from application to approval without paperwork or branch visits. The combination of OTP based verification, alternative data assessment, and direct bank transfer creates a borrowing experience built for speed and compliance.
Yes. On mPokket, Aadhaar and PAN are the primary KYC documents required for a paperless loan application. OTP based Aadhaar verification and PAN validation replace physical document submission, enabling a fully digital process.
mPokket requires a valid Aadhaar card, a PAN card, and access to the mobile number linked to your Aadhaar for OTP verification. Depending on your profile, proof of occupation or income may also be needed. No physical photocopies are required.
Loan apps like mPokket use digital KYC through Aadhaar and PAN to verify identity electronically. Combined with automated credit assessment using alternative data, this can help compress the approval process to as few as seven minutes, with funds transferred directly to a verified bank account.
When processed through an RBI compliant digital lender like mPokket, Aadhaar and PAN data is handled through secure, encrypted channels. OTP based verification ensures only the account holder can authorize the identity check. Always verify that a lending app follows RBI digital lending guidelines before sharing documents.
How to Choose the Right Digital Lending Platform: A Comparison Guide for 2026
4 min read • 12 May 2026
What Is a Key Facts Statement (KFS) in an Online Business Loan?
2 min read • 10 September 2026
How First-Time Borrowers Can Build Credit History in India (Step-by-Step Guide)
5 min read • 6 May 2026
Need ₹10,000 Urgent Loan Today — What Should You Do To Get It Fast?
4 min read • 30 April 2026