3 mins min read • 22 September 2026


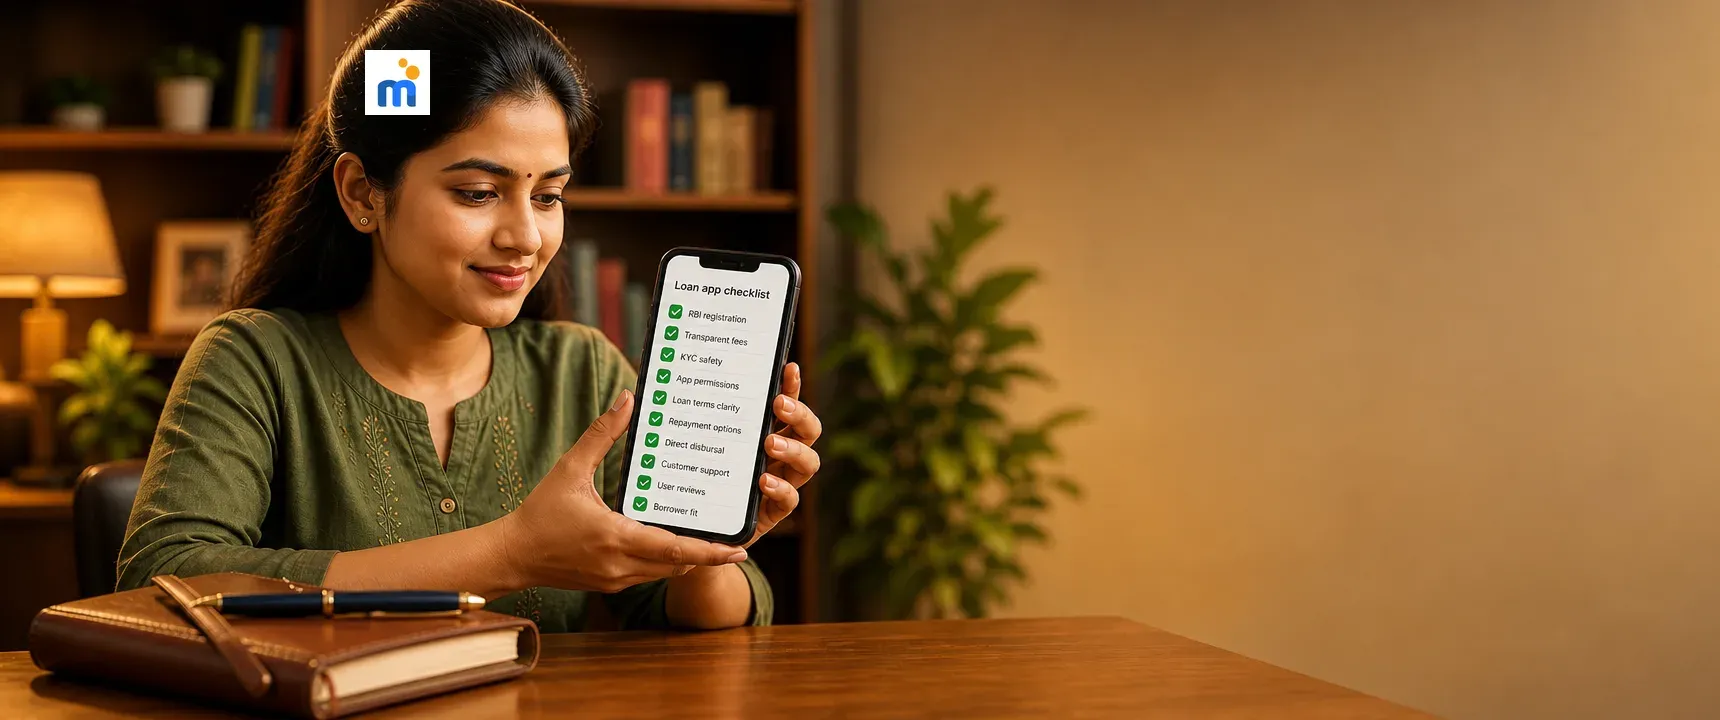
Table of content
Overview
Why a checklist matters
The 10 point checklist
Decision matrix for scoring
How digital lending works in India
Applying the checklist responsibly
FAQs
Downloading a loan app takes seconds. Sharing your Aadhaar, PAN, and bank details with the wrong one can cost you months of stress. In India, hundreds of apps promise instant loans, but not all of them are transparent about fees, licensed to lend, or built to protect your data. mPokket believes borrowers deserve a structured way to evaluate any loan app before they tap "apply." This 10 point checklist gives you that framework.
Follow our Whatsapp Community for more offers and updates.
Join nowSpeed sells. Loan apps in India compete on approval time, sometimes promising funds in minutes. That urgency can push borrowers to skip basic checks. A structured evaluation method slows the decision just enough to catch red flags.
Digital lending in India operates under RBI guidelines that require every lending app to be linked to a registered NBFC or bank. Yet predatory apps still surface on app stores. They collect excessive permissions, charge hidden processing fees, and sometimes harass borrowers during recovery.
A checklist converts vague caution into concrete action. Instead of wondering whether an app "feels" trustworthy, you verify ten specific things. mPokket recommends this approach because informed borrowers make better repayment decisions and build healthier credit profiles.
Every legitimate loan app in India must operate through an RBI registered NBFC or bank. Check the app's website or Play Store listing for the partner entity's name. Then verify that entity on the RBI's official NBFC list. If no partner is disclosed, treat that as a disqualifying signal.
Before you apply, the app should clearly display the annual interest rate range, processing fee, late payment penalty, and any other charges. Vague language like "low interest" without a number is a warning. mPokket, for example, discloses its fee structure upfront so borrowers can calculate total repayment cost before proceeding.
A trustworthy app uses OTP based digital KYC with Aadhaar and PAN verification. It should not ask you to share documents over WhatsApp or email. Check the app's privacy policy for data retention and sharing clauses. Legitimate digital lending platforms use encrypted verification, not manual document collection through informal channels.
Install the app but review its permission requests before granting access. A loan app reasonably needs camera access for selfie verification and storage access for document upload. It does not need access to your contacts list, call logs, or gallery. Excessive permissions often signal aggressive recovery practices or data harvesting.
The app should state the minimum and maximum loan amounts, available tenure options, and whether you can choose your repayment schedule. Ambiguity here means you may end up locked into terms you did not expect. Look for apps that let you select tenure and see the corresponding EMI before you submit documents.
Check whether the app supports multiple repayment modes: UPI, debit card, autopay, or in app payment. Flexible repayment matters especially for borrowers with variable income, such as freelancers, gig workers, or self employed professionals. mPokket supports UPI repayment and autopay, giving borrowers control over how and when they pay.
Legitimate apps transfer funds directly to your verified bank account. Be cautious of apps that disburse through wallets, vouchers, or third party accounts. Direct bank transfer ensures you receive usable funds and creates a clear transaction trail. Confirm the expected disbursal timeline as well; most credible apps specify this clearly.
Test the app's support channels before you apply. Send a query through in app chat, email, or the listed phone number. If you receive no response within 24 hours, reconsider. Borrowers need accessible support for repayment issues, account queries, and dispute resolution. An app without responsive support is a risk during your loan tenure.
Read recent reviews on the Google Play Store or Apple App Store. Focus on patterns rather than individual complaints. Repeated mentions of hidden charges, harassment during collection, or unauthorized debits are serious red flags. A few negative reviews among thousands may be normal, but a pattern of similar grievances is not.
The app should clearly state who can apply: students, salaried employees, self employed individuals, housewives, or gig workers. It should also list eligibility criteria such as minimum age, income type, and required documents. mPokket, for instance, serves students, salaried users, and self employed borrowers, and states eligibility requirements before the application begins. If an app does not tell you whether you qualify until after you share your data, that is a concern.
Use this table to score any loan app you are considering. Rate each criterion from 1 (poor or absent) to 5 (excellent). A total score below 30 suggests the app needs further scrutiny or should be avoided.
| Criterion | What to verify | |
|---|---|---|
| RBI registration | NBFC partner named and verifiable on RBI list | |
| Fee transparency | Interest rate, processing fee, and penalties disclosed before application | |
| KYC safety | OTP based digital KYC with Aadhaar and PAN; encrypted process | |
| App permissions | Only essential permissions requested; no contacts or call log access | |
| Loan terms clarity | Amount range, tenure options, and EMI visible before document submission | |
| Repayment flexibility | Multiple modes (UPI, autopay, debit card); flexible schedule options | |
| Disbursal method | Direct transfer to verified bank account; timeline stated | |
| Customer support | Responsive in app chat, email, or phone within 24 hours | |
| User reviews | No repeated patterns of hidden charges, harassment, or unauthorized debits | |
| Borrower fit | Eligibility criteria and target segments stated clearly before application |
Understanding the broader process helps you evaluate individual apps more critically. Digital lending in India follows a regulated flow. An app collects your basic details and documents through a digital interface. KYC verification happens electronically using Aadhaar and PAN. The lending NBFC or bank partner underwrites the loan based on your profile, income signals, and sometimes alternative data like UPI transaction history.
Once approved, funds are transferred directly to your bank account. Repayment happens through the app via EMI, UPI, autopay, or lump sum options depending on the product. The entire journey, from application to disbursal, can happen without a branch visit. mPokket operates within this framework, offering a paperless process with direct bank transfer after approval.
This digital model benefits borrowers who need speed and convenience. But it also means your personal data moves through digital systems, which is exactly why the checklist above matters. Verifying an app's legitimacy and data practices before you apply is the single most important step in responsible digital borrowing.
Start by listing two or three loan apps you are considering. Run each through the 10 point checklist and fill in the scoring matrix. Compare total scores. If one app scores significantly higher, that is your stronger option.
For first time borrowers, this process also builds financial literacy. You learn what to expect from a legitimate lender, what fees are standard, and what practices are unacceptable. mPokket encourages this kind of informed evaluation because borrowers who understand their loan terms are more likely to repay on time and build positive credit history.
If you are a student, salaried employee, freelancer, gig worker, or self employed professional evaluating a loan app in India, this checklist gives you a repeatable framework. Use it every time you consider a new app. The few minutes it takes can save you from hidden fees, data misuse, or predatory lending practices.
The best loan app depends on your borrower profile and needs. Use a structured checklist covering RBI registration, fee transparency, KYC safety, repayment flexibility, and borrower fit to compare options. mPokket scores well on these criteria for students, salaried employees, and self employed borrowers.
Digital lending in India involves applying through an app, completing electronic KYC with Aadhaar and PAN, receiving underwriting from an RBI registered NBFC or bank partner, and getting funds transferred directly to your bank account. The entire process is paperless and branchless.
Loan apps linked to RBI registered NBFCs and following transparent practices are generally safe. Verify the NBFC partnership, check app permissions, read user reviews for complaint patterns, and confirm that disbursal goes directly to your bank account before applying.
Verify RBI registration, fee disclosure, KYC method, app permissions, repayment options, disbursal method, customer support responsiveness, user reviews, and whether the app clearly states eligibility criteria for your borrower segment.
Yes. Check the app store listing for NBFC partner details, review the privacy policy, test customer support, and read user reviews before creating an account or uploading documents. A credible app discloses key terms before requiring your data.
How mPokket serves borrowers with limited or no prior credit history
3 mins min read • 20 September 2026
What should you compare before choosing a loan app in India for urgent needs?
3 mins min read • 21 September 2026
What does no credit score mean in a digital loan app
2 mins min read • 20 September 2026
Can You Cancel a Business Loan After Sanction but Before Disbursement?
3 min read • 18 September 2026
