4 min read • 12 October 2026


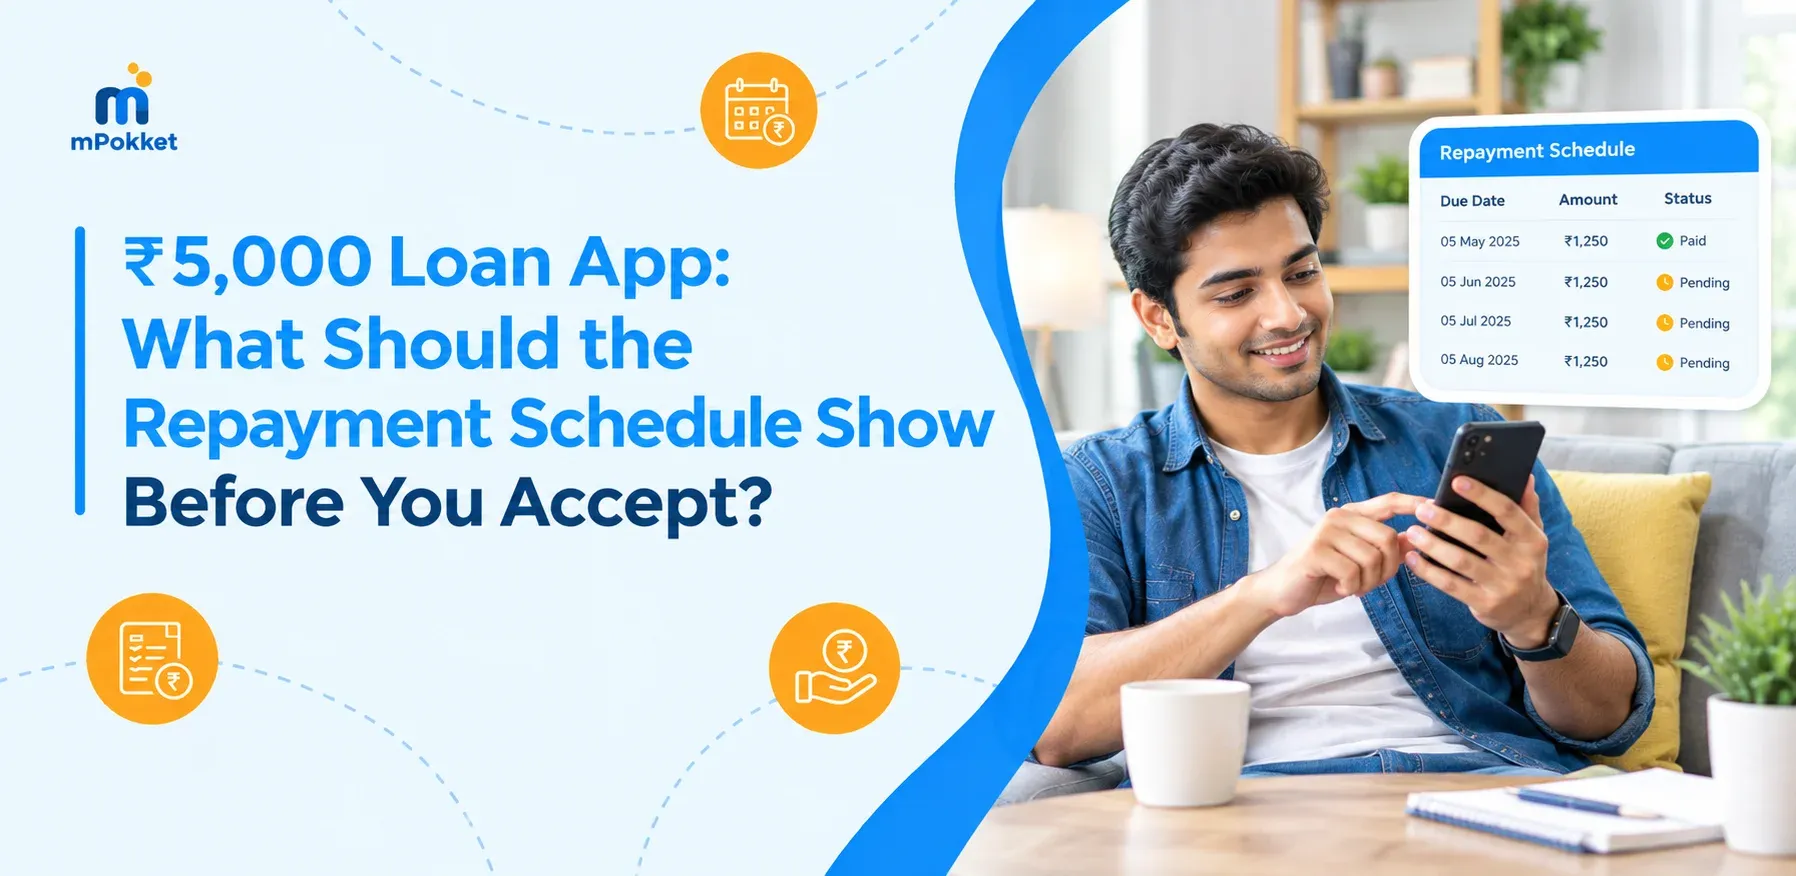
Table of content
Overview
What Is a ₹5,000 Loan App?
What Details Should a ₹5,000 Loan Repayment Schedule Include?
How Does an Instant 5000 Loan Repayment Schedule Work?
What Should You Check Before Accepting a Rs. 5000 Personal Loan Offer?
How to Compare Different Loan App for 5000 Options?
Which Small Amount Loan App Needs Minimal Documentation for a 5000 Personal Loan?
Conclusion
Frequently Asked Questions
A 5000 personal loan is a small, unsecured loan taken through an app and repaid on fixed dates. Before you accept, the schedule should show every due date, each installment, interest, fees and the total payable.
It’s late, a bill is due, and the app says “Approved.” One button says Continue. Nobody shows you the due dates. That’s where small borrowers usually get caught, and it’s rarely the amount that hurts. It’s the fee or the deadline they never saw. A 5000 personal loan looks harmless, but a short deadline or a surprise charge can make it feel heavy fast.
This guide explains what the repayment schedule must show, how an instant 5000 loan really works, and how to size up any small amount loan app calmly. We’ve added RBI rules and mPokket as one example, so you can verify everything yourself.
Follow our Whatsapp Community for more offers and updates.
Join nowA loan app for 5000 lets you borrow a small sum digitally, with no collateral and no branch visit. Most work through regulated lenders. Here’s who tends to use them and what mPokket offers.
Who uses a small amount loan app?
Students, freshers, gig workers and small shop owners, mostly. They need a short bridge until salary or customer payments arrive, not a long commitment. A small amount loan app suits that gap.
What does mPokket offer?
mPokket was founded in 2016 in Kolkata and began with small loans for students and young earners. It works with NBFC lending partners. Its site also lists self-employed people and business owners as borrowers. Limits and rates change, so trust your own offer screen.
It should show each due date, the amount due, the interest and fee split, and your total payback. Missing any of these? Pause. The table below is your checklist.
What is a Key Fact Statement?
RBI requires lenders to share a Key Fact Statement before the contract is signed. It covers APR, recovery process, grievance officer and cooling off period. Ask for it. Always.
You pick an amount and tenure, the app splits repayment into dates, and installments are collected from your linked account. Shorter tenure means less interest. Here’s a simple example.
What does a sample schedule look like?
This is illustrative only, at 2% a month on the reducing balance. These are not mPokket’s actual rates.
You’d repay about ₹5,200, plus any processing fee.
Can you exit early?
During the cooling off period you can leave a digital loan by returning the principal and proportionate interest without penalty, though a reasonable one time processing fee may apply.
Check who the lender is, the APR, every fee and the due dates. Then see whether the app is properly listed. A few quick checks follow.
Is an instant 5000 loan safe to take?
It can be, when the lender is regulated, shows APR upfront and asks only for permissions it truly needs. If an app pressures you to hurry, close it.
To compare loan apps for a ₹5,000 loan, you should evaluate the Annual Percentage Rate (APR) to understand the true total payable from each offer. Check processing fees, compare repayment tenures for flexibility, and verify the platform's RBI registration for safety.
Most digital lenders ask for eKYC, a selfie and bank details, and little else. Less paperwork doesn’t mean fewer checks, so decide on terms, not convenience.
mPokket says customers need no physical documents or branch visits. Moneyview also describes a paperless process, so several apps fit. Compare them fairly, then pick the one whose schedule you understand best.
A 5000 personal loan should never feel confusing. Ask for the full schedule, read the Key Fact Statement, and borrow only what you can repay on time. If every number makes sense, go ahead. If not, walk away.
Open the mPokket app, view your offer and review the repayment schedule before you accept.
1. What should I check in a ₹5,000 loan repayment schedule?
Due dates, installment amount, interest, processing fee, GST, late charges and total payable. Confirm prepayment terms too.
2. Is an instant ₹5,000 loan safe to take?
Yes, if the lender is regulated, discloses APR upfront and sends money to your own account. Avoid apps that rush you.
3. What is a small amount loan app?
It’s a mobile app that gives small, short term loans, often a few thousand rupees, without collateral or branch visits.
4. Can I get a 5000 personal loan online?
Yes. Many apps approve it digitally after eKYC and bank verification. Approval depends on your profile and the lender’s policy.
5. Why is reviewing loan terms important before acceptance?
Fees, penalties and short deadlines raise the real cost. Reading terms first helps you avoid surprises and repay comfortably.
₹5,000 Cash Loan: Which Fees Can Reduce the Amount You Receive?
4 min read • 11 September 2026
Which Is The Most Trusted Loan App In India?
4 min read • 1 May 2026
Step-by-Step Guide: How To Apply For mPokket Personal Loan
7 min read • 27 May 2026
