3 mins min read • 22 October 2026


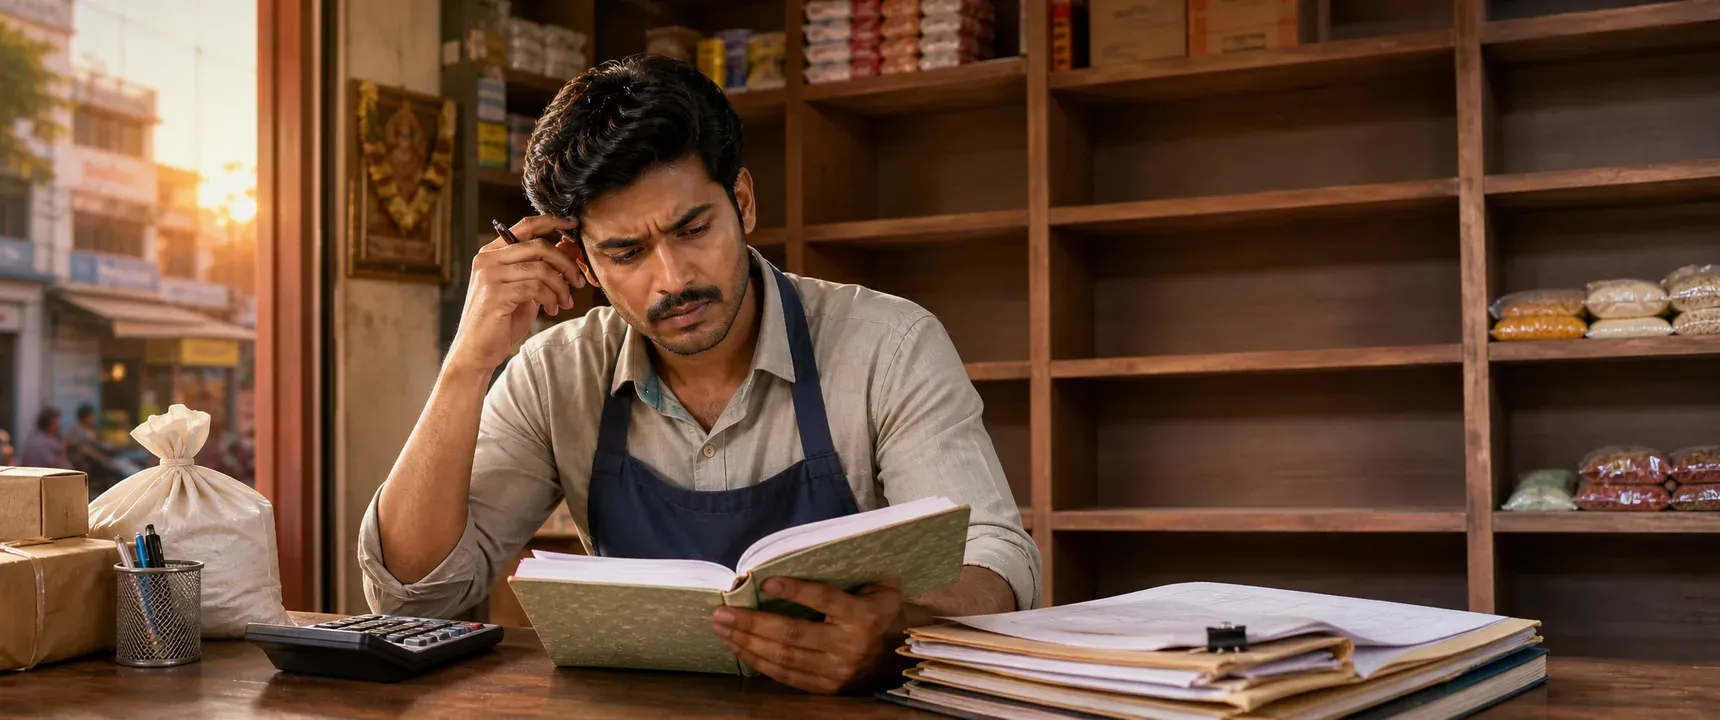
Table of content
When business funding delays start affecting inventory, salaries, or vendor trust
Why funding delays snowball
Warning signs in inventory
Salary delays and team morale
Vendor trust takes years to build
Recognizing the tipping point
How working capital loans help
FAQs
A delayed payment from a client or a slow loan disbursement might seem like a minor inconvenience. For an Indian MSME owner, though, that gap between needing funds and receiving them can cascade into empty shelves, anxious employees, and suppliers who stop picking up the phone. mPokket recognizes that these operational symptoms often signal a deeper working capital problem, one that a fast, paperless business loan or working capital loan can help address before lasting damage sets in.
Follow our Whatsapp Community for more offers and updates.
Join nowMost Indian MSMEs operate on thin margins. A single delayed receivable or a slow bank loan sanction can set off a chain reaction. The business owner postpones a raw material order. Production slows. Deliveries slip. Customers complain or leave.
The core issue is timing. Revenue and expenses rarely align perfectly. Seasonal demand spikes, festival inventory buildup, and bulk vendor payments all create moments when cash outflow exceeds inflow. Without a working capital loan or instant business loan to bridge the gap, these moments turn into crises.
Small business owners often absorb the first few shocks by dipping into personal savings or borrowing informally. Neither approach is sustainable. Personal savings deplete quickly, and informal borrowing carries unpredictable costs. A structured working capital loan from a digital lender like mPokket can help provide a more reliable safety net.
Inventory disruption is usually the first visible symptom of a funding delay. Here are the warning signs every small business owner should watch for.
Frequent stockouts on fast moving items. If your bestselling products keep running out, the problem may not be demand forecasting. It may be that you lack the cash to reorder on time.
Smaller, more frequent purchase orders. Buying in tiny batches because you cannot afford bulk quantities raises your per unit cost and eats into margins.
Expired or obsolete inventory piling up. Paradoxically, cash crunches can also cause overstock of slow movers. When you cannot afford to restock what sells, you are left with what does not.
Supplier lead times stretching. Vendors may deprioritize your orders if your payment history has become inconsistent, pushing your restocking timeline further out.
Lost bulk purchase discounts. Many suppliers offer 5 to 10 percent discounts on advance or bulk orders. Without ready cash, you miss these savings repeatedly.
Each of these symptoms compounds the next. A shopkeeper who cannot restock loses daily revenue. That lost revenue makes the next restock even harder to fund. mPokket's instant business loan process, which is designed to disburse funds quickly through a paperless application, can help break this cycle before it deepens.
Payroll is non negotiable. Employees, whether they are shop assistants, delivery staff, or skilled workers, depend on timely salary payments to cover rent, groceries, and family obligations. When a business owner delays salaries even by a week, the consequences are immediate and personal.
Staff begin looking for other jobs. Productivity drops because worried employees cannot focus. In tight labor markets, replacing a trained worker costs far more than the delayed salary itself. For micro enterprises with three to ten employees, losing even one person can halt operations.
The reputational cost matters too. Word travels fast in local business communities. A reputation for late salary payments makes it harder to attract reliable workers in the future. This is especially damaging for businesses in sectors like food service, retail, and logistics where dependable staffing is essential.
A working capital loan designed for salary payouts and operational expenses can help business owners maintain payroll discipline. mPokket's collateral free business loan option, with its quick approval process, is designed to help self employed professionals and MSME owners access funds before payday pressure becomes a staffing crisis.
Supplier relationships are built on consistency. A vendor who has supplied raw materials on 30 day credit for two years will not extend the same terms after three consecutive late payments. The erosion happens in stages.
First, the vendor sends polite reminders. Then, credit terms tighten from 30 days to 15 days or even cash on delivery. Next, the vendor may refuse to fulfill orders until past dues are cleared. Finally, the vendor drops the account entirely and redirects supply to more reliable buyers.
For small businesses, losing a trusted vendor is not just an inconvenience. It means scrambling to find alternatives, often at higher prices and with inferior quality. In industries like garment manufacturing, food processing, or construction materials, vendor relationships can take years to establish and days to destroy.
The financial math is straightforward. A business that pays vendors on time often receives better pricing, priority during shortages, and flexible return policies. A business that pays late loses all three advantages simultaneously.
Maintaining vendor trust requires predictable cash flow. When receivables are delayed or seasonal dips hit, a working capital loan can help bridge the gap. mPokket's online business loan process is designed to help MSME owners access funds with minimal documentation, potentially preserving vendor relationships that took years to cultivate.
Not every cash flow hiccup requires a loan. Seasonal fluctuations are normal. The critical question is whether the gap is temporary and manageable or whether it is starting to cause structural damage to the business. Here are signals that a business may have crossed the tipping point.
You are juggling which bills to pay first. Choosing between vendor payments and rent means cash flow has moved from tight to critical.
Customers are complaining about availability. When stockouts become visible to buyers, revenue loss accelerates.
Employees are asking about salary dates. If staff are inquiring before payday, trust is already fraying.
You are turning down new orders. Refusing business because you cannot fund the inventory or labor to fulfill it is a clear sign of working capital distress.
Personal savings are funding business expenses. This blurs the line between personal and business finance, creating risk on both sides.
Vendor credit terms have worsened. If suppliers have shortened payment windows or demanded advance payment, they are signaling reduced confidence.
When three or more of these signals appear together, the business likely needs external working capital support. Waiting longer typically increases the cost of recovery.
A working capital loan is specifically designed to address short term operational needs. Unlike a business expansion loan, which funds growth initiatives like new branches or equipment, a working capital loan covers the everyday costs that keep a business running: inventory purchases, salary payouts, vendor payments, and utility bills.
For Indian MSMEs, the key advantages of a working capital loan include speed of access, flexible tenure, and the ability to borrow without pledging assets. Digital lenders like mPokket have streamlined this process further by offering a 100 percent online application, paperless KYC using Aadhaar and PAN, and quick disbursal designed to get funds into a business bank account rapidly.
mPokket's approach to working capital lending is designed to be accessible to small business owners and self employed professionals who may not have perfect credit scores or extensive financial documentation. The collateral free structure means business owners do not need to risk personal property or equipment to access short term funds.
Responsible borrowing remains important. Before applying, business owners should estimate the exact shortfall, choose a tenure that aligns with expected receivables, and ensure the EMI fits within monthly cash flow. mPokket's business loan EMI calculator can help with this planning.
Funding delays do not have to become business emergencies. Recognizing the symptoms early, whether in inventory gaps, payroll pressure, or vendor strain, and acting before the damage compounds is the difference between a temporary cash flow dip and a lasting operational setback. mPokket's fast, paperless working capital loan process is designed to help Indian small business owners bridge that gap before it widens.
A working capital loan is short term business finance that covers everyday operational costs like inventory, salaries, and vendor payments. It bridges temporary cash flow gaps rather than funding long term expansion. mPokket offers collateral free working capital loans with a paperless online process.
Yes. Working capital loans are designed for exactly these purposes. They help business owners maintain payroll schedules and pay suppliers on time, preserving employee morale and vendor trust during cash flow gaps.
mPokket offers a 100 percent online, paperless business loan application with quick approval. The collateral free process is designed to help MSME owners and self employed professionals access working capital before cash flow gaps cause operational damage.
Digital lenders like mPokket offer instant business loans with minimal documentation, online KYC using Aadhaar and PAN, and quick disbursal to business bank accounts. These options can help small business owners access funds faster than traditional bank processes.
Consider a working capital loan when you notice frequent stockouts, difficulty meeting payroll, worsening vendor credit terms, or when you are turning down orders due to insufficient funds. Acting early can help prevent temporary gaps from becoming lasting damage.
₹1,000 Instant Loan: Why Can the Amount Credited Be Lower Than the Sanctioned Amount?
3 min read • 11 October 2026
How to use a personal loan EMI calculator before borrowing for an emergency
4 mins min read • 19 October 2026
10 money management tips you can take to the bank
2 min read • 6 December 2024
The smartest emergency borrowing advice often starts with smaller amounts and shorter plans
4 mins min read • 19 October 2026