4 mins min read • 23 October 2026


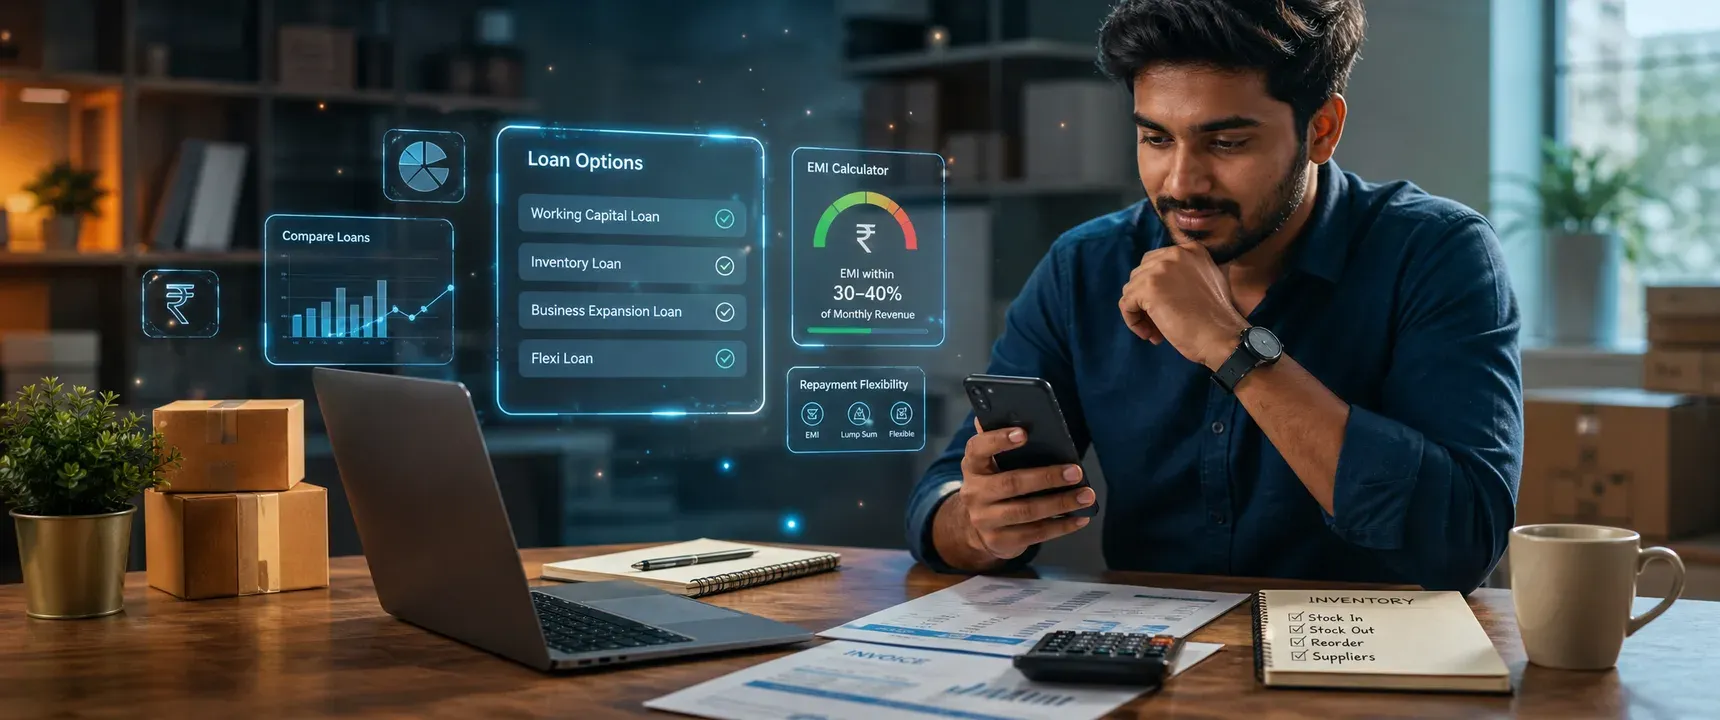
Table of content
Summary
Why bigger is not better
Matching loan type to use case
How to assess repayment capacity
The discipline of purpose based borrowing
Who benefits most from fit based selection
A smarter framework for loan selection
FAQs
What makes a business loan "best"? - The best business loan matches your actual purpose, whether that is working capital, inventory, expansion, or bridging a cash flow gap. Borrowing more than you need increases total interest and repayment pressure without adding value.
Why does use case matter more than size? - A working capital loan for vendor payments has different tenure and repayment needs than an expansion loan for hiring. Aligning the loan type to the use case keeps EMI manageable and protects cash flow.
How should MSMEs evaluate loan options? - Compare purpose fit, tenure flexibility, collateral requirements, and total repayment cost rather than headline loan amounts. mPokket offers collateral free business loans with flexible repayment designed for specific MSME and startup needs.
What role does repayment capacity play? - Borrowing within your repayment capacity, typically keeping EMI below 30 to 40 percent of monthly revenue, prevents cash flow strain and supports disciplined credit building over time.
Who benefits from purpose based borrowing? - MSMEs, self employed professionals, gig workers, women entrepreneurs, and early stage startups all benefit when they borrow for a defined need rather than chasing the maximum available amount.
Follow our Whatsapp Community for more offers and updates.
Join nowMany first time business borrowers assume that a higher sanctioned amount signals a superior product. This thinking is understandable. Larger numbers feel like stronger endorsements of creditworthiness. In practice, borrowing beyond your immediate need creates avoidable costs.
Every rupee you borrow carries an interest charge across the full tenure. If a retailer needs Rs 80,000 for seasonal inventory but borrows Rs 1,50,000 because the lender approved it, the extra Rs 70,000 sits idle or gets spent impulsively. The EMI, meanwhile, reflects the full amount. That gap between need and borrowing is where financial stress begins.
mPokket encourages borrowers to calculate the exact amount required before applying. A collateral free business loan designed for working capital needs can help a small business owner borrow precisely what the situation demands, without pledging assets or overcommitting monthly cash flow.
Not every business expense calls for the same loan structure. A vendor payment due next week requires short term liquidity. Opening a second outlet requires a longer tenure with a larger principal. Treating these two needs identically leads to either underborrowing (and missing the opportunity) or overborrowing (and straining repayment).
Consider three common scenarios that MSMEs and startups face regularly.
First, working capital gaps. A shopkeeper waiting on receivables needs funds for rent, salaries, and vendor payments. A short tenure working capital loan with flexible repayment options fits this need. The borrower repays quickly once receivables arrive, minimizing total interest.
Second, inventory restocking. A retailer preparing for a festive season needs to purchase stock in bulk. The loan amount should match the purchase order, not exceed it. Tenure should align with the expected sales cycle so that revenue from the inventory covers the EMI.
Third, business expansion. A home based entrepreneur scaling into a rented workspace needs funds for setup costs, equipment, and initial marketing. This use case justifies a longer tenure because the return on investment takes months to materialize. Borrowing too little here can stall the expansion; borrowing too much can create EMI pressure before revenue catches up.
mPokket offers business loans and personal loans for self employed professionals that accommodate these distinct scenarios. The platform's digital lending process, with paperless KYC using Aadhaar and PAN, is designed to help borrowers access the right amount quickly without a branch visit.
Repayment capacity is the single most overlooked factor in loan selection. Borrowers often focus on eligibility ("how much can I get?") rather than affordability ("how much can I comfortably repay?"). These are different questions with different answers.
A practical approach is to calculate your average monthly revenue or income over the past three to six months. Subtract fixed operating expenses. The remaining amount represents your repayment headroom. Financial discipline suggests keeping EMI obligations within 30 to 40 percent of that headroom.
For self employed professionals, freelancers, and gig workers whose income fluctuates, this calculation matters even more. A fixed EMI that feels manageable in a strong month can become a burden during a lean period. Flexible repayment loans, where borrowers can choose between EMI and lump sum options, address this reality directly.
mPokket's business loan EMI calculator can help borrowers estimate monthly instalments before committing. Adjusting the loan amount, tenure, or both until the EMI fits comfortably within cash flow is a smarter strategy than maximizing the sanctioned amount.
Purpose based borrowing is not about limiting ambition. It is about channeling borrowed capital toward outcomes that generate returns or solve specific problems. When a borrower defines the purpose before applying, three things happen naturally.
The loan amount becomes precise. There is no guesswork or inflation of the request. The borrower knows exactly what the funds will cover, whether that is inventory purchase, equipment finance, salary payouts, or marketing initiative funding.
The tenure becomes logical. A three month cash flow gap does not need a twelve month loan. A business expansion that takes six months to yield revenue should not be financed with a sixty day product. Purpose dictates timeline.
The repayment plan becomes realistic. When the borrower knows how and when the borrowed capital will generate returns, the repayment schedule aligns with actual cash flow rather than arbitrary dates.
This approach is especially relevant for MSMEs and startups in India, where cash flow patterns are often irregular and seasonal. mPokket's collateral free, paperless loan products are designed to support this kind of disciplined borrowing, with flexible tenure options and quick disbursal that matches the urgency of real business needs.
Several borrower segments gain the most from choosing loans based on fit rather than size.
MSME owners running retail shops, trading businesses, or service firms benefit because their working capital needs are cyclical. Borrowing the right amount at the right time keeps operations smooth without creating long term debt.
Self employed professionals such as doctors, chartered accountants, and consultants benefit because their income is project based. A flexi personal loan or a short term business loan that accommodates variable cash flow is more useful than a large fixed EMI product.
Women entrepreneurs starting home based ventures, from tiffin services to online retail, benefit because their initial capital needs are modest. A small loan for a specific setup cost is more practical than a large facility that comes with disproportionate repayment obligations.
Gig workers and freelancers benefit because their earnings change weekly or monthly. A loan with flexible repayment modes, including UPI repayment and autopay options, reduces the risk of missed payments during lean periods.
Early stage startups benefit because their runway capital needs are defined by specific milestones. Borrowing for a three month runway is different from borrowing for twelve months. Purpose based selection prevents dilution of focus and unnecessary interest costs.
mPokket serves these segments through its digital lending platform, offering instant business loans and personal loans with minimal documentation, direct bank transfer, and repayment options that adapt to the borrower's situation.
Before applying for any business loan, ask four questions. What is the specific expense this loan will cover? How quickly will that expense generate returns or resolve the cash flow gap? What monthly EMI can my business absorb without straining operations? And does the loan product offer the flexibility my income pattern requires?
These questions shift the evaluation from "which lender offers the most" to "which product fits my situation." That shift is where better borrowing decisions begin.
mPokket's approach to business finance reflects this philosophy. By offering collateral free business loans, flexible repayment options, and a 100 percent online process with Aadhaar and PAN based KYC, the platform is designed to help MSMEs, startups, and self employed borrowers access precisely the capital they need, when they need it, without the burden of borrowing beyond their purpose.
The best business loan is not the biggest one available. It is the one that solves a specific problem, fits within your repayment capacity, and leaves your business stronger after the last EMI is paid.
The best business loans for MSMEs and startups are those aligned to a specific use case, such as working capital, inventory, or expansion. mPokket offers collateral free business loans with flexible repayment, paperless digital KYC, and quick disbursal designed for small business needs.
The best online business loan provider is one that matches loan amount, tenure, and repayment structure to your actual business need. mPokket provides a 100 percent online business loan process with Aadhaar and PAN based verification, flexible EMI options, and direct bank transfer.
Calculate the exact expense the loan will cover, then estimate your monthly repayment capacity. Keep EMI within 30 to 40 percent of your available cash flow. mPokket's business loan EMI calculator can help you estimate instalments before applying.
Yes. Collateral free business loans, also called unsecured business loans, are available from digital lenders like mPokket. These loans do not require pledging property or assets and are designed for MSMEs, self employed professionals, and startups.
A working capital loan covers short term operational expenses like inventory, vendor payments, and salaries. A business expansion loan funds longer term growth activities like opening new branches, hiring, or purchasing equipment. Choosing the right type depends on your specific business need.
Online ₹2,000 Loan: How Does Repayment Frequency Change Total Cost?
3 min read • 12 October 2026
₹1,000 Cash Loan: Lump-Sum Repayment vs EMI—Which Fits a Small Ticket Better?
4 min read • 12 October 2026
UPI, autopay, and the new repayment stack for Indian borrowers
4 mins min read • 6 October 2026