4 mins min read • 20 October 2026


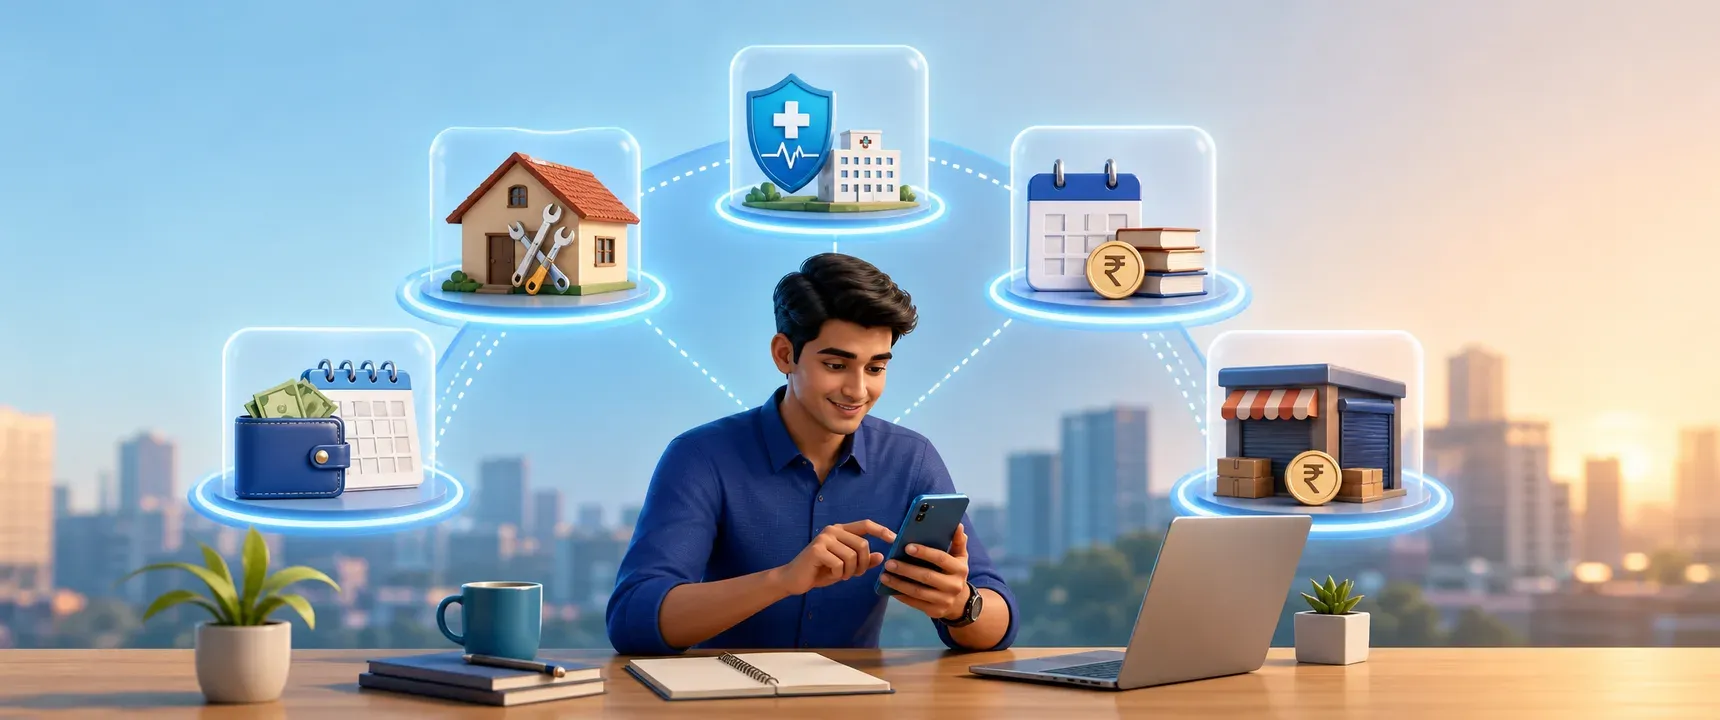
Table of content
India's 2026 emergency borrowing landscape by use case and urgency
Why use case matters for emergency loans
Household repairs: same day needs
Salary gaps and month end crunches
Education fees: planned but urgent
Business cash flow crunches
How to choose the right emergency loan
FAQs
A hospital bill at 2 a.m., a broken water pump on a Sunday, or a tuition fee deadline three days before payday. Each of these situations demands a different speed, amount, and repayment structure. Yet most Indians searching for emergency credit in 2026 land on generic "personal loan" pages that ignore the urgency spectrum entirely. mPokket maps the emergency borrowing landscape in India by use case and urgency so borrowers can match the right loan type to the right crisis, fast.
Follow our Whatsapp Community for more offers and updates.
Join nowNot every emergency is the same. A medical bill that must be paid within hours sits at one end of the urgency spectrum. A semester fee due next week sits at the other. Treating all emergencies as identical leads borrowers toward products that may charge higher interest than necessary or lock them into rigid repayment schedules.
In India, emergency borrowing intent is high but fragmented. Searchers ask for the "best app for medical emergency loan," "instant loan for home repair," or "quick loan before salary." Each phrase signals a distinct need. The table below organizes the five most common emergency borrowing scenarios by urgency, typical loan size, and the loan features that matter most.
| Use case | Urgency level | Typical amount | Key loan feature needed | Ideal repayment window |
|---|---|---|---|---|
| Medical bills | Critical (minutes to hours) | Rs 10,000 to Rs 2,00,000 | Instant approval, direct bank transfer | 3 to 12 months EMI |
| Household repairs | High (same day) | Rs 5,000 to Rs 50,000 | Paperless application, no collateral | 1 to 6 months EMI |
| Salary gap or month end crunch | Moderate (1 to 3 days) | Rs 3,000 to Rs 30,000 | Advance salary loan, flexible tenure | Next paycheck cycle |
| Education fees | Scheduled (1 to 2 weeks) | Rs 10,000 to Rs 1,50,000 | Collateral free, EMI option | 3 to 12 months EMI |
| Business cash flow crunch | Variable (hours to days) | Rs 20,000 to Rs 2,00,000 | Working capital loan, quick disbursal | 3 to 12 months EMI |
Hospital admissions rarely wait for banking hours. When a family member needs treatment, the borrower's priority is speed of disbursal, not interest rate comparison. Digital lenders that complete KYC through Aadhaar and PAN verification, approve within minutes, and transfer funds directly to a verified bank account are designed to serve this scenario.
mPokket's paperless loan process uses OTP based digital KYC and can help disburse funds to a borrower's bank account on the same day. Because the loan is collateral free and unsecured, borrowers do not need to pledge property or assets during a health crisis. Flexible EMI repayment options allow the borrower to spread the cost across several months rather than facing a lump sum burden during recovery.
Borrowers should still verify the total repayment amount using a personal loan EMI calculator before accepting the loan. Even in a crisis, understanding the interest rate and tenure prevents repayment stress later.
A leaking roof, a failed inverter, or a broken water heater can disrupt daily life within hours. These repairs typically cost less than medical emergencies but still require same day access to funds. The borrower profile here is broad: salaried employees, housewives managing household budgets, and self employed professionals working from home.
For housewives or homemakers without formal income proof, digital lenders that use alternative data assessment (such as household expense patterns or co applicant details) can help widen access. mPokket's loan without collateral approach and minimal documentation process is designed to reduce friction for borrowers who may not have salary slips or ITR documents.
Repayment for household repairs often fits a shorter tenure. A flexible repayment loan that allows the borrower to choose between 1 and 6 month EMI schedules can help align payments with monthly cash flow.
The paycheck timing gap is one of the most common reasons Indians search for emergency credit. Rent, utility bills, and grocery expenses cluster at month end, but salary credits may arrive on the first or fifth of the following month. This 3 to 7 day gap creates a recurring cash crunch for salaried employees, freshers in their first job, and interns on monthly stipends.
An advance salary loan or a short term personal loan can bridge this gap. mPokket's instant personal loan process, with approval that can happen within minutes and direct bank transfer, is designed to help borrowers cover next paycheck expenses without resorting to informal borrowing from friends or high cost credit card cash advances.
Freshers and interns who have no credit history can still be assessed through alternative data. mPokket does not require a perfect CIBIL score, which can help first time borrowers access formal credit and begin building a repayment track record. Responsible, on time repayment of even a small loan can help establish credit history early in a career.
School and college fee deadlines are technically predictable, but many families face them as emergencies when savings fall short. A parent may need Rs 50,000 for a semester fee within two weeks. A young professional may need Rs 20,000 for an upskilling course that starts next Monday.
Because the timeline is slightly longer (days rather than hours), borrowers have more room to compare interest rates, tenure options, and total repayment amounts. A personal loan EMI calculator helps estimate whether the monthly instalment fits the household budget. mPokket's collateral free personal loan with flexible EMI options is designed to serve this use case for salaried employees, self employed professionals, and housewives funding children's education.
Women borrowers in particular search for "personal loan for women" and "loan for housewife for children's education." Digital lenders that offer paperless applications with Aadhaar and PAN based KYC can help reduce the documentation barrier for homemakers who may lack traditional income proof.
Small business owners, freelancers, gig workers, and self employed professionals face cash flow gaps when client payments are delayed, inventory needs restocking, or vendor invoices come due before revenue arrives. A shopkeeper may need Rs 30,000 for inventory before a festival season. A freelancer may need Rs 15,000 to cover operating expenses while waiting for a client invoice to clear.
The urgency here varies. Some cash flow gaps are predictable (seasonal inventory cycles), while others are sudden (a large client delays payment). Working capital loans and instant business loans serve this segment. mPokket's quick loan process, with digital document submission and no branch visit, is designed to help self employed borrowers and small business owners access funds without pledging business assets.
For MSME owners, having a Udyam registration certificate and basic business proof (bank statements, GST registration if applicable) can help streamline the application. mPokket's collateral free business loan approach means borrowers can preserve personal property and business assets while addressing short term cash flow needs.
Matching the loan to the emergency requires answering four questions before applying.
How soon do I need the funds?
How much do I actually need?
Can I repay within one paycheck cycle?
What is the total cost including interest?
Borrowers who need funds within hours should prioritize lenders offering instant approval and direct bank transfer. Those with a few days of lead time can compare interest rates and tenure options more carefully. In both cases, using an EMI calculator and reading the Key Fact Statement before accepting the loan helps prevent overborrowing.
mPokket's 100 percent online process, from application to disbursal, is designed to help borrowers across the urgency spectrum. Whether the need is a medical bill at midnight or a tuition fee due next week, the combination of paperless KYC, collateral free access, flexible EMI schedules, and direct bank transfer can help borrowers act quickly without compromising on transparency.
Emergency borrowing is not one size fits all. By understanding which use case you face and what loan features matter most for that scenario, you can borrow responsibly, repay on time, and build a healthy credit profile for the future. mPokket is designed to support that journey for salaried employees, self employed professionals, freshers, housewives, gig workers, and small business owners across India.
mPokket is designed to offer instant personal loans with paperless Aadhaar and PAN based KYC, same day approval, and direct bank transfer to a verified account. This process can help borrowers access funds quickly for medical emergencies without collateral or a branch visit.
Yes. Digital lenders like mPokket offer collateral free, unsecured personal loans. Borrowers do not need to pledge property, gold, or business assets. Approval is based on identity verification and alternative data assessment rather than physical security.
Most digital lenders require Aadhaar card, PAN card, a selfie for identity verification, and bank account details for disbursal. mPokket's paperless process uses OTP based digital KYC, so borrowers typically do not need salary slips or extensive documentation.
On platforms like mPokket, approval can happen within minutes after completing digital KYC. Funds are designed to be transferred directly to the borrower's verified bank account on the same day, though exact timing depends on banking hours and verification completion.
Yes. mPokket is designed to serve borrowers without traditional income proof or credit history, including freshers, interns, and housewives. Alternative data assessment and minimal documentation requirements can help widen access to formal emergency credit.
How mPokket thinks about credit access for women, freelancers, and gig workers
4 mins min read • 1 October 2026
Is GST Registration Mandatory for a Business Loan in India?
3 min read • 10 September 2026
₹1,000 Instant Loan: Why Can the Amount Credited Be Lower Than the Sanctioned Amount?
3 min read • 11 October 2026
10 money management tips you can take to the bank
2 min read • 6 December 2024