3 mins min read • 29 September 2026


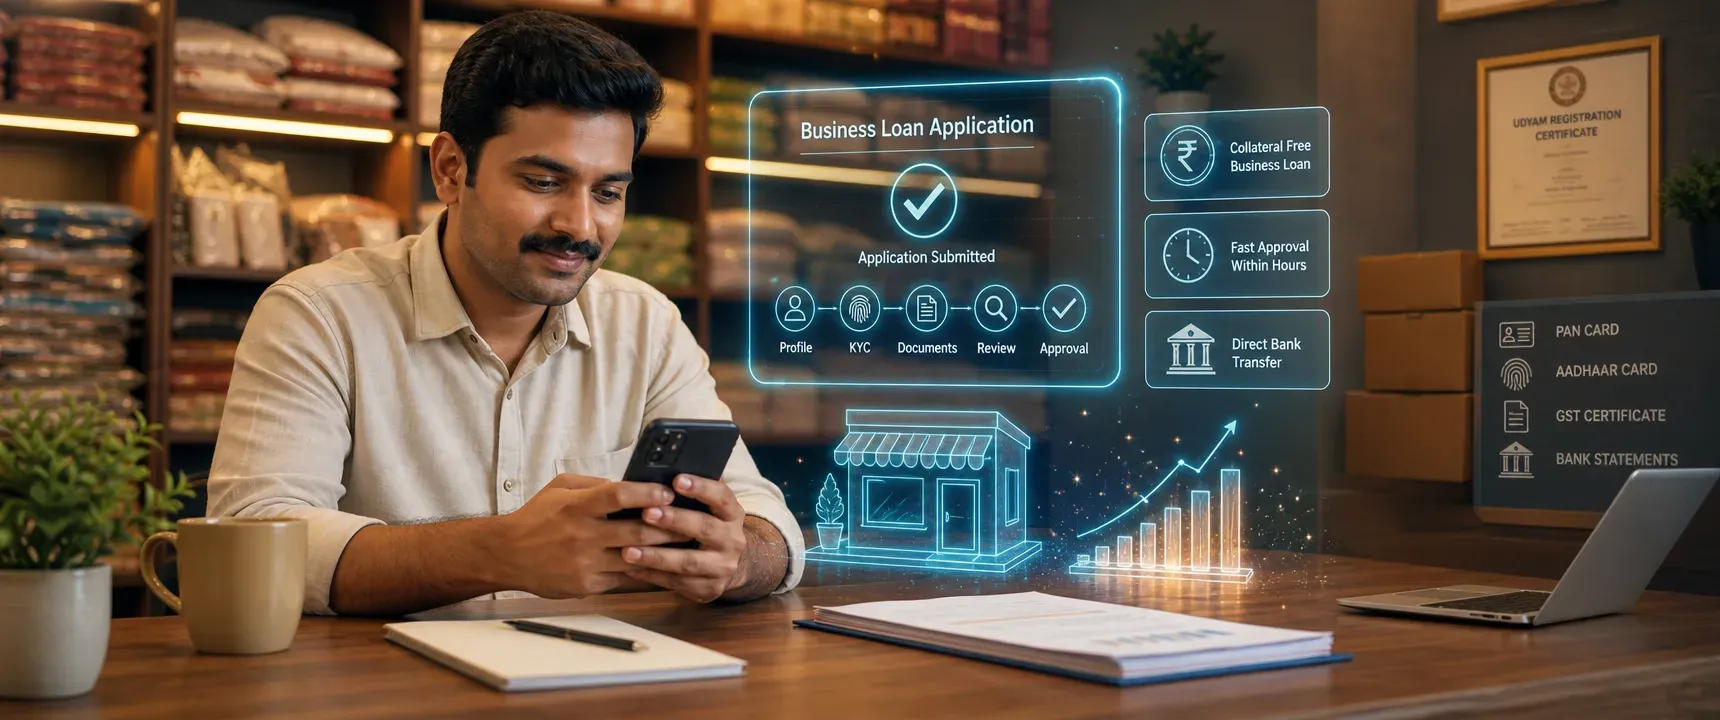
Table of content
Summary
Prepare documents before you start
Match your profile to eligibility
Fill the application with precision
Complete digital KYC correctly
Review before you submit
After submission, stay responsive
Set up repayment from day one
FAQs
A rejected online business loan application costs more than time. For small Indian businesses, it can mean missed inventory cycles, delayed vendor payments, or a lost growth window. mPokket, a digital lending platform built for speed and minimal documentation, helps MSMEs and micro entrepreneurs access collateral free business loans through a paperless process. Knowing how to apply correctly is what separates a quick approval from a frustrating rejection.
Follow our Whatsapp Community for more offers and updates.
Join nowThe single biggest cause of application delays is missing or incorrect documentation. Before opening any online business loan application, gather the following items and verify that every detail matches across documents.
PAN card in the name of the business owner or proprietor. Ensure the name spelling matches your Aadhaar and bank account exactly.
Bank statements from the last three to six months showing regular business transactions. Use the account where you want funds disbursed.
Selfie or photograph for identity verification, if the platform requires it.
Platforms like mPokket accept digital uploads, so keep clear scanned copies or well lit phone photographs ready. Blurry or cropped documents trigger manual review and slow down approval.
Applying for a loan you do not qualify for wastes time and can leave a negative mark on your credit profile. Before submitting, confirm that you meet the basic eligibility criteria most digital lenders use.
Business vintage matters. Most platforms require your business to be at least six months old. If you are a startup with less history, look for lenders that specifically offer startup business loans with alternative data based approval.
Repayment capacity is assessed through your bank statements and cash flow patterns, not just your turnover. Lenders examine whether your monthly inflows can comfortably cover the proposed EMI. Use a business loan EMI calculator to estimate your monthly obligation before you apply.
mPokket and similar digital lenders may not require a high CIBIL score. They can use alternative assessment methods, evaluating transaction patterns, business consistency, and income stability instead. This approach is designed to help first time borrowers and businesses without formal credit history.
Accuracy in the application form is non negotiable. A single mismatch between your PAN name and bank account name can trigger rejection. Follow these practices when completing the form.
Use your legal name exactly as it appears on PAN. Do not use nicknames, abbreviations, or alternate spellings.
Enter the correct business type. Whether you are a sole proprietor, partnership, or private limited company, select the right category. Misclassification raises red flags during verification.
Request a realistic amount. Borrowing more than your cash flow supports leads to rejection. Calculate what you actually need and what your monthly EMI would be before choosing a loan amount and tenure.
Double check your mobile number and email. OTP verification and approval notifications depend on these. An outdated number means you cannot complete KYC.
Digital KYC replaces the branch visit. On platforms like mPokket, this typically involves Aadhaar based OTP verification and PAN validation. The process takes minutes when done right, but common mistakes can stall it.
Ensure your Aadhaar is linked to your current mobile number. If you recently changed numbers, update your Aadhaar through the UIDAI portal before applying. Without a linked number, OTP verification fails.
When uploading your selfie for identity verification, use good lighting and a plain background. Avoid sunglasses, hats, or anything that obscures your face. The automated system compares your selfie against your Aadhaar photograph.
After submitting KYC documents, do not close the app or browser until you receive confirmation. Interrupted sessions sometimes require you to restart the entire process.
Treat the final review screen as a checkpoint, not a formality. Go through every field one more time. Confirm that your bank account number and IFSC code are correct, because funds will be disbursed directly to this account after approval.
Check that all uploaded documents are legible. A partially visible PAN number or a bank statement with cut off transaction rows will be flagged during verification. Re upload any document that looks unclear on screen.
If the platform offers a draft or save option, use it. This lets you return and verify details without losing progress. mPokket's paperless application process is designed for speed, but speed should not come at the cost of accuracy.
Your application does not end at the submit button. Digital lenders may request additional information or clarification during the verification stage. Keep your phone accessible and respond to any calls, messages, or in app notifications promptly.
If approved, review the loan terms carefully before accepting. Check the interest rate, EMI amount, tenure, and any processing fees. Use the business loan EMI calculator to verify that the monthly instalment fits your cash flow.
Once you accept, funds are typically transferred directly to your verified bank account. On platforms like mPokket, this disbursal can happen within hours. Confirm receipt in your bank statement and save the loan agreement for your records.
Timely repayment protects your credit profile and keeps you eligible for future borrowing. Set up autopay or UPI based repayment on the day you receive the loan, not when the first EMI is due.
Choose a repayment mode that matches your cash flow. If your business earns daily or weekly, a flexible repayment option (where available) can reduce month end pressure. mPokket offers multiple repayment modes including UPI and debit card options.
Mark your EMI due dates on a calendar or set phone reminders. Missing even one payment can affect your credit score and may result in late fees. Consistent, on time repayment also helps build your credit history, which can improve your eligibility for larger loans in the future.
Small Indian businesses, whether local retailers, home based ventures, or self employed professionals, can access working capital faster than ever through digital lending. The difference between a smooth approval and a frustrating rejection often comes down to preparation, accuracy, and responsiveness. By following these best practices, you position your business to get the funds it needs without unnecessary delays. mPokket's collateral free, paperless business loan process is designed to help MSMEs and micro entrepreneurs move quickly, but the quality of your application still determines the outcome.
Download a digital lending app like mPokket, complete your profile with PAN and Aadhaar details, upload business proof and bank statements, verify your identity through OTP based KYC, and submit. Approval and disbursal can happen within hours for complete applications.
You typically need a PAN card, Aadhaar card, business proof such as Udyam registration or GST certificate, and recent bank statements. Some platforms also require a selfie for identity verification. mPokket accepts paperless digital uploads of these documents.
Yes. Digital lenders like mPokket offer collateral free business loans for MSMEs, shopkeepers, and self employed professionals. Approval is typically based on business cash flow, bank statements, and alternative data assessment rather than pledged assets.
Common reasons include name mismatches across PAN, Aadhaar, and bank account; incomplete document uploads; requesting amounts beyond repayment capacity; and failing OTP verification due to an unlinked Aadhaar mobile number. Reviewing every detail before submission can help avoid these issues.
On digital platforms like mPokket, disbursal can happen within hours of approval. Speed depends on the completeness and accuracy of your application, successful KYC verification, and correct bank account details for direct transfer.
How Does mPokket Evaluate Personal Loan Eligibility for the Self-Employed?
1 min read • 7 July 2026
How Can CIBIL Defaulters in Mumbai Improve Their Chances of Getting a Personal Loan?
3 min read • 22 August 2026
Working Capital Loan: Everything Small Businesses Should Know
5 min read • 17 July 2026
Working Capital Loan, Cash Credit, or Overdraft: Which One Actually Fits Your Business?
3 min read • 16 September 2026
