3 min read • 17 September 2026


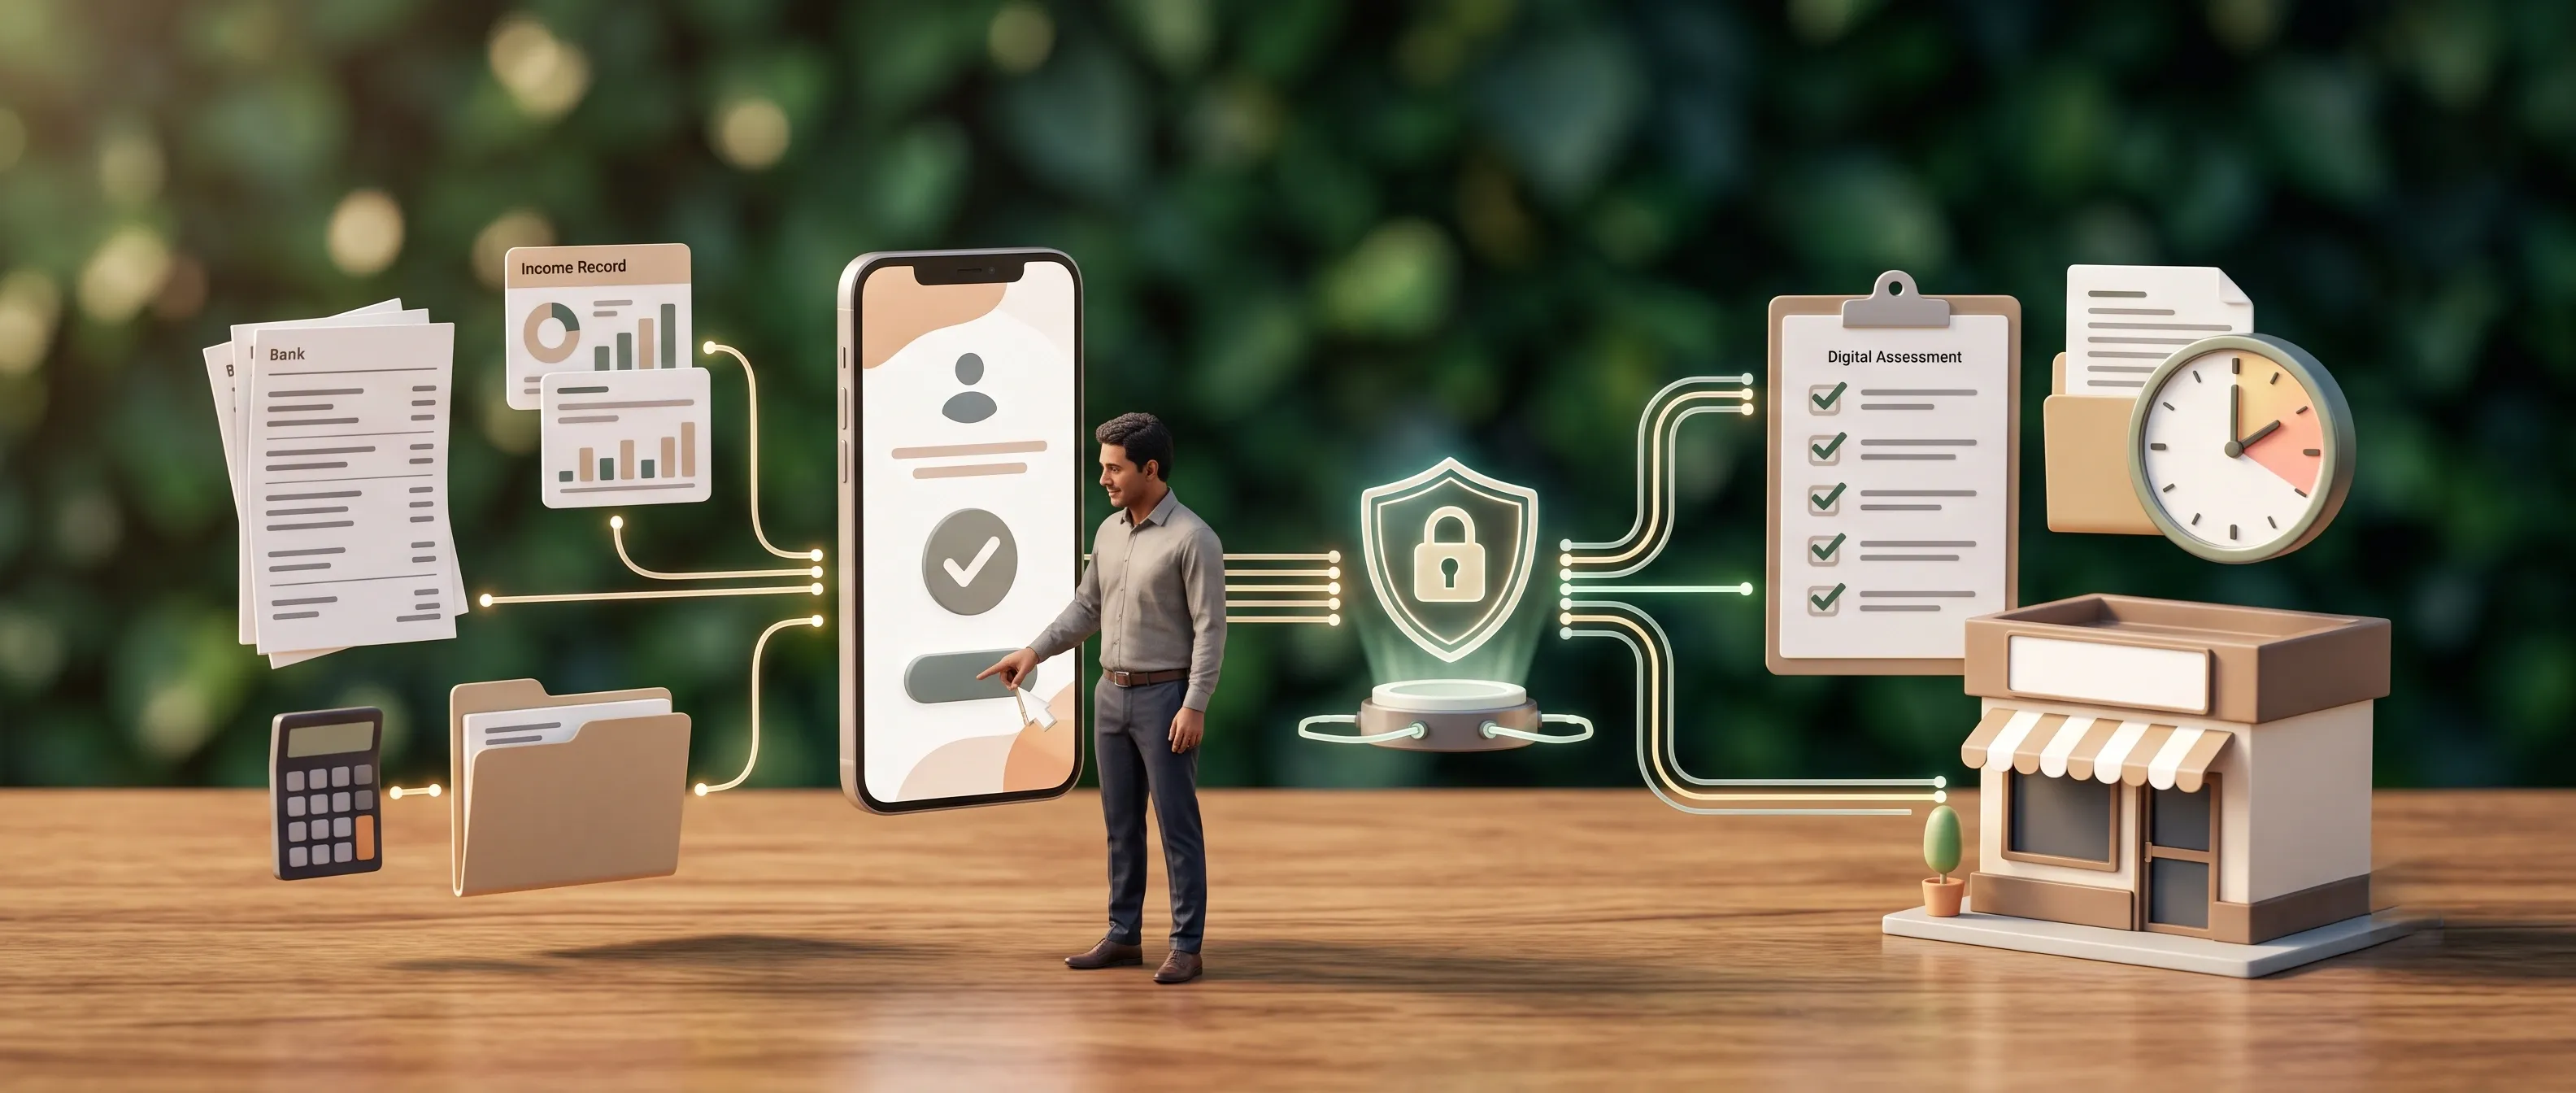
Table of content
Overview
What Is the Account Aggregator Framework?
How Does Account Aggregator Data Help Online Business Loan Assessment?
What Is Account Aggregator Consent?
How Does Account Aggregator Improve Business Loan Documentation?
Does Account Aggregator Data Improve Business Loan Eligibility?
What Are the Eligibility Criteria for an Online Business Loan?
What is the Best Instant Business Loan App for Small Business Owners?
Conclusion
Frequently Asked Questions
If you have ever applied for a loan for your shop or small business, you know the drill. Pull out bank statements, scan them, email them, and then wait while someone manually checks every page against your GST filings. It eats up days, sometimes weeks, and you're often not even sure why your file is stuck.
That's the real pain point behind most online business loan searches today. People want money fast, but the checking process behind the scenes has stayed slow and paper-heavy. This is where Account Aggregator data changes things.
In short, an account aggregator framework can make an online business loan assessment noticeably faster, since it lets lenders pull your verified financial data digitally instead of waiting on manual documents.
Let’s explore what the Account Aggregator framework actually is, how it feeds into business loan eligibility checks, what account aggregator consent means for you, and how it reshapes business loan documentation for small business owners.
Follow our Whatsapp Community for more offers and updates.
Join nowThe Account Aggregator framework is an RBI-backed system that lets you share financial data digitally, with your explicit consent, instead of handing over paper statements.
Picture it as a secure pipe connecting your bank or GST portal to the lender you're applying with. Nobody moves data through this pipe without you saying yes first. Regulated entities called account aggregators sit between your bank (a financial information provider) and the lender (a financial information user). They don't store your data; they just transmit it, encrypted, once you approve the request.
It helps because lenders get your real cash flow data quickly, cutting the back and forth that usually slows down loan processing.
Rather than asking you to upload months of statements for someone to read line by line, the system receives structured data straight from the source. A few things change in practice:
For anyone comparing lenders right now, this is one of the biggest shifts in how an online business loan actually gets approved.
It's your explicit, time-bound permission that spells out exactly what data gets shared, with whom, and for how long.
Nothing moves without it. Before any bank data reaches a lender, you see a consent screen showing the purpose, the data type, and how long it's valid for. You could allow just six months of bank data for one application and nothing beyond that. And unlike emailing a bank statement and losing track of where the copy ends up, this consent can be withdrawn later too.
It swaps manual uploads for digitally fetched, verified records, so there's far less paperwork between you and your funds.
Traditional business loan documentation usually means statements, ITRs, and GST returns collected separately, often re-requested when something doesn't match up.
Cleaner documentation shortens the gap between applying and actually getting your online business loan disbursed.
Yes, often it does, because lenders see a fuller, current picture of your cash flow instead of a snapshot from old paperwork.
Business loan eligibility checks have long leaned on credit scores and static income proofs, which can unfairly rule out owners with thin credit files but healthy cash flow.
With account aggregator data, a lender can look at real money movement and repayment patterns across accounts. That fuller view often works in favor of business owners who are creditworthy in practice but got overlooked by rigid, paperwork-heavy checks before.
Most lenders weigh business vintage, turnover, repayment history, and basic KYC before sanctioning a loan.
Generally, small business owners applying for an online business loan need:
Why Eligibility Checks Are Getting Faster
Since account aggregator data feeds straight into underwriting systems, checks that once took days can now be wrapped up within hours.
There isn't one universal "best" app. It depends on your loan amount, comfort with documentation, and how urgently you need funds. That said, small business owners looking for a simple, low-document online business loan should know about mPokket.
It's run by an RBI-registered NBFC, mPokket Financial Services Private Limited, offering business loans up to ₹2,00,000 through a largely paperless digital process, with EMI tenures from 6 to 24 months and no collateral required.
Before finalizing any lender, it helps to compare processing fees, interest rate ranges, tenure options, and how each one handles KYC and documentation, whether through account aggregator data or the older upload method.
Account aggregator data is genuinely reshaping how fast and how fair a business loan assessment can be. Swapping slow manual paperwork for consent-based, digitally verified data helps lenders judge business loan eligibility more accurately while cutting business loan documentation time dramatically.
If you're planning to apply for an online business loan soon, understanding how account aggregator consent works and picking a lender that uses this framework well could save you days of waiting around. Ready to check where you stand? Check your eligibility on the mPokket app and see how quickly a decision can come through.
1. What is an account aggregator framework?
It's an RBI-regulated system letting individuals and businesses share financial data digitally and securely, with consent, between banks and lenders, cutting out manual paperwork.
2. Can Account Aggregator data speed up online business loan approval?
Yes, generally it does, since lenders receive verified data directly instead of relying on manual checks and repeated document requests.
3. Is account aggregator consent mandatory for a business loan?
Not mandatory as your only path, but if you use the Account Aggregator route, consent is required before any data moves, and you decide its scope and duration.
4. Does Account Aggregator data improve business loan eligibility?
It can, since lenders get a fuller, current view of cash flow rather than relying purely on credit scores or static documents, which often helps thin-file borrowers.
5. What documents are required for an online business loan?
Usually PAN, Aadhaar, bank statements or account aggregator linked bank data, proof of business or income, and GST details where applicable, though this varies by lender.
How to Strategically Use Instant Business Loans for Short-Term and Long-Term Goals
4 min read • 24 July 2026
Why Do Online Business Loan Applications Fail During Digital Verification?
4 min read • 27 August 2026
How Can You Speed Up the Loan Application Process with the Right Documentation?
2 min read • 27 May 2026
