4 mins min read • 26 October 2026


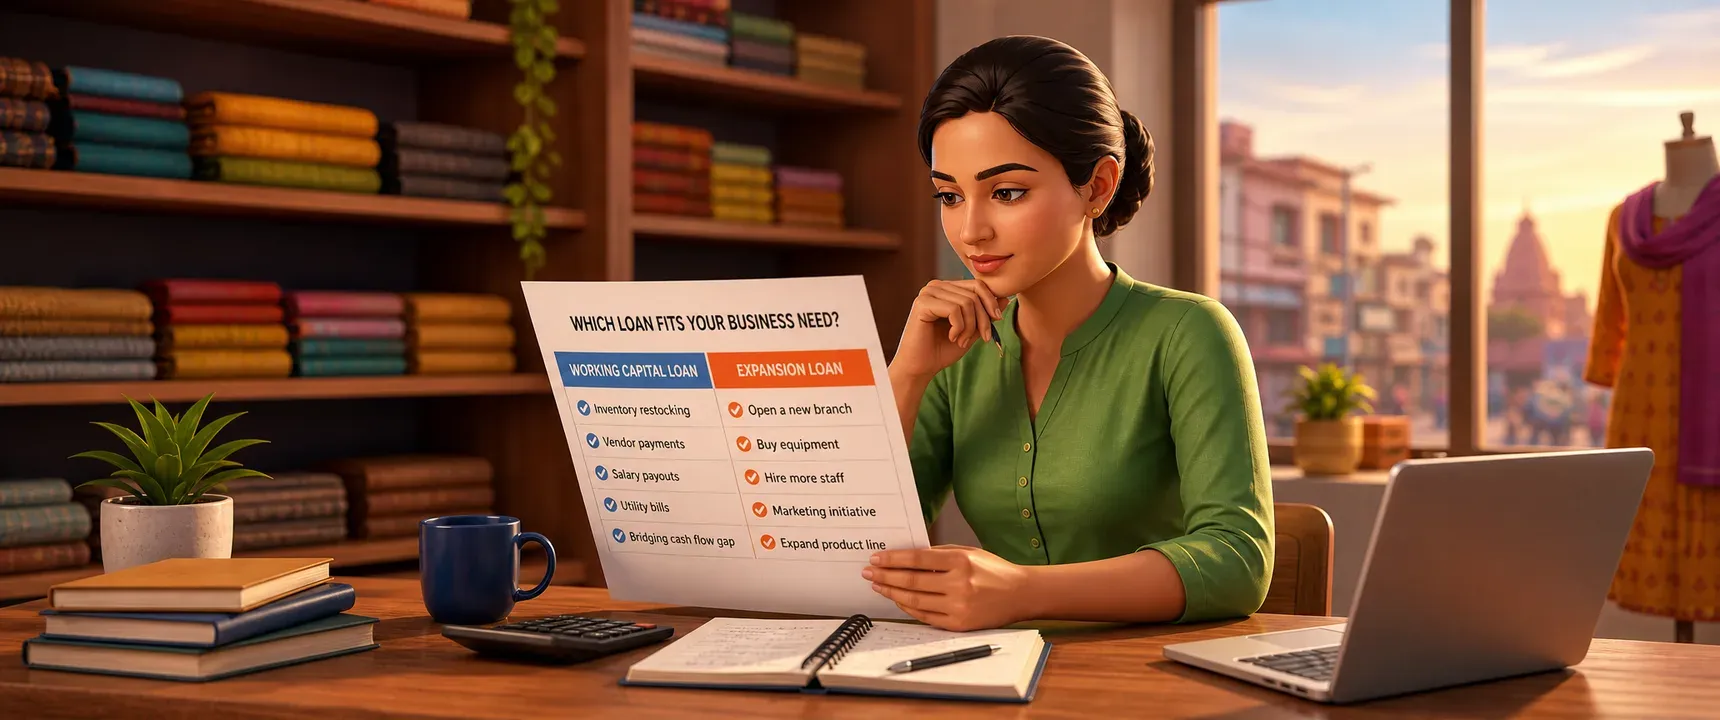
Table of content
Overview
Why small businesses confuse the two
The four scorecard criteria
Decision matrix: scoring your need
Common mistakes to avoid
How mPokket supports this decision
FAQs
Every Indian small business owner reaches a point where funds feel tight, but the real question is rarely "do I need money?" It is "what kind of money do I need?" Confusing a cash cycle gap with a growth opportunity, or vice versa, can lead to mismatched loan tenures, unnecessary interest costs, and repayment stress. mPokket believes that borrowing for the right reason is the foundation of responsible business finance. This scorecard helps shopkeepers, retailers, service providers, and MSME owners diagnose their actual funding need and choose between a working capital loan and a business expansion loan with clarity.
Follow our Whatsapp Community for more offers and updates.
Join nowA kirana store owner who needs to restock before Diwali and a salon owner planning a second outlet both "need money." But the store owner faces a cash flow gap measured in weeks. The salon owner faces a capital investment measured in months or years. When search results lump both needs under "business loan," owners often pick whichever product appears first.
This mismatch creates problems. A short term need funded by a long tenure loan means paying interest for months after the gap has closed. A growth investment funded by a short tenure loan means EMI pressure before the new branch generates revenue. The scorecard below separates these two situations using four measurable criteria.
Ask yourself: "Am I borrowing because money is going out faster than it is coming in this month?" If vendor payment dates, salary payouts, or rent fall before your receivables arrive, you have a cash cycle gap. This is a classic working capital need. Score this criterion high for working capital if the gap repeats monthly or seasonally.
If your cash cycle is stable and you are borrowing to fund something new, this criterion points toward expansion funding instead.
A business with predictable monthly revenue can plan fixed EMI repayments over a longer tenure. That stability suits expansion loans, where returns build gradually. A business with irregular or seasonal income, common among retailers, freelancers, and service providers, is better served by a shorter working capital loan that aligns repayment with the next revenue cycle.
Owners should review three to six months of bank statements or sales records before scoring this criterion. Consistent inflows suggest expansion readiness. Volatile inflows suggest working capital is the safer choice.
This is the most straightforward criterion. Map your intended use to one of two columns.
| Working capital uses | Expansion funding uses |
|---|---|
| Inventory restocking | Opening a new branch or outlet |
| Vendor payments and raw materials | Purchasing new equipment or machinery |
| Salary payouts and rent | Hiring additional staff for growth |
| Utility bills and operational expenses | Marketing initiative for new market entry |
| Bridging a seasonal cash flow gap | Product line expansion or diversification |
If most of your intended spending falls in the left column, a working capital loan is the right fit. If it falls in the right column, expansion funding is more appropriate. Some owners discover their needs span both columns. In that case, consider two separate, smaller loans rather than one mismatched product.
Repayment comfort measures how quickly you expect the borrowed funds to generate returns. Working capital loans typically have shorter tenures because the inventory you buy or the vendor you pay leads to revenue within days or weeks. Expansion loans require longer tenures because a new branch or equipment purchase takes months to become profitable.
Score this criterion by estimating your payback period. If you expect to recover the borrowed amount within one to three months, working capital is the match. If recovery will take six months or longer, expansion funding with a longer EMI schedule is more realistic.
Use the table below to score each criterion on a simple scale. Circle the column that matches your situation for each row. The column with more selections is your recommended loan type.
| Criterion | Points to working capital loan | Points to expansion loan |
|---|---|---|
| Cash cycle pressure | Recurring gap between payables and receivables | No immediate gap; funds needed for a new initiative |
| Revenue stability | Irregular or seasonal income patterns | Consistent monthly revenue over 3 to 6 months |
| Purpose of funds | Inventory, vendor payments, salaries, rent | New branch, equipment, hiring, marketing |
| Repayment comfort | Expect to recover funds within 1 to 3 months | Expect returns after 6 months or longer |
Three or four selections in one column give a clear answer. A two and two split suggests a blended need. In that case, separating the operational portion into a working capital loan and the growth portion into an expansion loan can help you manage repayment more comfortably.
Overborrowing is the first risk. A shopkeeper who needs two months of inventory funding does not need a twelve month expansion loan. The extra tenure means extra interest. Underborrowing is equally dangerous. An MSME owner opening a second location who takes only enough for rent, ignoring setup costs and initial marketing, will face a cash crunch within weeks of launch.
Another frequent error is ignoring repayment alignment. A working capital loan with weekly or fortnightly repayment can match a retailer's daily sales cycle. An expansion loan with monthly EMI can match a salaried professional's income pattern. Choosing a repayment frequency that clashes with your cash inflow creates unnecessary stress.
mPokket is designed to help borrowers, including small business owners and self employed professionals, access collateral free digital loans with flexible repayment options. By understanding whether your need is operational or growth oriented before you apply, you borrow for the right reason and choose a tenure that fits your cash flow. Platforms like mPokket can help simplify the application process through paperless digital KYC using Aadhaar and PAN, with funds transferred directly to your bank account.
mPokket also supports MSME financing education by encouraging business owners to evaluate their borrowing needs carefully. Responsible borrowing starts with asking the right questions, and this scorecard is designed to make those questions concrete.
Small business owners who take five minutes to score their situation across these four criteria will borrow with more confidence, repay with less stress, and build a stronger credit history over time. Whether you need to bridge a cash flow gap this month or fund a new branch next quarter, matching the loan to the need is the single most important financing decision you can make.
A working capital loan is a short term business loan that covers day to day operating expenses like inventory purchases, vendor payments, and salary payouts. It bridges the gap between cash outflows and incoming revenue, helping businesses maintain smooth operations during temporary cash cycle shortfalls.
Yes. Working capital loans are specifically designed for recurring operational costs. Salaries, vendor invoices, rent, and utility bills are all common uses. The key is that these expenses generate near term revenue, making a shorter repayment tenure appropriate.
A business expansion loan funds growth activities such as opening new branches, buying equipment, or hiring staff. It typically carries a longer repayment tenure because the investment takes months to generate returns. A working capital loan covers short term operational gaps with faster payback expectations.
Evaluate four factors: cash cycle pressure, revenue stability, the specific purpose of funds, and how quickly you expect to recover the borrowed amount. Scoring these criteria using a simple scorecard, like the one mPokket recommends in this guide, can help clarify which loan type fits your situation.
Yes. Several digital lending platforms, including mPokket, can help small business owners and self employed professionals access collateral free loans with paperless KYC. Eligibility is typically assessed using business vintage, cash flow patterns, and digital identity verification rather than physical asset pledges.
Common EMI calculator mistakes that lead to unrealistic borrowing decisions
3 mins min read • 22 October 2026
₹1,000 Instant Loan: Why Can the Amount Credited Be Lower Than the Sanctioned Amount?
3 min read • 11 October 2026
10 money management tips you can take to the bank
2 min read • 6 December 2024
15 Common Financial Mistakes That Student Makes
3 min read • 6 August 2024
₹2,000 Personal Loan: APR vs Interest Rate, What Is the Real Cost?
4 min read • 11 October 2026