3 min read • 11 September 2026


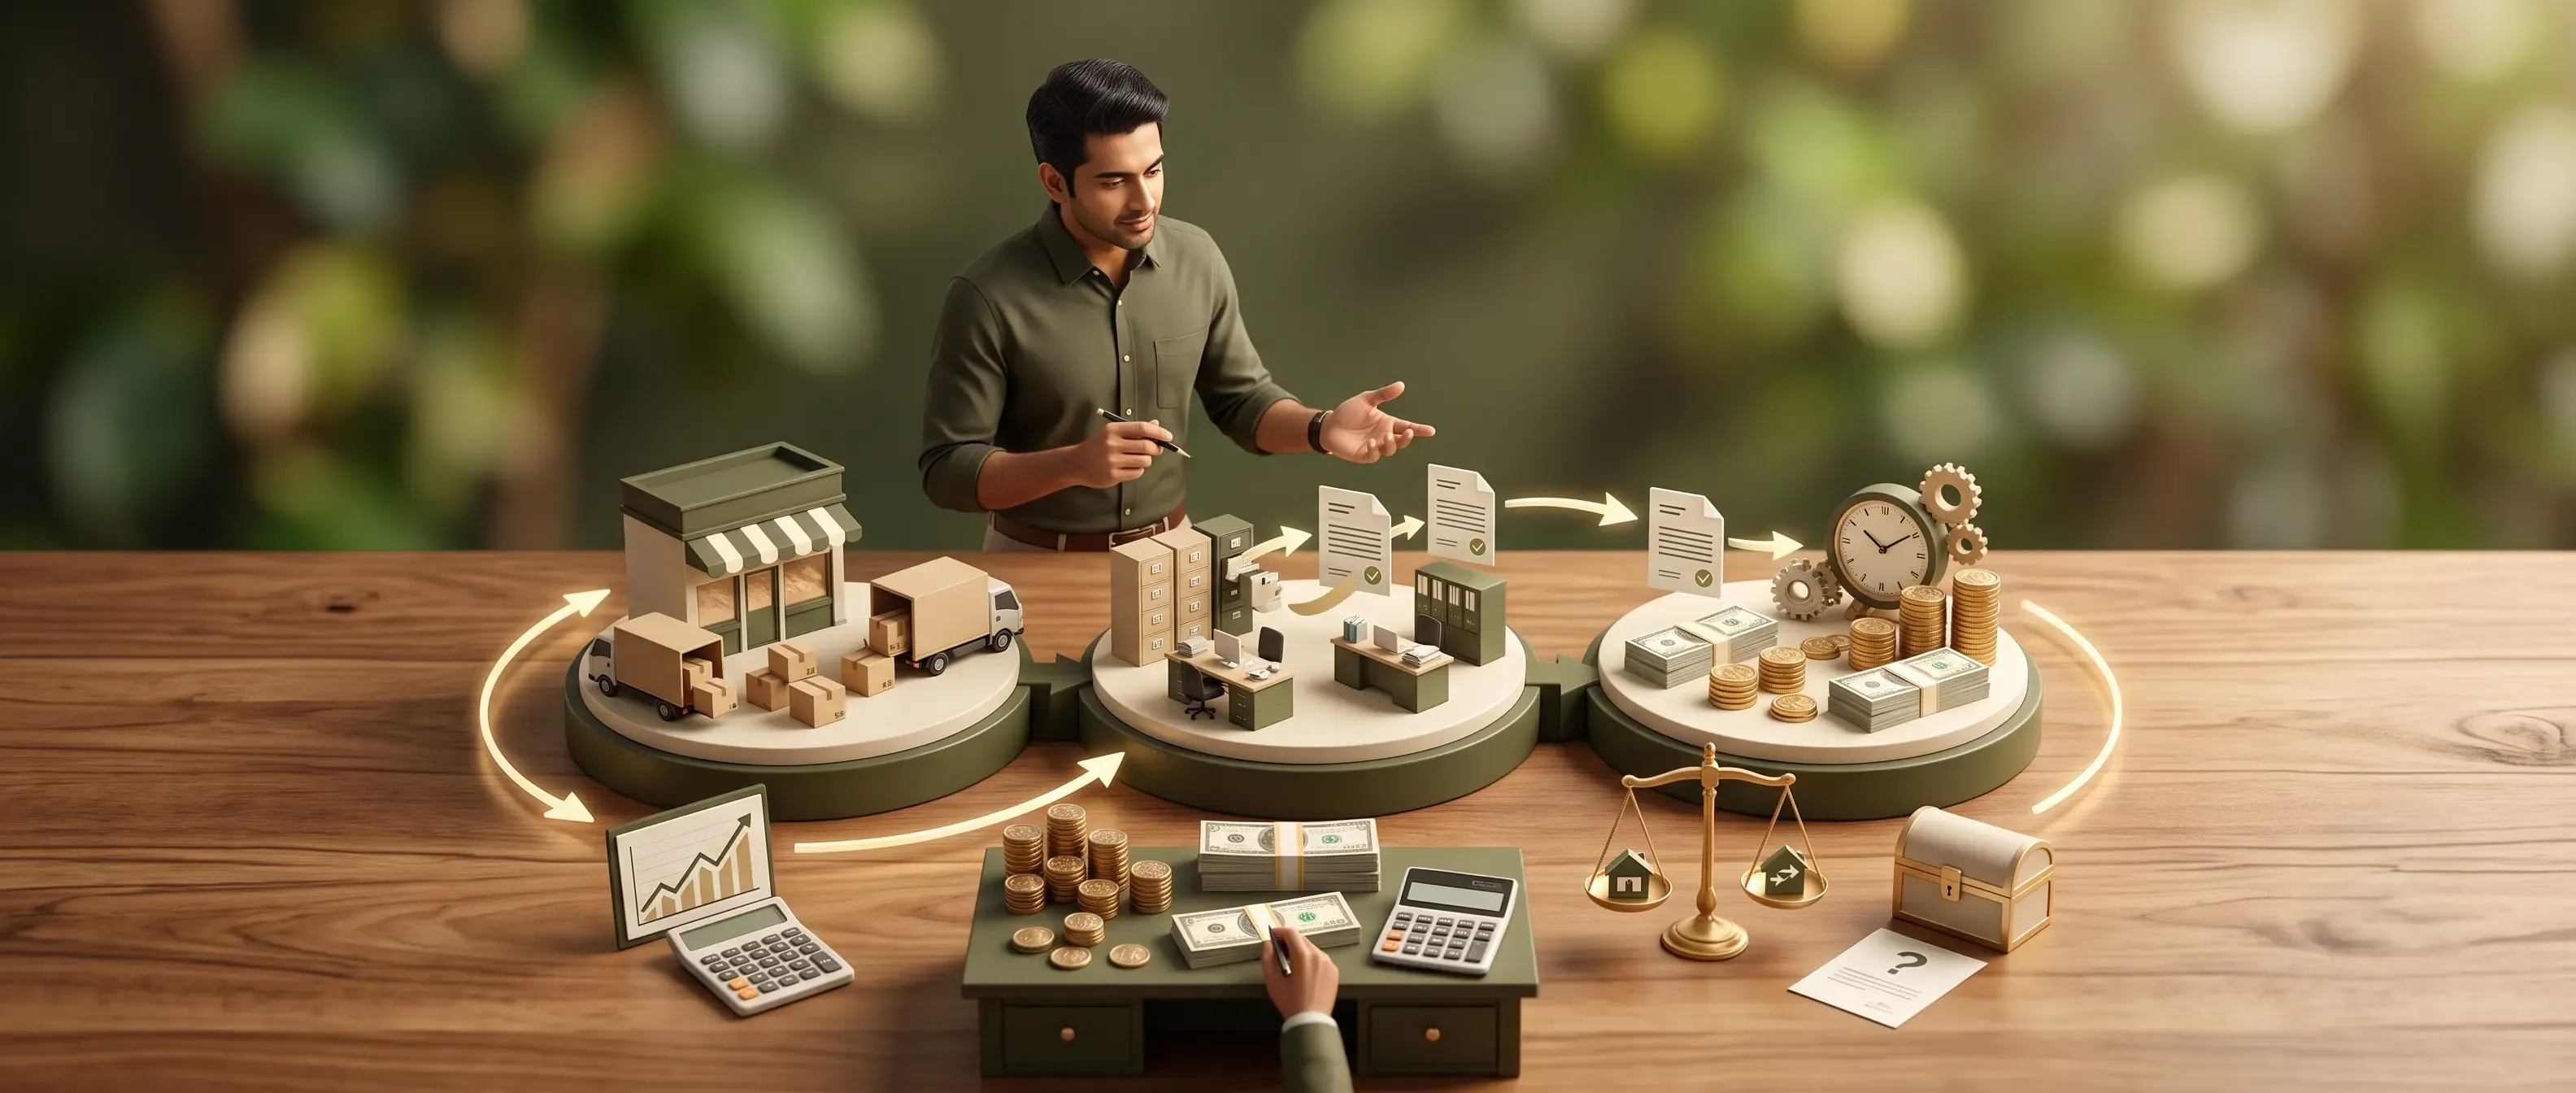
Table of content
Overview
What Is a Working Capital Cycle?
Why Is the Working Capital Cycle Important Before Taking a Business Working Capital Loan?
What Is the Cash Conversion Cycle?
How Do You Calculate a 30-Day Working Capital Cycle?
How Do You Calculate a 60-Day Working Capital Cycle?
How Do You Calculate a 90-Day Working Capital Cycle?
How Do You Calculate Working Capital Requirement?
How Does Working Capital Calculation Help Decide Your Loan Amount?
When Should a Business Consider a Working Capital Loan?
What Is a Quick Business Loan for Emergency Working Capital Requirements?
Conclusion
Frequently Asked Questions
Running short on cash right before a big order lands, or watching payroll dates creep closer while invoices sit unpaid, is a familiar headache for most small business owners. Before rushing into a business working capital loan, it helps to know how long your money actually stays tied up in day-to-day operations.
Get this number wrong, and you either borrow too little and land right back in a cash crunch, or borrow too much and pay interest on funds you never needed. This guide covers how to calculate your working capital cycle across 30, 60, and 90-day windows, work out your working capital requirement, and figure out when a business working capital loan genuinely makes sense.
Follow our Whatsapp Community for more offers and updates.
Join nowA working capital cycle is simply the number of days your cash stays locked up in inventory and unpaid invoices before it comes back to you. Shorter cycles mean healthier cash flow.
It is a continuous loop. You spend cash to buy stock, make sales, wait for client payments, and finally use that returned cash to restock.
The cycle measures how long that entire loop takes, from the moment cash leaves your account to the moment it returns.
Understanding this loop is the crucial first step before you even think about applying for a business working capital loan.
It tells lenders and you exactly how much cash your operations need and for how long. That number decides both loan amount and tenure.
The cash conversion cycle is basically another name for the same idea, and in most finance textbooks, it's used interchangeably with the working capital cycle.
It's calculated as Inventory Days + Receivable Days − Payable Days. A shorter cycle usually signals a business that collects payments fast and doesn't hoard stock unnecessarily, which is exactly the kind of profile lenders like to see before sanctioning a working capital loan.
Doing a quick working capital calculation for a 30-day cycle is beneficial for fast-paced operation. Retailers, food service vendors, and e-commerce shops usually see rapid stock turnover.
Assume inventory sits for around 15 days. Your buyers pay you within 10 days of getting their invoice. Meanwhile, you take 20 days to clear supplier dues. That's 15 + 10 − 20 = 5 days.
Businesses this fast rarely need heavy borrowing, but even a 5-day gap can strain cash if order volumes suddenly spike, and that's usually when a short-term business working capital loan bridges the mismatch.
Things shift a bit for a 60-day timeframe. Wholesalers and mid-level manufacturers often hold larger stock volumes and give buyers longer credit periods.
Suppose you keep inventory on hand for 35 days and wait a full 30 days for receivables. If you pay your own suppliers at the 25-day mark, your actual gap is 40 days (35 + 30 - 25). That math right there is your basic working capital calculation.
If a major client pays late, that gap expands quickly. This is exactly when a business working capital loan starts looking like a necessary tool to keep the lights on. It will help you keep operations moving without delaying your suppliers' payments.
A 90-day cycle usually shows up in manufacturing, construction, or B2B businesses with long production and billing timelines.
If inventory ties up cash for 50 days, receivables take 45 days to clear, and payables stretch to 35 days, the cycle comes to 50 + 45 − 35 = 60 days. That's two months of cash sitting idle, and it's exactly this stretch that pushes businesses toward a structured business working capital loan rather than dipping into savings.
Your working capital requirement is the actual rupee amount you need to fund one full cycle, not just the number of days it takes.
Working Capital Requirement = (Daily Operating Expenses) × (Working Capital Cycle in Days)
Once you know this figure, you're in a much better position to ask for the right loan amount instead of guessing.
A precise working capital calculation shows lenders exactly why you need the funds. It provides a data-backed justification for the amount you are requesting. It proves you understand your own business mechanics. When a lender sees this level of detail, getting approved for a business working capital loan becomes much easier.
Lenders typically map your requirement against your cash flow statements, seasonal sales patterns, and existing liabilities. A clean working capital calculation shows you understand your own cash gaps, and that alone can speed up approval and sometimes improve the terms offered on your business working capital loan.
A business should consider a working capital loan the moment its cycle outlasts its available cash reserves, not after the shortfall has already hurt operations. You might wonder when it's actually the right time to seek financing. A standard working capital loan makes sense under specific conditions.
For an emergency working capital requirement, digital lending platforms such as mPokket are a trusted option. They provide rapid disbursal options designed for cash flow timing issues rather than long-term asset purchases.
The entire process with mPokket happens online. From submitting your KYC and KYB details to the final bank transfer, it's seamless. The approved amount and interest rates for your business working capital loan depend entirely on risk-based pricing, which is tied directly to your financial profile.
Whether a quick loan, an overdraft, or invoice financing fits best still depends on your own cycle length and requirement, so it's worth calculating that first. Self-employed professionals can also explore similar quick personal loan options from mPokket for smaller, short-tenure needs when a full business loan isn't necessary.
Calculating your working capital cycle before applying for a business working capital loan isn't just an accounting exercise; it's what stops you from borrowing blindly. Once you know your 30, 60, or 90-day numbers, you walk into any lender conversation with a clear ask instead of a guess, and that clarity often decides whether a loan fits your cash flow or adds pressure to it.
1. What is a working capital cycle?
It measures the total time your cash remains tied up in unsold inventory and unpaid invoices before it flows back to you. The basic formula adds inventory days and receivable days, then subtracts payable days.
2. How do you calculate a cash conversion cycle?
Use the same formula as the working capital cycle: Inventory Days + Receivable Days − Payable Days. Both terms describe the same underlying calculation.
3. How do I calculate working capital requirements?
Multiply your daily operating expenses by your working capital cycle length in days to get the total cash amount your operations need to run smoothly.
4. What is a working capital loan used for?
Financing for working capital covers short-term, immediate needs. Think payroll, inventory restocking, or clearing supplier invoices. You wouldn't use a working capital loan to buy a new warehouse or heavy machinery.
5. How does the working capital cycle affect loan requirements?
A stretched-out cash conversion cycle leaves your cash locked away for longer periods. So, you’ll be needing a higher amount of cash loan for longer tenure.
5 Reasons Your Business Needs a Working Capital Loan
4 min read • 28 July 2026
How Do You Choose Between Expansion and Working Capital With Female Business Loans?
3 min read • 26 August 2026
How Self Employed Individuals Manage Cash Flow Gaps
5 min read • 8 May 2026
Instant Loan Solutions for Self-Employed Professionals Facing Cash Flow Issues
2 min read • 28 April 2026
