3 mins min read • 8 October 2026


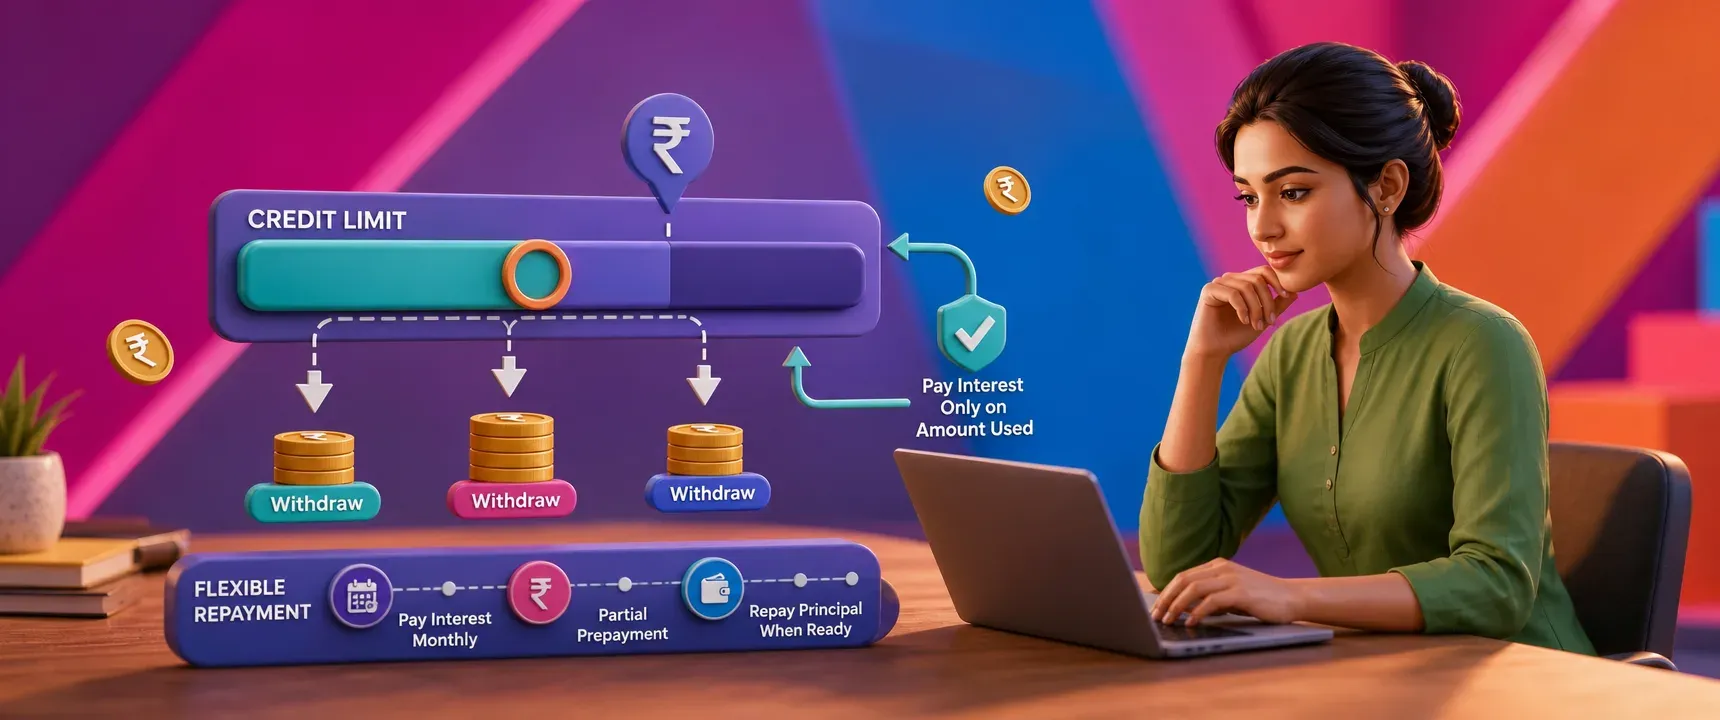
Table of content
How does a flexi personal loan work in India
Summary
How a flexi loan works
Flexi loan versus regular loan
When a flexi loan makes sense
FAQs
When your income fluctuates month to month, a fixed EMI can feel like a straitjacket. A flexi personal loan solves that problem by letting you withdraw only what you need, pay interest on the amount you actually use, and repay on terms that match your cash flow. mPokket explains the mechanics so you can decide whether this flexible credit structure fits your borrowing needs.
Follow our Whatsapp Community for more offers and updates.
Join nowWhat is a flexi personal loan? - A flexi personal loan is a pre-approved credit limit you can draw from as needed. Unlike a standard personal loan that disburses a lump sum, it gives you ongoing access to funds within a sanctioned limit.
How does interest work? - Interest is charged only on the amount you withdraw, not on the full sanctioned limit. If you repay part of the principal early, the interest obligation drops immediately.
Who benefits most? - Borrowers with variable cash flow benefit most. Salaried employees facing month end gaps, self-employed professionals with seasonal income, freelancers, and gig workers can all use a flexi loan to borrow only when necessary and reduce total interest cost.
A lender sanctions a maximum credit limit based on your eligibility. You do not receive the entire amount at once. Instead, you withdraw funds whenever a need arises, up to that limit.
Interest accrues only on the withdrawn balance. If your limit is Rs 1,00,000 and you withdraw Rs 40,000, you pay interest on Rs 40,000 alone. The remaining Rs 60,000 sits unused at zero cost.
Repayment is equally flexible. You can choose to pay only the interest component each month and return the principal when your cash flow allows. Alternatively, you can make partial prepayments at any time. Each prepayment reduces your outstanding balance and, therefore, your interest burden going forward.
A regular personal loan disburses the full sanctioned amount on day one. You begin paying EMI immediately on the entire principal, regardless of whether you needed all of it right away.
A flexi personal loan, by contrast, separates sanction from withdrawal. You draw funds in portions and repay at your own pace within the agreed tenure. This structure can help reduce total interest outgo significantly when you do not need the full amount continuously.
For someone with predictable expenses and steady income, a fixed EMI loan works well. For someone whose expenses arrive unevenly, a flexi loan offers breathing room without the penalty of paying interest on idle funds.
Consider a self-employed shopkeeper who needs working capital for inventory restocking every few weeks but not a large lump sum. A flexi loan lets the shopkeeper withdraw Rs 20,000 this week, repay Rs 15,000 next week after sales, and withdraw again the following month.
Salaried employees facing a month end cash crunch can withdraw a small amount before payday and repay once the salary is credited. Freelancers with project-based income can draw funds between client payments and settle the balance when invoices clear.
mPokket highlights that this structure is designed to align repayment with actual earnings, which can help borrowers avoid the stress of rigid monthly installments during lean periods. Platforms offering flexible repayment loans typically allow repayment through UPI, autopay, or in-app methods, making the process paperless and convenient.
A flexi personal loan is a credit facility where a lender sanctions a limit and the borrower withdraws funds as needed. Interest applies only to the withdrawn amount, not the full limit, which can help reduce overall borrowing cost.
A regular personal loan disburses the entire sanctioned amount at once with fixed EMIs. A flexi loan lets you withdraw in parts and repay flexibly, so you pay interest only on the amount you actually use.
Borrowers with variable or irregular cash flow benefit most. This includes self-employed professionals, freelancers, gig workers, and salaried employees who face periodic month end gaps before their next paycheck.
What Is an Instant Flexi Loan and How Does It Work?
4 min read • 13 July 2026
Do the Revised MSME Classification Limits Change MSME Loan Eligibility?
2 min read • 10 September 2026
Should You Prepay Your Personal Loan? Benefits and Things to Consider
4 min read • 21 July 2026
Need ₹10,000 Urgent Loan Today — What Should You Do To Get It Fast?
4 min read • 30 April 2026
